


Brown & Brown (BRO) just posted third quarter results showing higher revenue and net income compared with a year earlier, while also rolling out its COMPASS data and AI platform for insurance decision-making.
Brown & Brown’s recent news has arrived alongside a sharp 30 day share price return of 19.98% and a 1 day move of 3.04%, even though the year to date share price return is down 7.40% and the 1 year total shareholder return is down 6.74%. This suggests that enthusiasm around the COMPASS launch and earnings update is building from a weaker longer term base.
Spot opportunities riding similar data and AI tailwinds by scanning our hand picked 40 profitable AI stocks that aren't just burning cash that pair real earnings with applied machine learning.The sharp rebound in Brown & Brown’s share price could be read as a clear vote of confidence in the business or as a short burst of optimism around COMPASS and earnings. The valuation work now shows which story fits better.
Most Popular Narrative: 4% Undervalued
Against Brown & Brown’s last close of $71.88, the most followed narrative pegs fair value at about $74.75 using a 7.24% discount rate and incorporates the firm’s cash generation, acquisitions and AI driven process changes.
Brown & Brown is rolling out AI enabled submission, policy checking and billing tools that are already saving tens of thousands of hours a year and automating more than 25% of the submission process in many programs, which can free producers and underwriters to handle more volume and support future organic revenue growth and operating margin resilience.
See why 31 investors see Brown & Brown as 4% undervalued.
Result: Fair Value of $74.75 (UNDERVALUED)
Still, the Brown & Brown story can be knocked off course if producer departures drag on Retail revenue or if weaker CAT property pricing continues to squeeze program income.
Find out about the key risks to this Brown & Brown narrative.
Another View: What Brown & Brown’s P/E Is Telling You
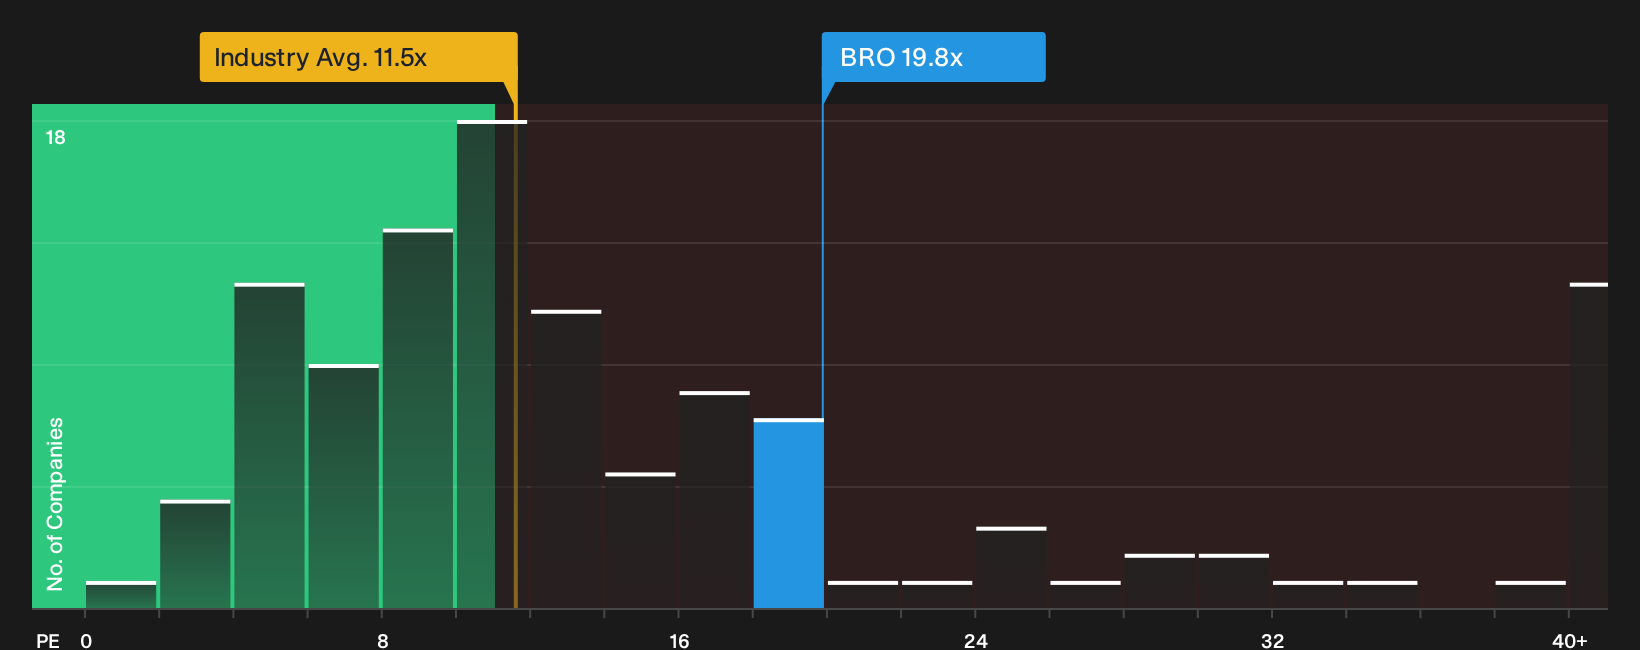
The SWS DCF work suggests Brown & Brown is undervalued, yet the market is already paying 19.8x P/E for the stock. That is richer than both the US Insurance industry on 11.5x and the fair ratio of 13.1x, so buyers are paying up today for earnings that models already flag as mispriced. Which signal do you trust more right now?
For a closer look at how that earnings multiple compares with the fair ratio and peers in more detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Brown & Brown is split, with both genuine concerns and clear bright spots in focus. If you want to move faster than the crowd and ground your view in the underlying data, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Brown & Brown?
Do not stop with Brown & Brown. Broaden your watchlist now so you keep fresh opportunities in sight instead of reacting after the easy gains have passed.
- Target quality at a discount by scanning our hand picked 34 high quality undervalued stocks that line up robust fundamentals with prices that may not fully reflect them.
- Prioritise resilience by using the 29 resilient stocks with low risk scores to focus on companies with steadier risk profiles that can help balance bumpier positions in your portfolio.
- Hunt for potential future standouts early through the 19 high quality undiscovered gems and spot lesser known businesses with strong underlying numbers before attention fully arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com