


Sustained ETF buying in JPMorgan Chase (JPM) has put the stock back in focus, as institutional flows line up with the bank’s own research that highlights a broad profit cycle tied to AI investment.
Recent trading has been constructive for JPMorgan Chase, with the share price gaining 1.96% over the past week and 2.47% over the last month, even though the 90 day share price return declined 4.74%. The 1 year total shareholder return of 12.22% and very large 3 year total shareholder return point to momentum that has cooled short term rather than broken, against a backdrop of Q3 earnings coming in below expectations, ongoing fixed income issuance and a new senior data infrastructure hire tied directly to the bank’s AI ambitions.
Scan how ETF flows into JPMorgan Chase compare with peers by zeroing in on 53 AI infrastructure stocks following the same AI driven build out theme.
After a strong three year run and a softer 90 day patch, JPMorgan Chase now trades with an implied 31% discount to its intrinsic value estimate and an 8.8% gap to the average analyst target. Does that still skew the risk reward toward buyers?
Most Popular Narrative: 8% Undervalued
On the most followed thesis, JPMorgan Chase screens as modestly undervalued, with a fair value of $370.39 against the recent $340.58 close. That gap sits alongside long term profit growth and a diversified banking and asset management mix that many investors already know well.
JPMorgan is the best-run large bank in the world, a diversified "fortress balance sheet" spanning consumer, corporate, investment banking and asset management. It is my financial-sector anchor and a source of steady dividends.
See why 20 investors see JPMorgan Chase as 8% undervalued.
According to duarte_EM, that fair value of $370.39 bakes in moderate earnings growth assumptions, a conservative 8.0% discount to intrinsic worth and a cyclical profile rather than a high growth story. The same thesis highlights income through dividends and the potential to add during weaker periods as central to how some holders treat JPMorgan Chase in a portfolio.
Result: Fair Value of $370.39 (UNDERVALUED)
Still, that income focused JPMorgan Chase thesis can be knocked off course if a weaker credit cycle hits loan books hard or if regulation tightens and compresses returns.
Find out about the key risks to this JPMorgan Chase narrative.
Another View: What JPMorgan Chase’s P/E Is Telling You
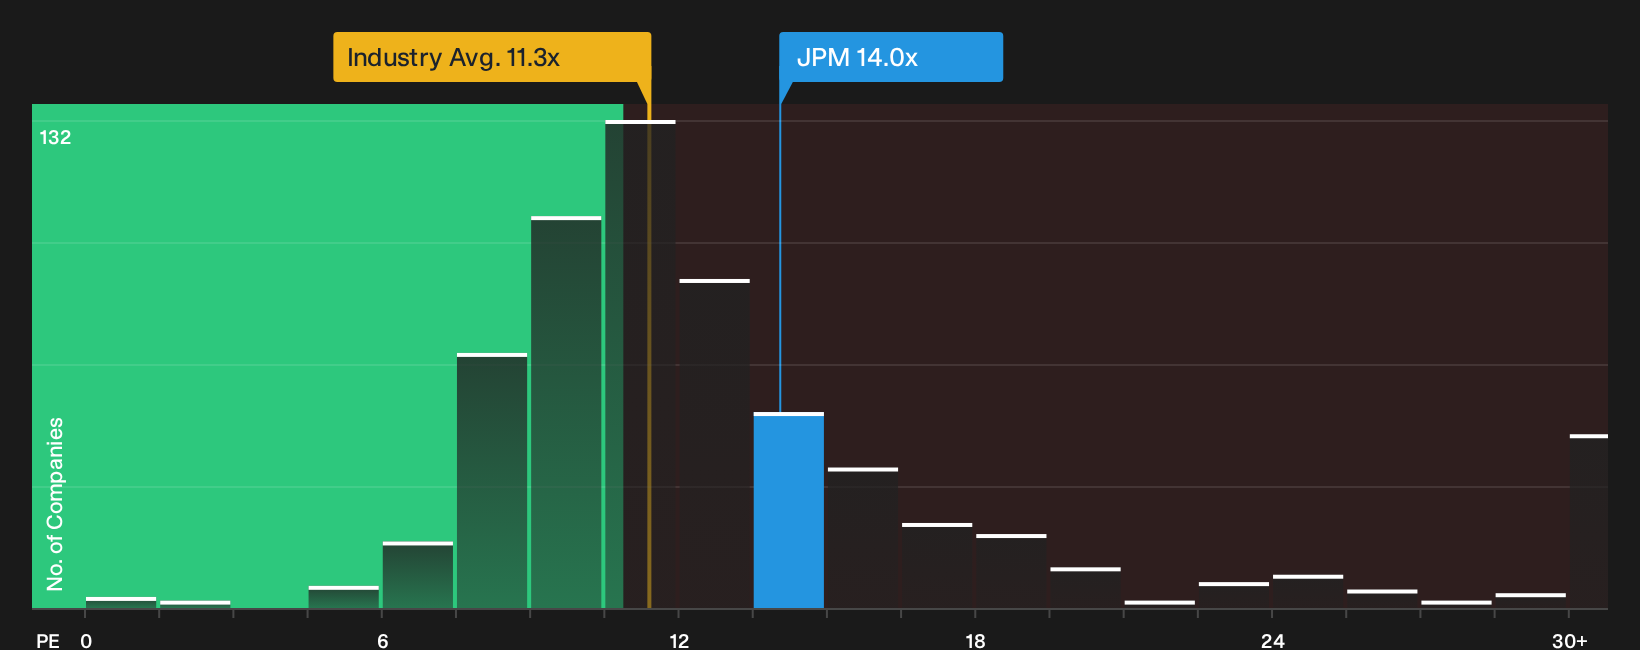
Through a simple P/E lens, JPMorgan Chase looks less generous than that 31% discount to intrinsic value suggests. The bank trades around 14x earnings compared with 11.3x for the US Banks industry and 11.6x for close peers, even though the fair ratio sits near 14.3x. Is that premium a comfort or a risk for anyone relying on the undervalued story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk can be useful fuel, especially when you move beyond headlines. Act while the details are fresh and weigh the potential benefits against the hazards with the help of 3 key rewards and 1 important warning sign
Looking for more ideas beyond JPMorgan Chase?
Do not stop with one bank. Broaden your watchlist with a few focused screens that can surface very different types of opportunities before the crowd notices.
- Target reliable income streams by scanning companies built around strong payouts with the help of 4 dividend fortresses.
- Hunt for quality at a discount by zeroing in on financially sound opportunities through 19 high quality undiscovered gems.
- Prioritise capital preservation by filtering for resilient businesses using the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com