


Earnings momentum and credit costs in focus
Cathay General Bancorp (CATY) just posted third quarter and nine month results that showed higher net interest income and net income than a year earlier, alongside a rise in net charge-offs.
Investors tracking Cathay General Bancorp will likely weigh this mix of stronger profitability metrics against the increase in credit losses. The latest figures arrive with markets already aware that the bank's share price has risen this year.
The share price of Cathay General Bancorp has gained 34.72% year to date, with a 7.77% 1 month share price return. The 1 year total shareholder return of 47.77% and 3 year total shareholder return of 95.23% point to strong momentum building around the latest earnings story.
Scan beyond Cathay General Bancorp and see which other banks are showing similar earnings momentum with controlled risks by reviewing the hand picked 29 resilient stocks with low risk scores.
Cathay General Bancorp now appears to be a solidly profitable regional bank with a strong recent increase in its share price. The key issue is whether that earnings strength is already fully reflected in today's valuation.
Most Popular Narrative: 1% Overvalued
Cathay General Bancorp closed at $65.57, almost exactly in line with a narrative fair value of $65 that uses a 7.24% discount rate and treats recent earnings power as largely captured in the price.
Continuing expansion of Cathay General Bancorp’s wealth management offerings, which management highlights as a key driver of rising core noninterest income to about US$20.3 million in Q2 2026, supports further fee revenue growth that does not depend on balance sheet size.
See why 4 investors see Cathay General Bancorp as 1% overvalued.
Result: Fair Value of $65 (ABOUT RIGHT)
Still, Cathay General Bancorp faces real swing factors, including its commercial real estate concentration and funding costs that could squeeze returns if conditions shift against those assumptions.
Find out about the key risks to this Cathay General Bancorp narrative.
Another view on Cathay General Bancorp valuation
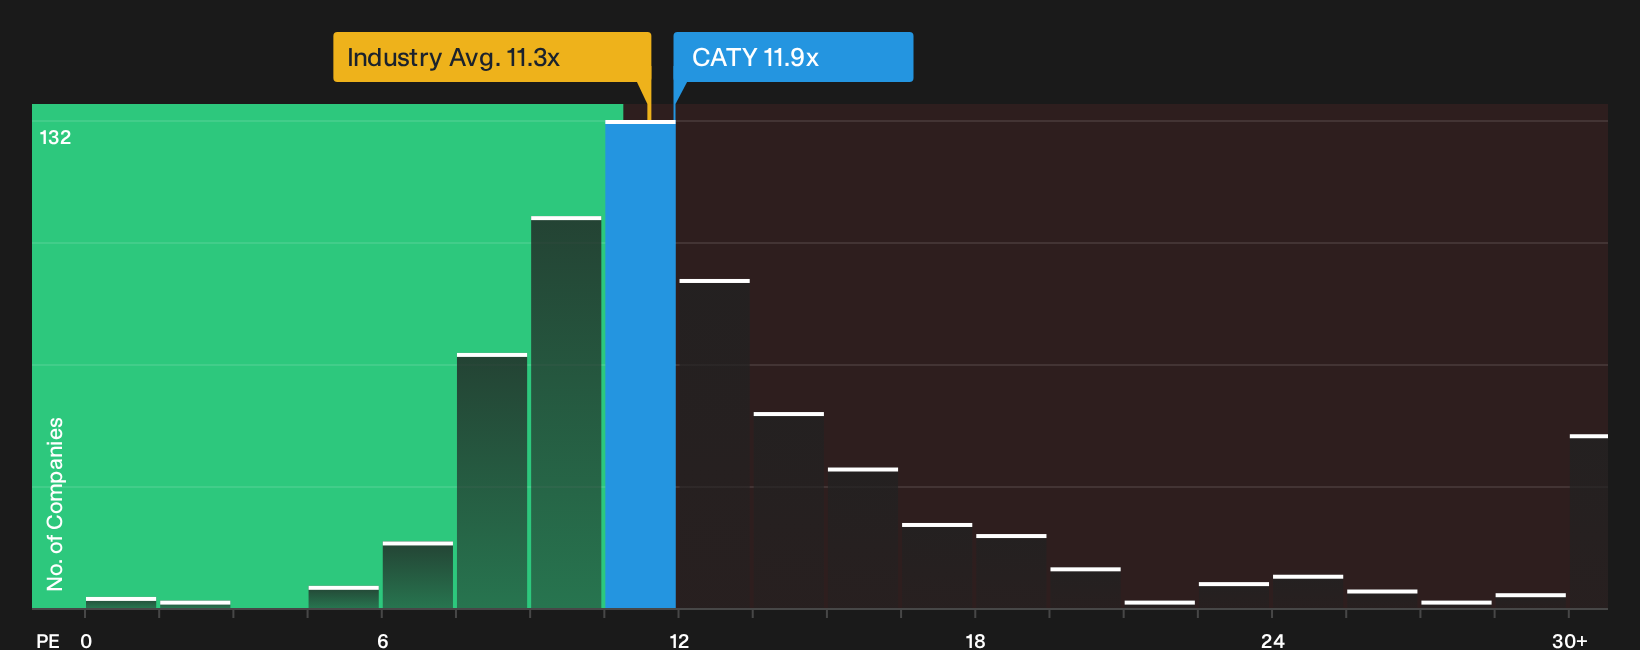
The first narrative frames Cathay General Bancorp as roughly fairly priced, yet the current P/E of 11.9x sends a mixed message. It sits above the US Banks industry on 11.3x, and just above a fair ratio of 11.8x. That tiny premium keeps upside tight if sentiment cools.
This kind of narrow gap between the actual P/E, peers, and the fair ratio can work in both directions. It limits obvious mispricing, but it also leaves less room for error if earnings progress slows or the sector falls out of favor. The key question is whether you are comfortable being paid mainly through ongoing earnings and dividends, rather than expecting a big re rating.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Cathay General Bancorp so far and not sure where you land. Move quickly and stress test your own view by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Cathay General Bancorp?
If Cathay General Bancorp has sharpened your thinking, do not stop there. Use the Simply Wall Street Screener to widen your watchlist and pressure test your next moves.
- Target powerful combinations of quality and value by reviewing a hand picked 34 high quality undervalued stocks that may offer stronger fundamentals than their current prices suggest.
- Strengthen portfolio resilience by scanning a curated list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with sturdier financial footing.
- Get ahead of the crowd by checking a focused 19 high quality undiscovered gems that highlights stocks many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com