


BioNTech has been under pressure for years, and the stock’s long slide now raises a very specific question for investors. Is the current share price still in line with what the company’s sales can reasonably support, given where the business is today?
- The share price has declined 63.6% over the past 5 years, which puts the focus squarely on whether the business now generates enough revenue to back even this lower valuation.
- Recent oncology trial updates, including mixed yet progressing data in breast cancer, may influence how investors think about future product revenue streams and the timing of any meaningful sales contribution beyond Covid-related products.
- There is a second opinion on BioNTech worth weighing. See what analysts think BioNTech's shares could be worth.
For investors, the debate is whether BioNTech’s current market value is adequately grounded in its sales today rather than in hopes for what its pipeline might deliver years down the line.
If you are weighing BioNTech’s recent slide against its current revenue base, it can help to compare that setup with other companies screened for 34 high quality undervalued stocks
Has BioNTech Run Too Far on Sales?
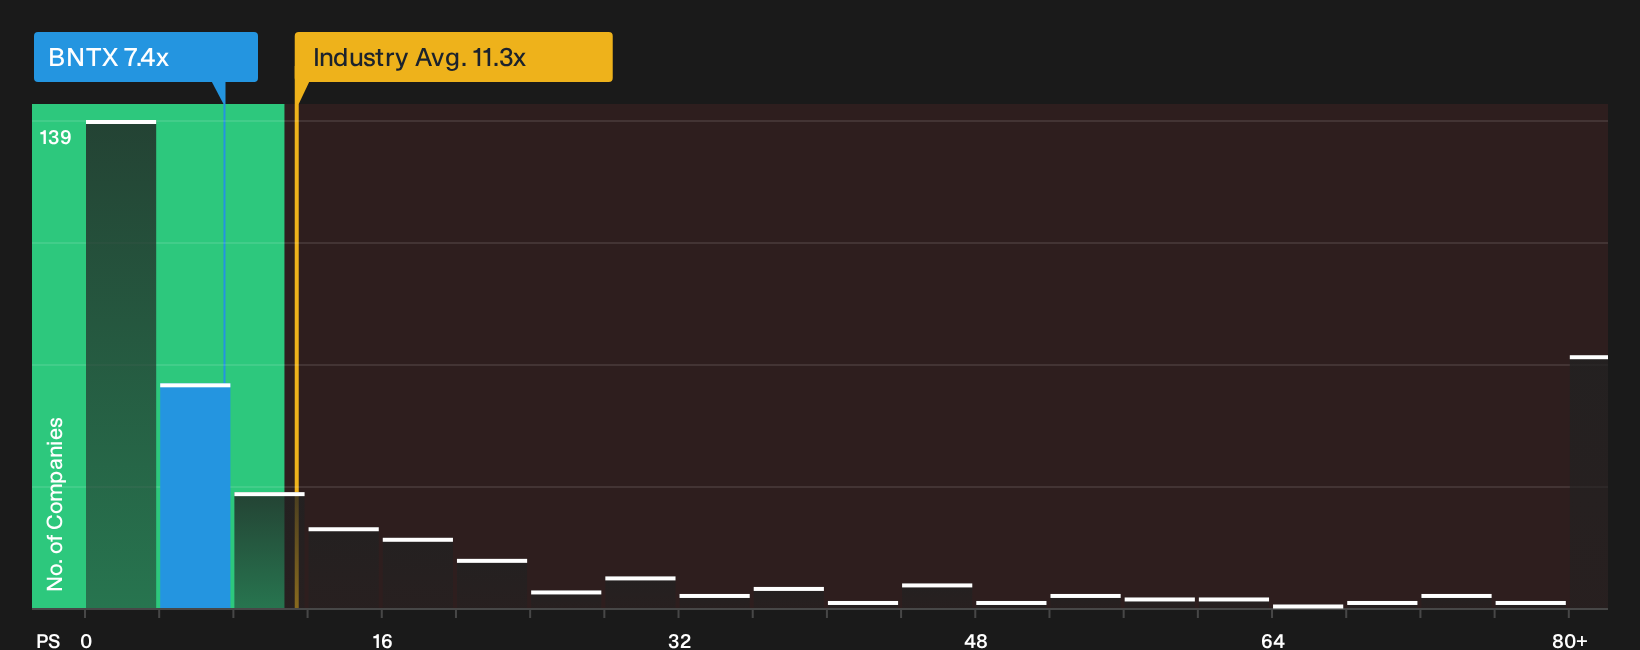
P/S is a useful lens for BioNTech because its Covid and oncology focus can leave earnings and cash flow noisy while revenue remains a clearer anchor. On this measure, the stock trades at about 7.4x trailing sales, compared with roughly 11.3x for the wider Biotechs industry and around 5.7x for closer peers. That leaves BioNTech priced above a peer basket but below the broader group.
Based on the tailored fair P/S, the current 7.4x level screens as overvalued rather than cheap on sales alone. The recent DYNASTY-Breast02 trial result, which brought mixed yet progressing data in metastatic breast cancer, keeps attention on the oncology pipeline. However, the market multiple suggests investors already pay a relatively full price for the revenue base that exists today. For you, the question is whether the existing sales mix and pipeline risk justify that richer P/S tag or point to better value elsewhere. Explore the numbers behind BioNTech's P/S valuation.
The BioNTech Narrative: What Would Justify Today's Price?
Narratives pick up where the BioNTech valuation puzzle leaves off. They spell out which assumptions on future growth, margins and earnings would need to hold for the stock to be worth materially more or less than the current price, and each one links a fair value to a specific mix of potential catalysts and risks so you can track over time which version of BioNTech's story appears closer to reality on Simply Wall St's Community page.
Bulls and bears on BioNTech are looking at the same oncology pivot and COVID reset, then reaching sharply different conclusions about what the stock is worth.
Bull case: 25% undervalued
"The current valuation implies the share price gives limited credit to the size of BioNTech’s late stage oncology pipeline and sizeable cash balance…"
Discover why this Narrative puts BioNTech at 25% undervalued.
Bear case: 12% overvalued
"The numbers imply that BioNTech’s current share price assumes successful diversification into oncology and effective cost savings that outweigh structurally lower COVID-19 revenues and ongoing net losses…"
Explore why this Narrative puts BioNTech at 12% overvalued.
BioNTech’s valuation still leaves one crucial piece of the story unanswered
Price to sales tells you where BioNTech trades today, but the next layer is how professional analysts currently map out its revenue and earnings profile a few years from now. Explore where analysts expect BioNTech to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com