


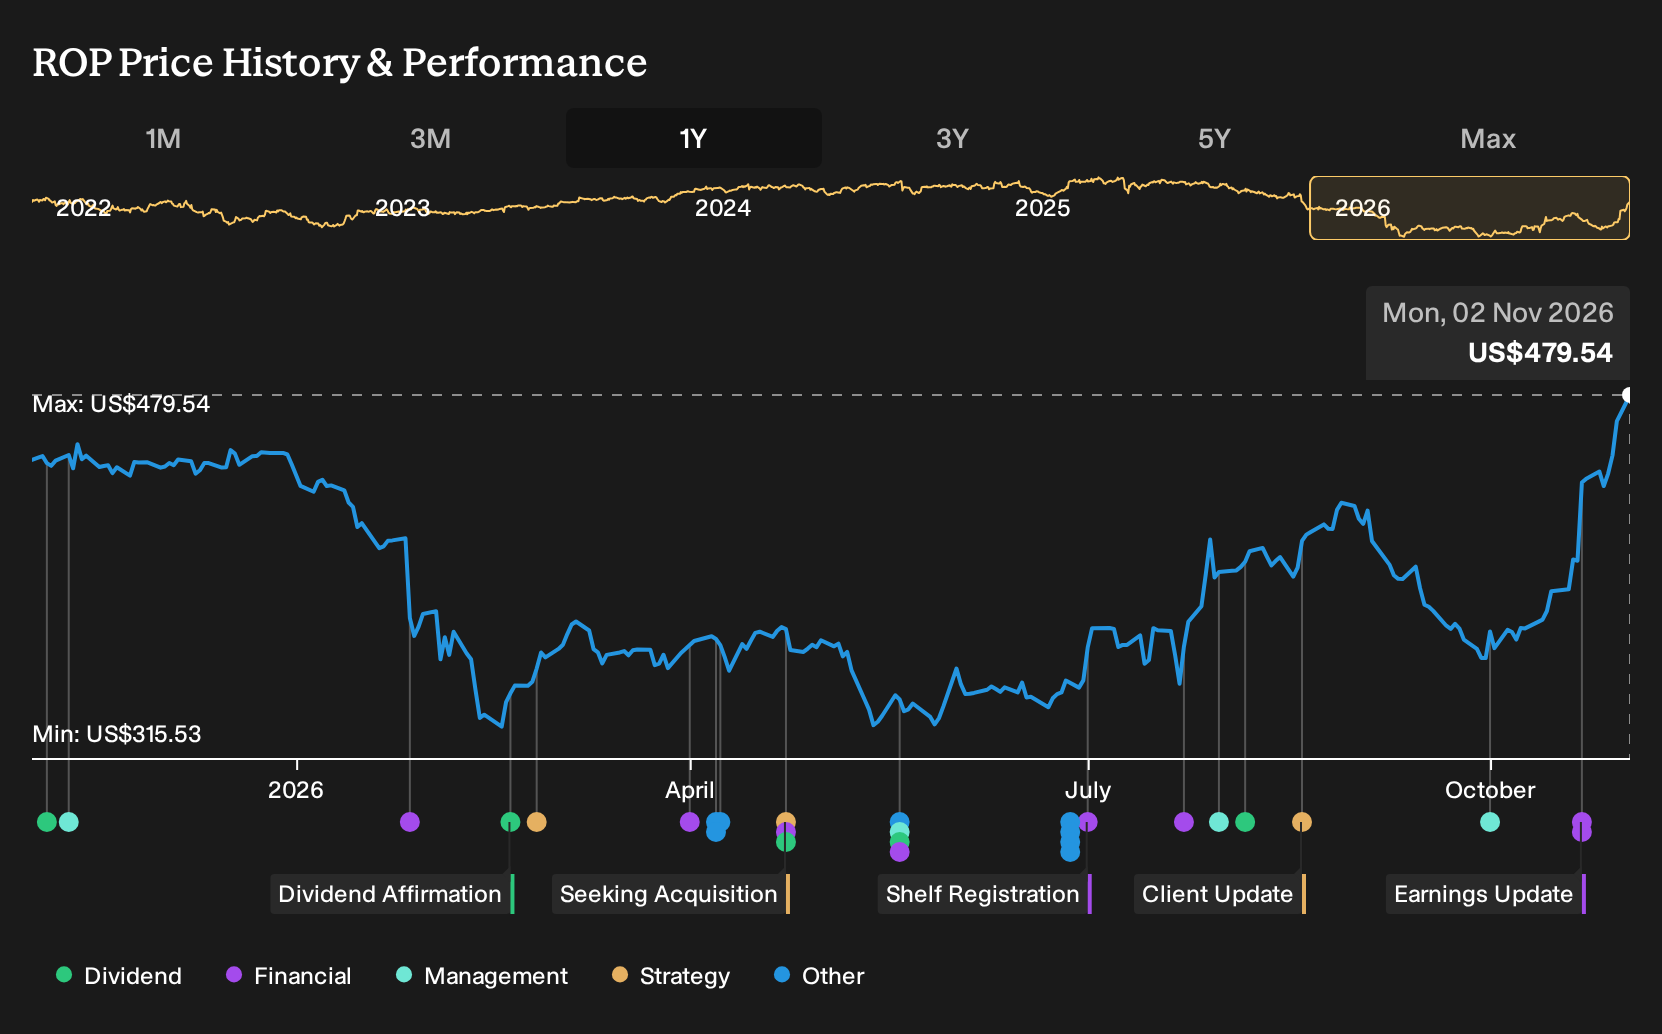
- Roper Technologies reported third quarter 2026 sales of US$2,171.8 million and net income of US$484.7 million, with diluted EPS from continuing operations of US$4.88. The company also issued fourth quarter GAAP DEPS guidance of US$4.27 to US$4.32 and full year 2026 GAAP DEPS guidance of US$25.60 to US$25.65.
- The business currently combines a P/E of 18.5x with recent 7.6% revenue growth and 32.6% EPS growth. This interacts directly with guidance that points to GAAP DEPS above US$25 for 2026.
- The following section examines how Roper Technologies’ earnings profile and updated GAAP DEPS guidance could influence its existing investment narrative.
Roper Technologies Investment Narrative Recap
To own Roper Technologies, you need to be comfortable with a software heavy portfolio that leans on recurring revenue, disciplined M&A and steady cash generation rather than big cyclical swings. The third quarter print and GAAP DEPS guidance reinforce that story rather than change it. In the near term, the key swing factor is whether vertical software units keep absorbing AI tools and new modules fast enough to support usage and pricing.
The biggest risk is still execution on acquisitions and integration, especially with more than US$5b earmarked for earlier life cycle software assets. Softer pockets of demand in areas such as government related software or logistics remain an operational watchpoint, but the latest quarterly numbers do not materially alter that risk hierarchy.
The fresh full year 2026 GAAP DEPS outlook of US$25.60 to US$25.65 is the announcement that really matters here. It ties the strong nine month EPS print of US$21.30 on a diluted basis to a concrete earnings bridge for the final quarter and provides a clearer view of how Roper Technologies is converting its portfolio into profit per share.
For catalysts, that guidance range frames how much room management has to keep investing in AI enabled products and to pursue M&A without diluting returns. It also intersects with the current 18.5x P/E, since any stumble against that DEPS range would quickly refocus attention on acquisition risk, integration complexity and the durability of free cash flow across Roper Technologies’ 29 businesses.
Roper Technologies' current analyst narrative points to forecast revenue of US$10.2b and earnings of US$2.1b by 2029, built on assumed annual top line growth of 6.5%. That profile implies a decline of US$500m in earnings from about US$2.6b today to the 2029 consensus level.
Uncover why Roper Technologies' fair value indicates a 5% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into AI as a potential upside catalyst for Roper Technologies, highlighting portfolio wide AI agents and early AI bookings when they were penciling in revenue of about US$10.5b and earnings of US$2.1b by 2029. Those projections came before this new guidance, so you may see sentiment shift as the latest numbers are absorbed.
Explore 2 other Roper Technologies fair value estimates, including one that suggests the potential for as much as 10% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Roper Technologies research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Roper Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Roper Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Roper Technologies?
Once you have a view on Roper Technologies, it can help to compare it against a wider field of businesses with different balance sheet profiles, income streams and risk levels. The Simply Wall St Screener lets you do that in a structured way so you are not just reacting to headlines or the latest quarterly print.
- If capital preservation is your priority, focus on resilient businesses with steadier profiles and use our screener of 29 resilient stocks with low risk scores to see which ones line up with that mindset.
- If balance sheet strength matters most to you, filter for companies with cleaner finances and consistent fundamentals through this list of solid balance sheet and fundamentals (24 results).
- If you are hunting for opportunities that the market may not be paying full attention to yet, start with this curated set of 19 high quality undiscovered gems that already pass a quality filter.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com