


Australia’s central bank has lifted interest rates to an 18 year high at 4.85%, which makes dependable cash generation matter much more than headline earnings stories. When money is no longer cheap, investors often look for Canadian companies where share prices lag the underlying cash flowing through the business. This article highlights three such stocks that currently screen as attractively priced on their cash flow potential.
The three companies below are just a sample of those that currently look interesting on a discounted cash flow lens, and the wider screen has surfaced 6 more businesses with equally compelling cash generation stories that are not covered here.
If you want to identify and analyze potential value ideas built on projected cash flows and current pricing, head straight to the Undervalued Stocks Based On Cash Flows screener.
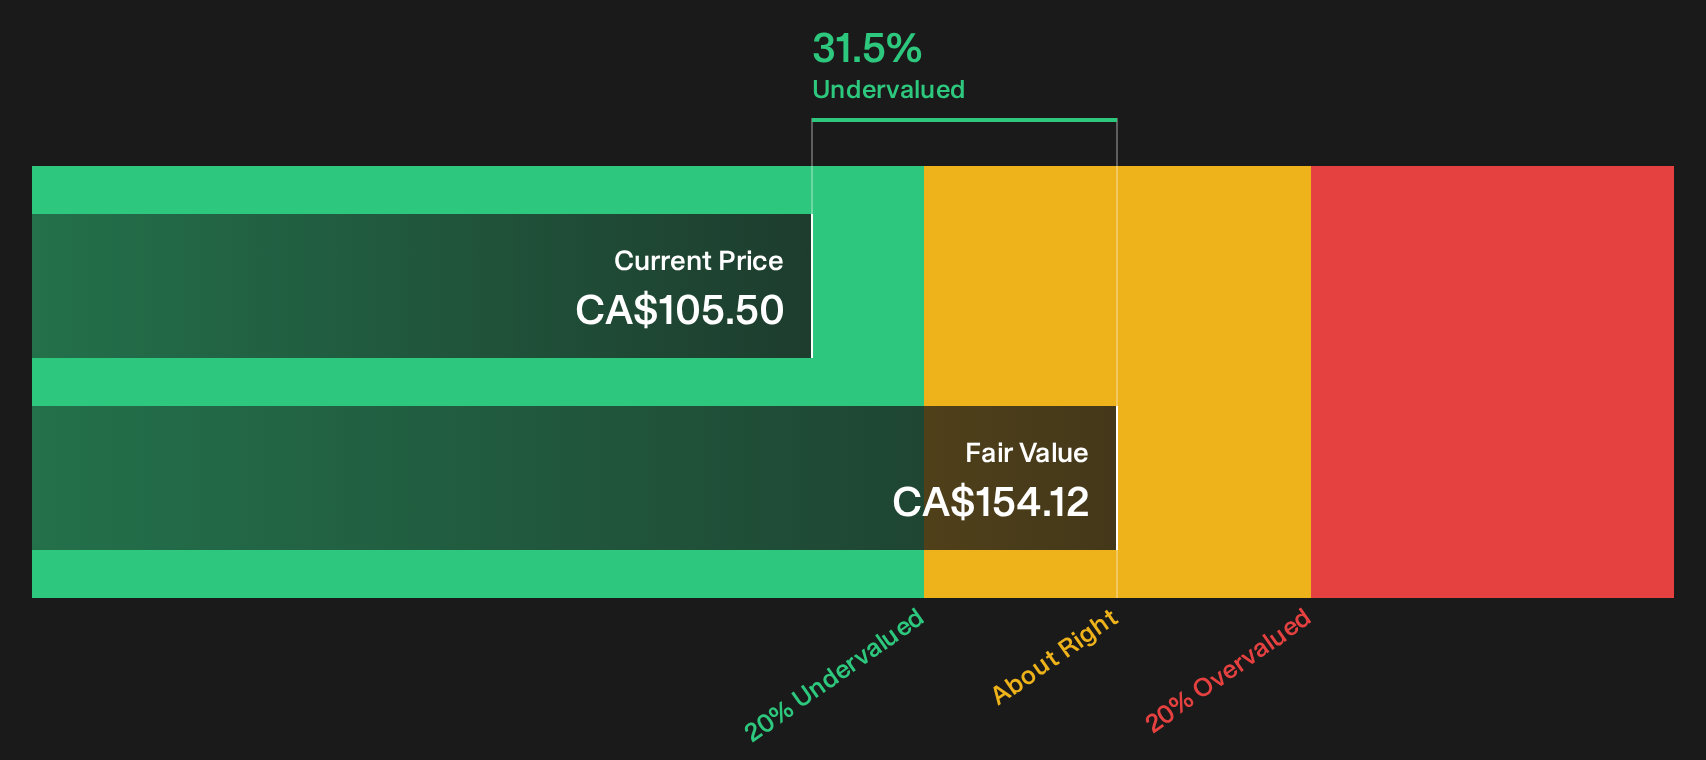
Suncor Energy (TSX:SU)
Suncor Energy is a large integrated producer where long-life Oil Sands operations supply bitumen that feeds its own refineries, creating a tight link between physical barrels and the cash flow profile that lands it in this discounted cash flow screen.
Suncor Energy runs oil sands production, offshore exploration and refining operations, with about CA$26.9b from Oil Sands and CA$36.8b from Refining and Marketing, while Exploration and Production contributes CA$2.5b. The business has a market value of about CA$130b.
"Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels."
What happens to that cash flow story if one unseen pressure quietly starts to squeeze margins at the wrong point in the cycle?
If that margin pressure risk is on your mind, the full narrative for Suncor Energy explains in detail where cash generation could diverge from headline earnings and what might quietly be accelerating beneath the surface.
DPM Metals (TSX:DPM)
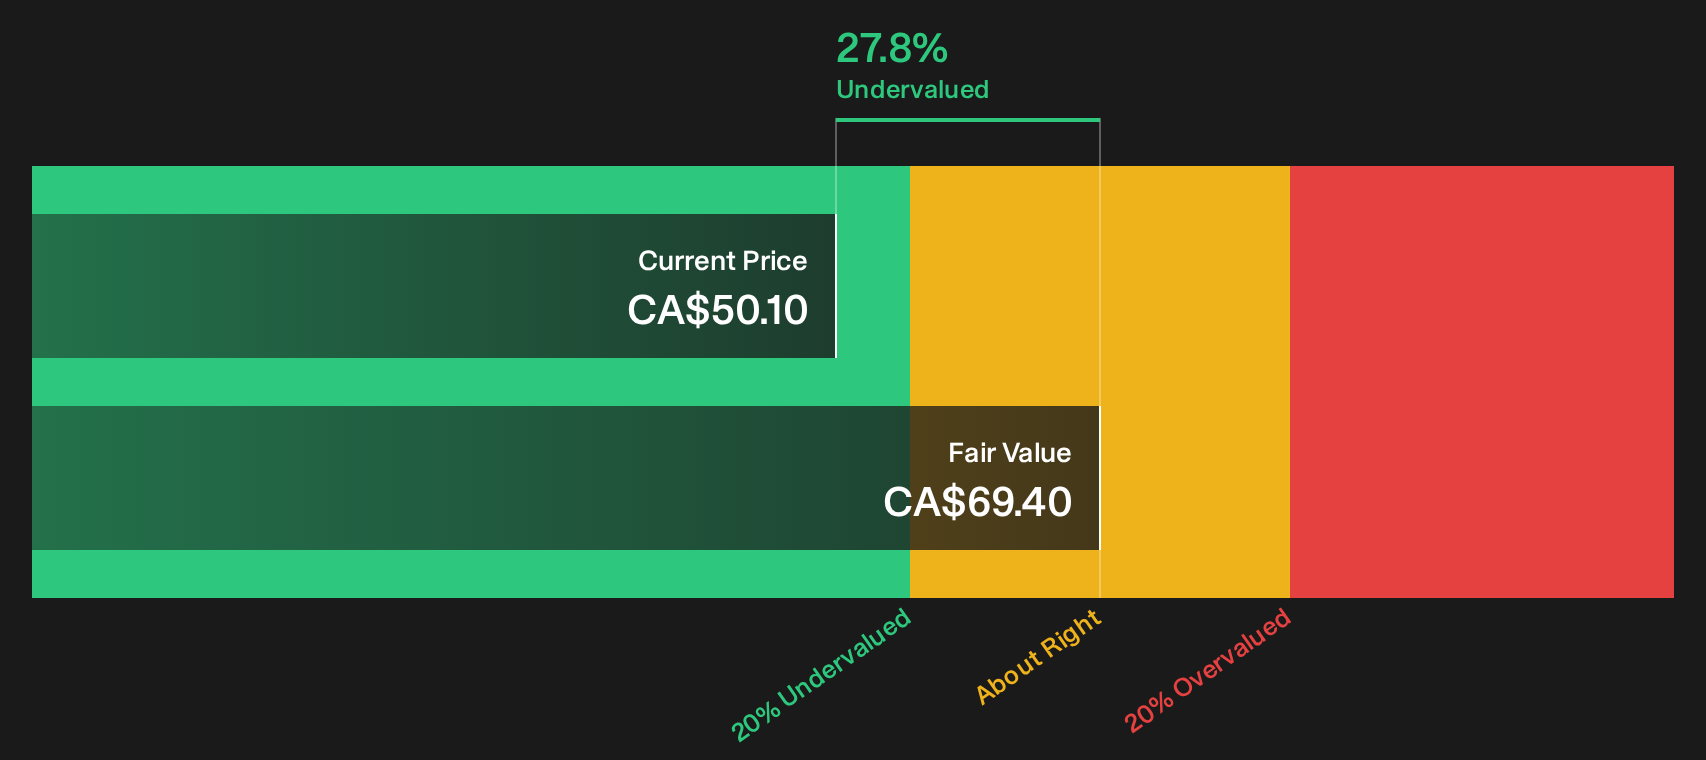
DPM Metals is a Toronto based precious metals producer focused on gold led projects that feed directly into cash flow driven valuation work, with revenue mainly coming from the Chelopech mine at about US$744 million and Ada Tepe at roughly US$275 million, and a market value near CA$11.1b.
For investors hunting undervalued cash flow, DPM Metals matters because its producing assets and project pipeline give analysts something concrete to plug into discounted cash flow models instead of just blue sky exploration stories.
"The Vareš mine is contributing to record quarterly free cash flow and is targeting an 850,000 tonne per year run rate by year end."
What really moves the needle from here is how one pressure on future profitability resolves over the next few years.
That unresolved pressure is exactly why the full narrative for DPM Metals digs into how DPM Metals’ cash engine could accelerate or stall as the next phase plays out.
Imperial Oil (TSX:IMO)
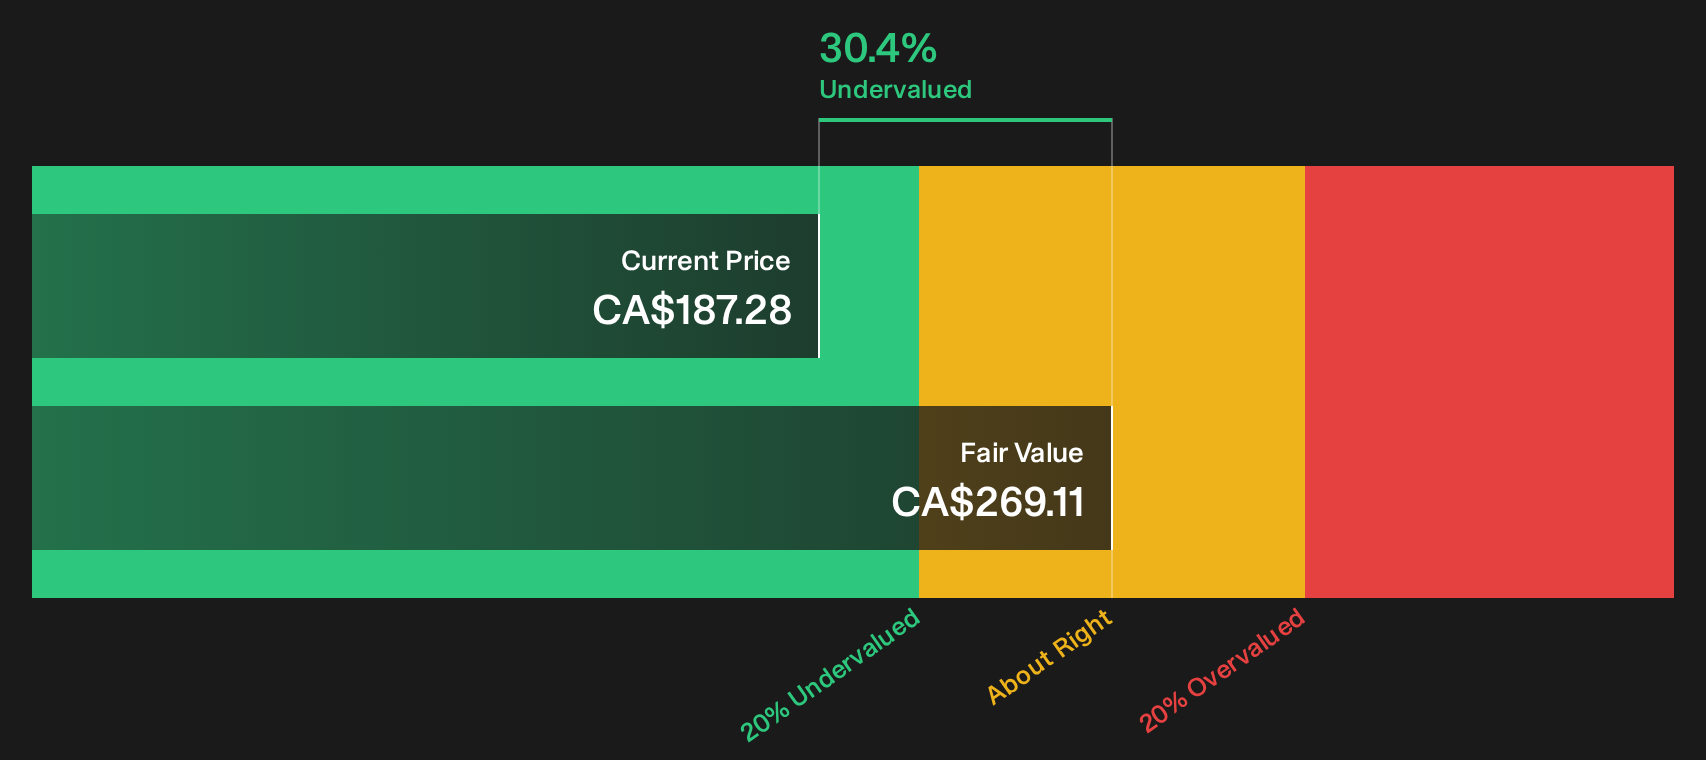
Imperial Oil is an integrated energy producer where upstream crude oil, natural gas, synthetic crude and bitumen output anchors the cash flow story that fits this undervalued DCF screen. Downstream refining and chemicals add extra earnings power on top of that production base.
Imperial Oil generates most of its income from downstream operations at about CA$61.7b, with upstream contributing roughly CA$18.2b and chemicals around CA$1.5b. The group carries a market value near CA$91.3b.
For investors focused on cash flow driven value, Imperial Oil brings together long life production, a sizeable refining network and petrochemical assets that all convert barrels into hard numbers. This is exactly what this discounted cash flow theme is looking to capture.
"Ramped up solvent assisted SAGD at Cold Lake, with Grand Rapids producing above 20,000 bpd, Leming SAGD moving toward 9,000 bpd and the planned 30,000 bpd Mahihkan start up in 2029, points to a production mix shift toward lower unit cash costs that can underpin future revenue and net margin improvement."
What could really reshape Imperial Oil’s cash profile is how one cost and productivity lever changes the balance between strong production and future margins.
That cost and productivity lever is exactly what the full narrative for Imperial Oil unpacks in depth, revealing where Imperial Oil’s cash engine could be accelerating or quietly stalling next.
Seeking Alternatives Before Everyone Else?
Fresh ideas move first. By the time momentum headlines hit, early entries are already flying. Scan these under the radar for now opportunities while it matters and get in early.
- Target reliable income by tracking companies in the 3 dividend fortresses that aim to keep payouts coming even when volatility picks up.
- Spot potential breakout opportunities among 9 resilient stocks with low risk scores that pair steadier risk profiles with room for sentiment to shift fast.
- Back future-facing infrastructure by reviewing 43 power grid technology and infrastructure stocks positioned around the long term build out of smarter, more resilient electricity networks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com