


Fed officials talking about higher for longer rates, CPI running at 3.7% and consumers still spending with thinner savings all point to one thing: cash is no longer just a parking bay, it is a live decision. Investors who ignore how short-duration bond and money-market ETFs react to this mix risk sleepwalking past a key opportunity. This piece walks through three stocks from the screener that appear well positioned under these conditions.
The three ETFs covered below are just a sample, and the full screen highlights 8 more US short-duration bond and money-market funds with similarly detailed stories that are not covered here.
To size up this opportunity set properly, head straight to the US Short-Duration Bond & Money-Market ETFs screener to filter, analyze, and identify the ideas that best fit your own watchlist.
EVERTEC (EVTC)
EVERTEC plugs into this short-duration and money-market theme as the plumbing behind card payments, settlements, and record-keeping that banks and intermediaries lean on when they package and move cash-like assets for clients.
EVERTEC runs card processing, merchant acquiring, and business process services across Latin America, Puerto Rico, and the Caribbean, tying closely into how banks distribute cash-like and short-term products. Revenue is led by Latin America Payments and Solutions at about US$441 million, followed by Business Solutions at roughly US$238 million, Merchant Acquiring at about US$196 million, and Payment Services in Puerto Rico and the Caribbean at around US$231 million, with intersegment eliminations of roughly US$110 million. The stock is valued by the market at about US$1.9b.
EVERTEC matters for this ETF-focused list because it connects the day-to-day flow of payments and cash movements to the infrastructure that short-duration and money-market products rely on when rates stay higher for longer.
"Ongoing Latin America expansion through acquisitions such as Sinqia, Dimensa, Tecnobank and BBChain, combined with large processing contracts including Transbank in Chile and Clip in Mexico, is expected to shift more of EVERTEC’s revenue mix toward higher growth markets and support earnings over the next several years."
What happens to EVERTEC’s appeal from here depends heavily on how one unseen pressure shapes future margins and cash generation.
That pressure point is exactly what the full narrative for EVERTEC unpacks, revealing how EVERTEC’s Latin America push could accelerate or strain the story from here.

Jack Henry & Associates (JKHY)
Jack Henry & Associates is one of the behind-the-scenes operators that helps banks run the plumbing for deposits, payments, and digital channels, which in turn can shape how short-duration bond and money-market products reach retail and business clients.
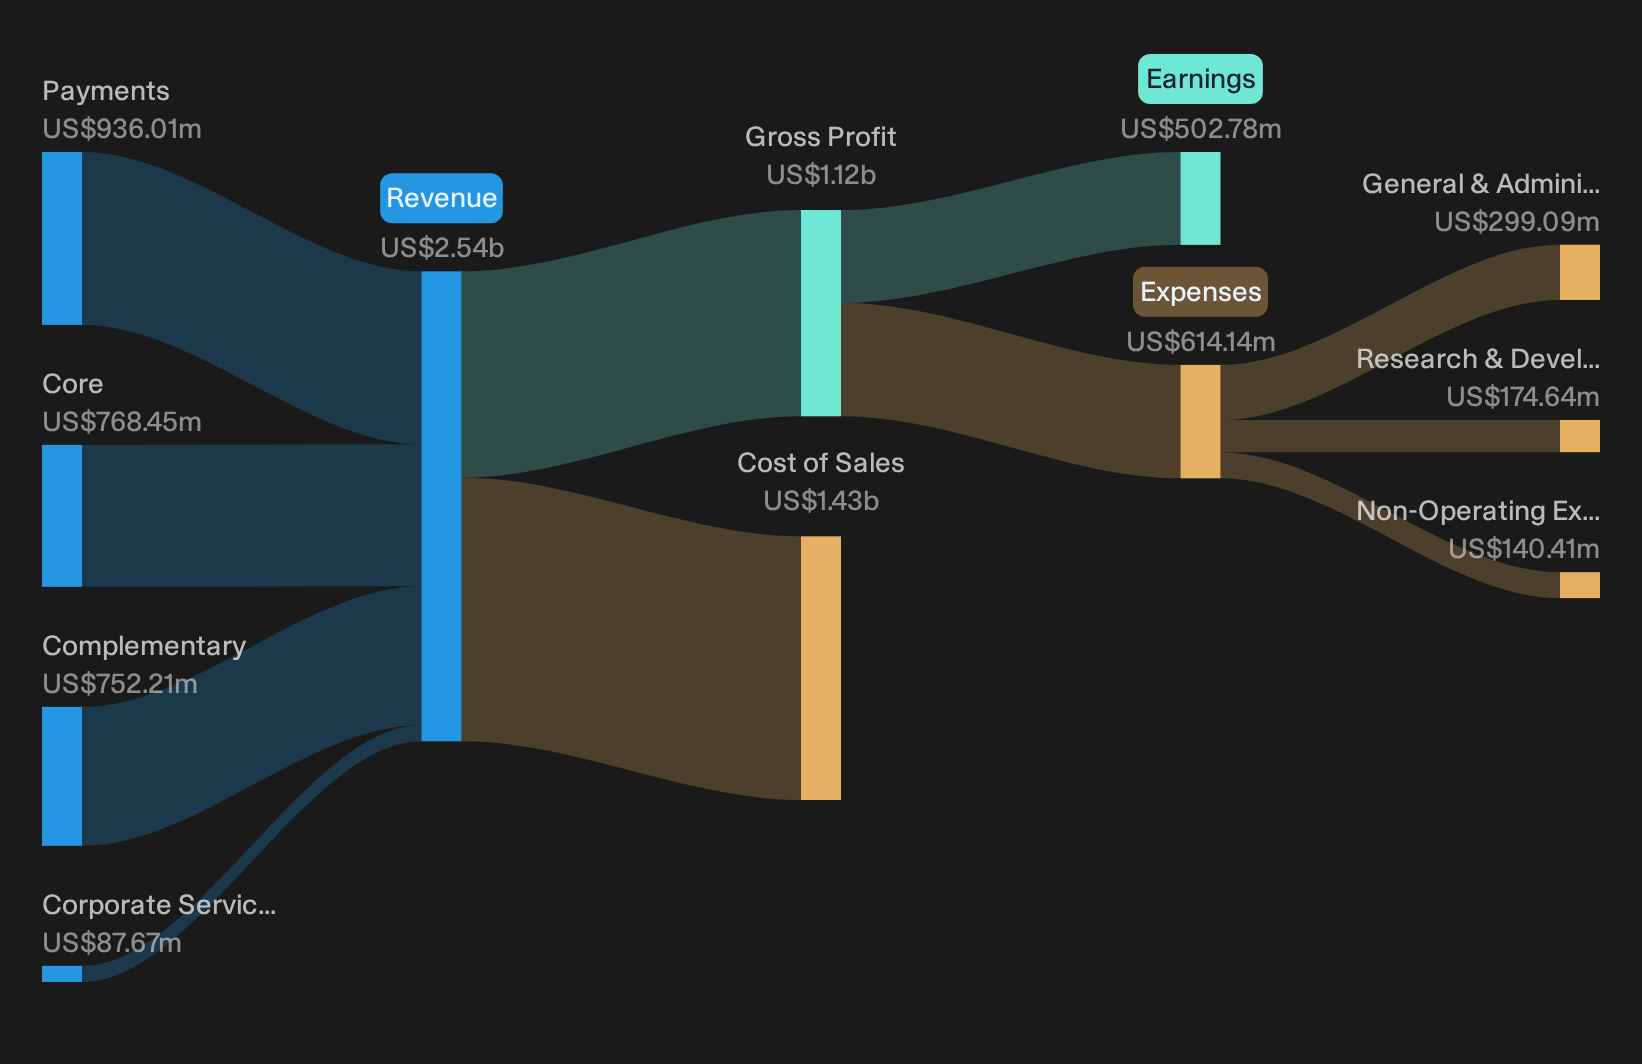
Jack Henry & Associates runs core processing and payment technology for US banks and credit unions, tying directly into how institutions handle deposits, cash movement, and liquidity. Payments brings in about US$936 million, Core about US$768 million, Complementary roughly US$752 million, and Corporate Services about US$88 million, with the business valued at around US$11.3b.
"The August call presented it as one of 15 competitive core wins in the quarter, one of 14 over $1 billion for the year, the anchor of a 58-win fiscal year that broke a two-decade record. The language around the win shifted from excited restraint to matter-of-fact enumeration, which may say more about execution confidence than any single superlative would."
What really tests Jack Henry & Associates from here is how one unresolved cost and pricing equation shapes the margin story investors now expect.
That margin puzzle is exactly what the full narrative for Jack Henry & Associates unpacks, showing where pricing power, bank tech budgets, and competitive pressure could be accelerating under the surface.
NCR Atleos (NATL)
NCR Atleos links directly into the short-duration and money-market theme by running the ATMs and self-directed banking rails that help customers move cash between deposit products, funds and other near-cash options.
NCR Atleos focuses on self-directed banking and ATM networks, with Self-Service Banking generating about US$2.96b of revenue, Network around US$1.26b, T&T roughly US$165 million and Other about US$26 million. This gives the company a market value near US$3.4b.
NCR Atleos is trying to tilt its business toward more recurring, service-led cash access while the broader macro debate tilts toward higher for longer policy. This puts every interest-sensitive model under a brighter light.
"Although NCR Atleos highlights strong momentum in ATM as a service and recurring self service banking revenue, the ongoing decline of roughly 4% in cash withdrawal transactions and weaker prepaid payroll card usage signal that transaction driven revenue in the Network segment could keep softening."
What happens to NCR Atleos’ appeal from here may hinge on how one unseen pressure shapes future margins and cash generation.
That pressure point is where the full narrative for NCR Atleos steps in, tracing how NCR Atleos could turn softening transactions into a reset for recurring cash access economics.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Slower money gets caught chasing momentum after prices are already flying. Scan under the radar for now, while it matters, and get in early.
- Explore potential breakout trends in cash rich, under-covered businesses by scanning the 19 high quality undiscovered gems that may still be flying below most investors’ radars.
- Review income ideas while yields remain elevated by running through the 4 dividend fortresses that aims to spotlight sturdier payers before prices change.
- Focus on structural tailwinds in next wave automation by working through the curated 95 robotics and automation stocks that highlights how factories, logistics and hardware are evolving.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com