


San Diego, California-based QUALCOMM Incorporated (QCOM) operates as a multinational semiconductor and telecommunications equipment company. With a market cap of $176 billion, the company develops and delivers digital wireless communications products and services based on CDMA digital technology.
Shares of this semiconductor and equipment giant have underperformed the broader market over the past year. QCOM has declined 10.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.3%. In 2026, QCOM stock is down 5.2%, compared to the SPX’s 10.2% rise on a YTD basis.
Narrowing the focus, QCOM’s underperformance is also apparent compared to the State Street SPDR S&P Semiconductor ETF (XSD). The exchange-traded fund has gained about 25% over the past year. Moreover, the ETF’s 36.9% gains on a YTD basis outshine QCOM’s single-digit losses over the same time frame.
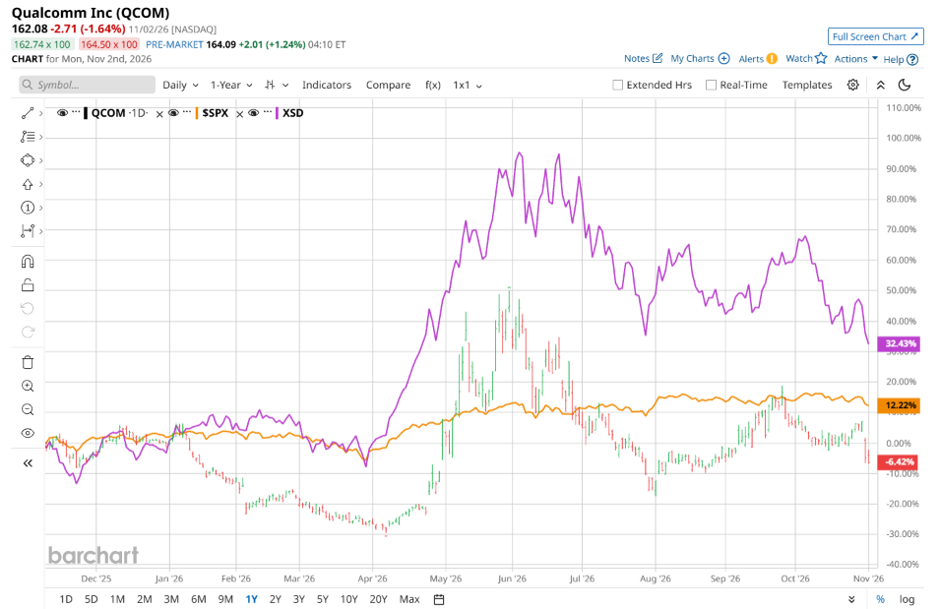
QCOM shares have underperformed due to mounting industry headwinds, including sluggish consumer demand in the core smartphone market and shifting premium chip mixes. Profitability is further squeezed by rising input costs for wafers, memory, packaging, and testing, alongside a sharper-than-expected loss of revenue as Apple Inc. (AAPL) accelerates its transition toward in-house modems.
For the current fiscal year, ending in September, analysts expect QCOM’s EPS to fall 23.4% to $7.71 on a diluted basis. The company’s earnings surprise history is mixed. It beat or matched the consensus estimate in three of the last four quarters while missing the forecast on another occasion.
Among the 34 analysts covering QCOM stock, the consensus is a “Moderate Buy.” That’s based on 10 “Strong Buy” ratings, two “Moderate Buys,” 18 “Holds,” one “Moderate Sell,” and three “Strong Sells.”
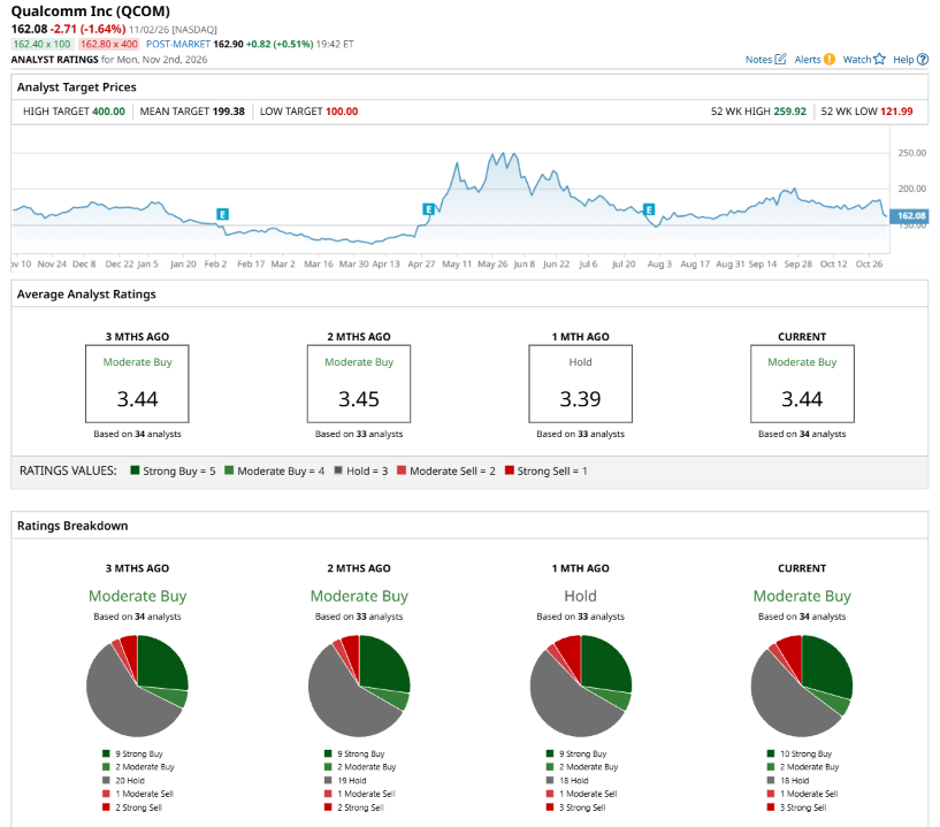
This configuration is more bullish than a month ago, with a “Hold” rating overall, consisting nine analysts suggesting a “Strong Buy.”
On Oct. 25, Bernstein analyst Stacy Rasgon maintained a “Hold” rating on QCOM and set a price target of $165, implying a potential upside of 1.8% from current levels.
The mean price target of $199.38 represents a 23% premium to QCOM’s current price levels. The Street-high price target of $400 suggests an ambitious upside potential of 146.8%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.