


Prologis (PLD) has moved back into the spotlight after completing a US$71.8 million at-the-market equity sale and filing for a much larger US$5 billion follow-on offering of common shares.
Prologis shares trade at US$129.65, with recent capital raising and the Joliet joint venture helping the 7-day share price return of 2.64% stand in contrast to a 90-day share price decline of 6.76%, while the 1-year total shareholder return of 7.65% indicates momentum that has been building over a longer period.
Scan how Prologis compares to other logistics and real estate players raising fresh equity by reviewing our curated list of solid balance sheet and fundamentals (24 results)
Fresh equity in play and a multi year Joliet project on the table put timing front and center for Prologis investors. Is it worth stepping in now, or is it better to wait for a potentially cleaner entry point once the valuation work is complete?
Most Popular Narrative: 15% Undervalued
Against a last close of $129.65, the most followed narrative pegs Prologis around $152.85 per share. This frames the fresh equity moves and Joliet build out as part of a longer term cash flow story rather than a short term trading blip.
The main thing that has to go right is that Prologis continues to convert its integrated platform in development, data centers, energy, and fund management into profitable projects and capital recycling while managing risks from equity issuance and large acquisitions.
The current valuation and narrative imply that Prologis shares do not fully reflect the long-term cash flow potential from embedded rent uplifts, logistics and data center development pipelines, and European expansion.
See why 111 investors see Prologis as 15% undervalued.
Result: Fair Value of $152.85 (UNDERVALUED)
Still, the Prologis story can wobble if fresh equity raises dilute earnings per share faster than cash flows build, or if the large SEGRO deal underdelivers relative to current expectations.
Find out about the key risks to this Prologis narrative.
Another View: Prologis On Earnings Versus Peers
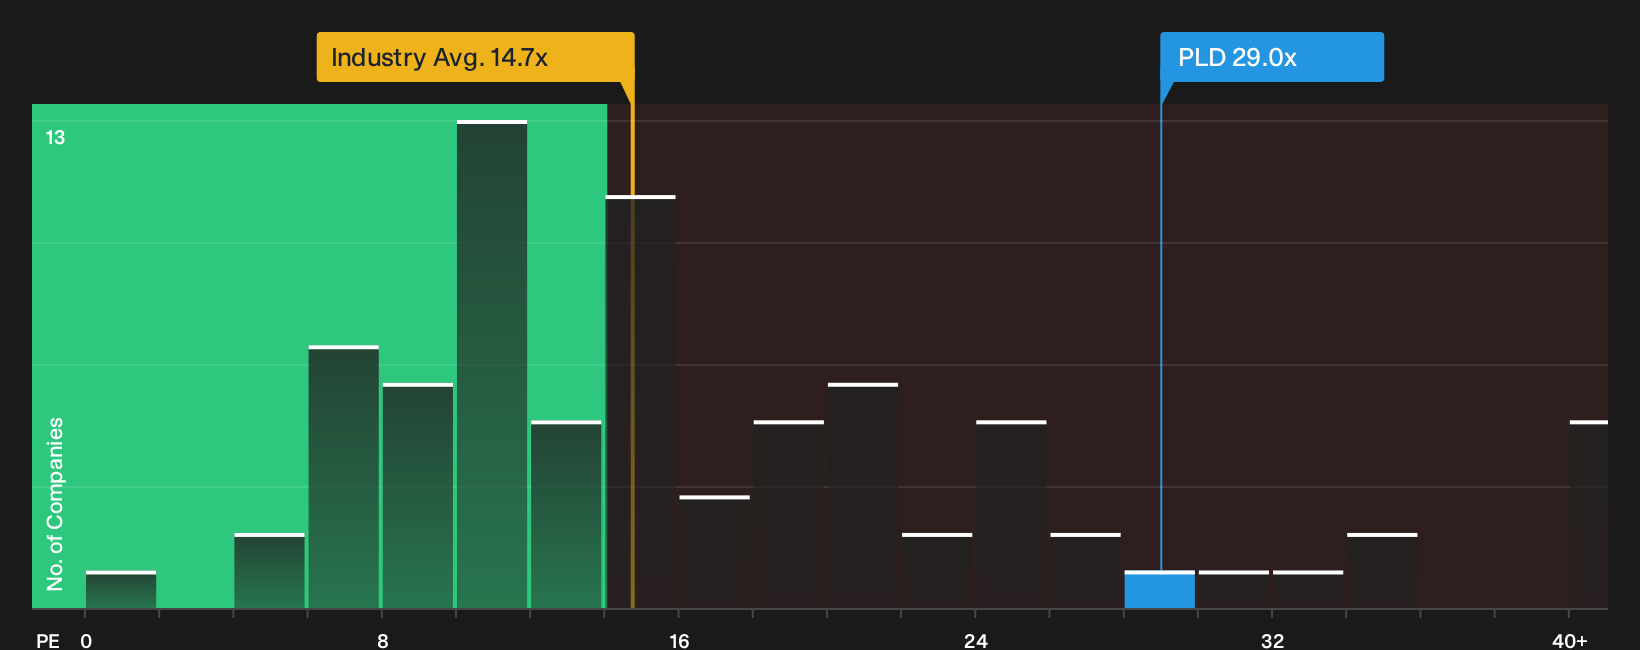
On simple earnings terms, Prologis trades at about 29x P/E. That is higher than both the peer group at 25x and the wider Global Industrial REITs average at 14.7x, even though the fair ratio for Prologis is estimated at 32.6x. Does that premium feel comfortable given the equity issuance and SEGRO risk in play?
Our valuation breakdown sets out how that gap between the current P/E, peers, and the fair ratio could close over time, and what that might mean for upside or downside scenarios for existing and new shareholders See what the numbers say about this price — find out in our valuation breakdown.
Here is how Prologis screens visually against the broader industry on this metric
Next Steps
Sentiment on Prologis is clearly mixed, with fresh equity, a premium P/E and that Joliet project all pulling in different directions. If you want to move fast but still keep a cool head, weigh the upside and downside in our breakdown of 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Prologis?
Do not stop with Prologis. Use this moment to broaden your watchlist with other potential opportunities that fit your risk, income, and value goals.
- Target potential mispricings by scanning a curated set of 34 high quality undervalued stocks that pair resilient fundamentals with room for sentiment to catch up.
- Strengthen your income stream by reviewing a hand picked group of 4 dividend fortresses built around higher yields and balance sheet support.
- Dial down portfolio stress by focusing on 29 resilient stocks with low risk scores that combine sturdier financials with lower risk scores before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com