


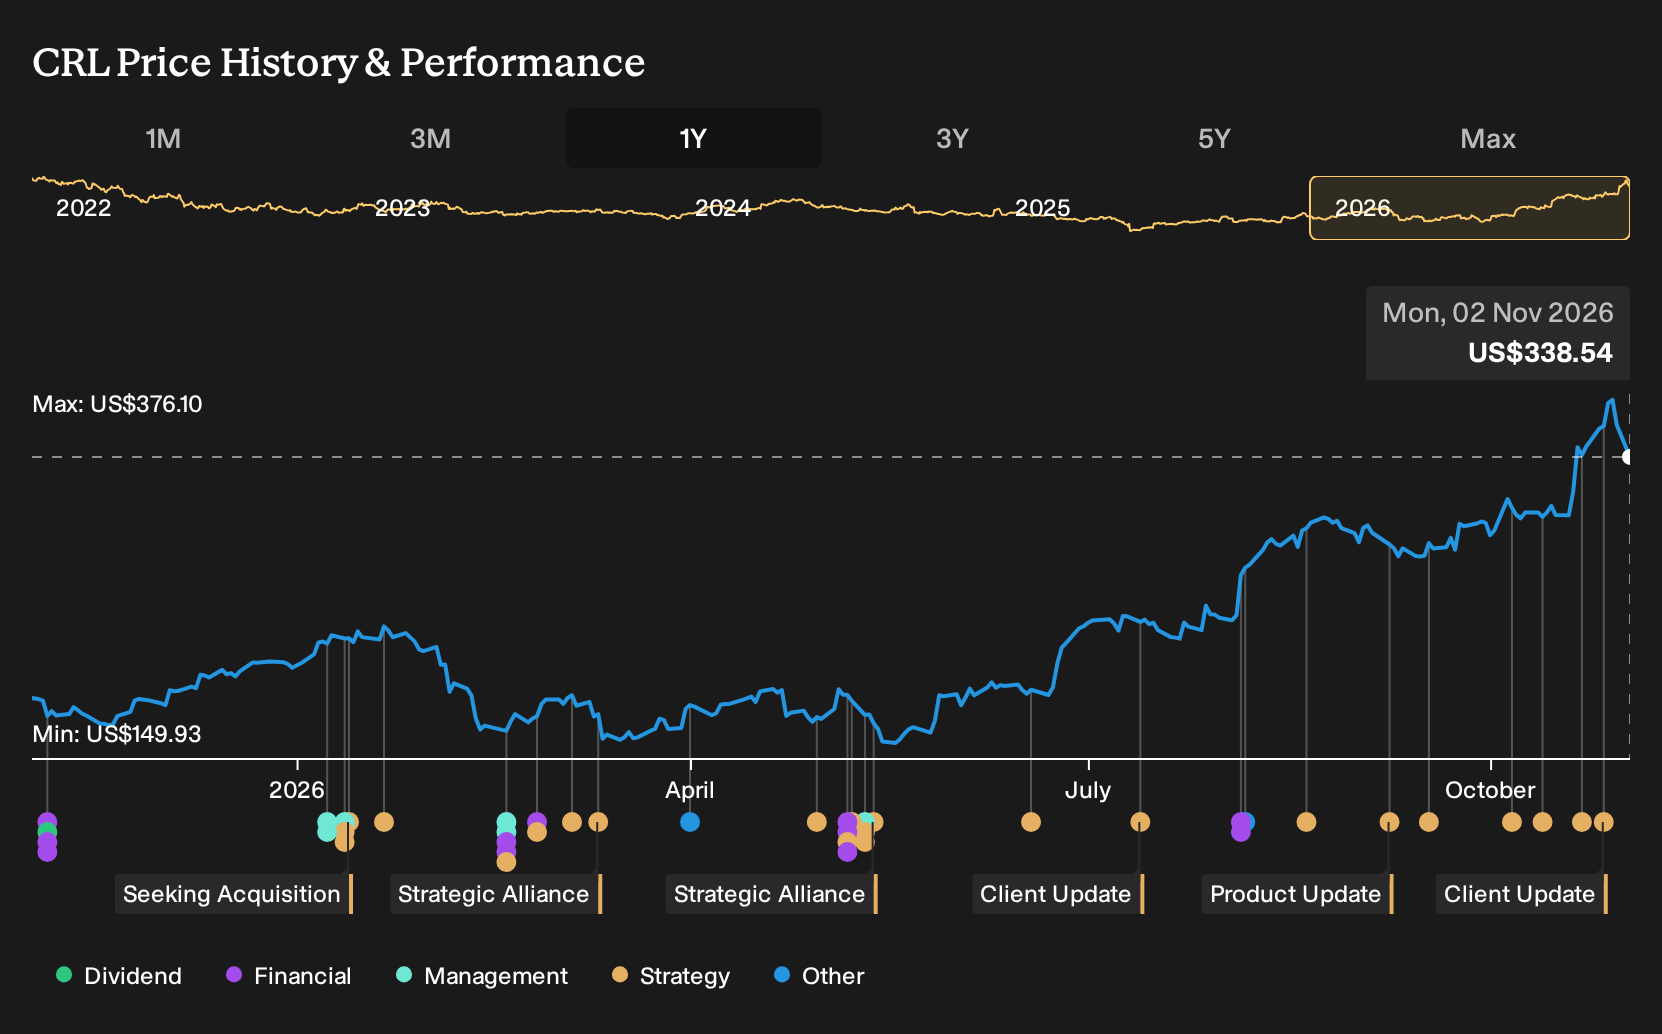
If you only glanced at Charles River Laboratories International’s recent headlines about falling net margin and mixed segment trends, you might not expect a standout result for long term holders. For Charles River Laboratories International shareholders, the return over the past year was 89.3%, including dividends. If you had been weighing the bullish and bearish analyst cases back on 2 November 2025, how might you have judged that risk against what the business actually delivered?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Charles River Laboratories International is not the only name tied to this theme. Zero in on 33 healthcare AI stocks and compare how each one is priced.
The Two Charles River Narratives Investors Faced
The shares cost US$180 at the start of the period, so anyone looking at Charles River Laboratories International then had to decide which story felt more reasonable.
On the bullish side, the Fair Value sat at US$200. This was framed around faster adoption of New Approach Methods and digital tools, plus an assumption that revenue would grow 3.7% a year and profit margins would move from a loss to 14.8% by 2028.
The bearish view put Fair Value at US$79.1. This was built on revenue falling 11.7% annually, animal testing demand being eroded by alternatives, and Charles River Laboratories International only reaching a 6.3% margin and a 23.8x P/E on 2028 earnings.
What The Results Changed For Charles River Laboratories International
Charles River Laboratories International spent the period refocusing around its Pathway to Purpose plan, divesting CDMO and Cell Solutions units and leaning into AI enabled services and cell and gene therapy partnerships. That supported the bullish story about New Approach Methods and digital tools. The measured results pulled the other way. Q2 2026 revenue of US$1,004.1 million and a small net loss challenged any quick profitability recovery. Overall, the evidence cut both ways.
The key assumption here was margin repair, not just top line direction. For any other contract research stock, it may be useful to track whether net margin and absolute profit move toward the thesis on each quarterly update before relying heavily on long term narratives about technology or regulation.
What Charles River’s 89% Run Already Assumes
Charles River Laboratories International now trades at US$339, after a return of 89.3% over the past year. The selected Narrative’s Fair Value sits below that level, so it treats today’s quote as already reflecting strong delivery.
That view hinges on digital modernization, New Approach Methodologies and bioanalysis mix shift working as planned. Anyone paying today’s price is effectively judging whether those margin and earnings goals can absorb the specific operational risks the selected Narrative flags.
"The numbers imply the share price already reflects strong execution on cost savings, mix shift toward higher margin segments, and sustained biotech funding support, which leaves limited room for disappointment if demand, pricing, or margin expansion fall short of current expectations."
One Narrative disagrees with today's price. → See where this Narrative says Charles River Laboratories International should trade
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 45% below our estimate - grows payment volumes for merchants by routing pay-ins and payouts across local solutions.
- Company 2 - 26% below our estimate - wins electrical and communications work tied directly to large hyperscale data center buildouts.
- Company 3 - 30% below our estimate - links AI workloads and subscription software to the same expanding cloud infrastructure footprint.
That is three of the list. See the full list of 34 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com