


Key earnings takeaways and why Erie Indemnity is in focus
Erie Indemnity (ERIE) moved into the spotlight after third quarter 2026 results, which showed modest top line and earnings per share shifts, along with strong underwriting gains and a larger policyholder surplus.
Erie Indemnity’s latest earnings update has arrived alongside a sharp shift in sentiment, with the share price climbing 23.9% over the past month and 12.0% across 90 days, even though the year to date share price return is slightly down and the 1 year total shareholder return has slipped 1.7%. This points to near term momentum building after a softer stretch as investors reassess the insurer’s underwriting strength and upcoming leadership transition.
Scan how Erie Indemnity’s earnings driven move compares with other financially solid insurers by reviewing our curated list of solid balance sheet and fundamentals (24 results) in the same space.
Erie Indemnity appears to be a solid operation, with steady underwriting and fee income, and the share price has recently moved up sharply. The key question now is whether that quality is already fully reflected in the current valuation.
Price-to-Earnings of 24.9x: Is it justified for Erie Indemnity?
Erie Indemnity finished the latest session at $273.93, and at that price the shares trade on a P/E of 24.9x, which screens as expensive when set against both the insurance peer group and the broader US Insurance industry averages quoted in the data.
The P/E ratio compares what you pay per share with the earnings that Erie Indemnity generates for each share. For an insurer built around fee based and underwriting services, this measure gives a quick sense of how much future profitability the market is already factoring into the current quote.
At 24.9x earnings, investors are paying materially more for each dollar of profit than for the typical US Insurance stock on 11.5x, and meaningfully above the peer average of 13.1x. That gap suggests the market is assigning a premium to Erie Indemnity’s earnings profile and 22.6% return on equity. The estimated fair P/E of 15.4x indicates a level the valuation could move toward if sentiment cools.
Explore the SWS fair ratio for Erie Indemnity.
Result: Price-to-Earnings of 24.9x (OVERVALUED)
Still, Erie Indemnity faces pressure if underwriting trends soften or if the leadership transition reduces investor confidence in the current premium valuation.
Find out about the key risks to this Erie Indemnity narrative.
Another view on Erie Indemnity’s valuation
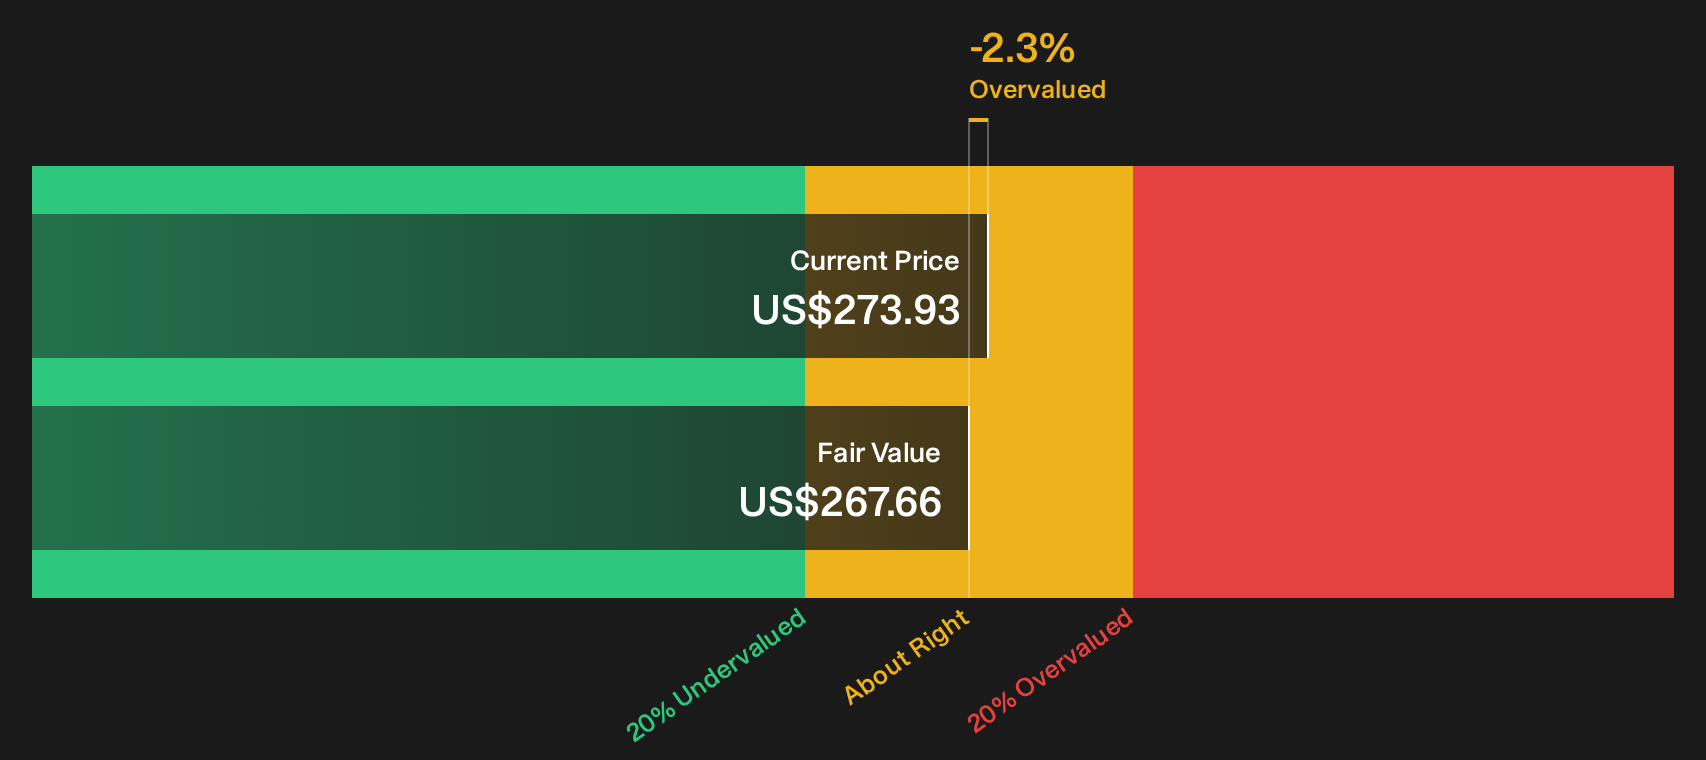
The P/E workup presents Erie Indemnity as clearly expensive. The SWS DCF model points in the same direction, with the current $273.93 price sitting above an estimated future cash flow value of $267.66, which indicates only a slim margin of safety for anyone paying that price today.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Erie Indemnity for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading this, you might feel Erie Indemnity carries both a rich price tag and some genuine bright spots. Consider reviewing the underlying data for yourself, evaluating the key metrics in detail, and weighing the 2 key rewards
Looking for more investment ideas beyond Erie Indemnity?
If Erie Indemnity helped clarify what you want in a holding, do not stop here. The wider market holds plenty of candidates worth a closer look.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) to see which businesses match your risk profile.
- Hunt for quality at a potential discount by reviewing the 19 high quality undiscovered gems that combine solid financials with lower market attention.
- Focus on capital preservation and stability by filtering through 29 resilient stocks with low risk scores so that short term noise does not pull prices away from your checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com