


Altria Group (MO) is one of the leading tobacco and nicotine companies in the United States, headquartered in Richmond, Virginia, with a business legacy spanning more than two centuries. Its diverse portfolio comprises several well-established businesses, including Philip Morris USA, the manufacturer of the iconic Marlboro cigarette brand, and John Middleton, known for its Black & Mild cigars. The company also owns popular smokeless tobacco brands such as Copenhagen and Skoal, alongside on!, its portfolio of oral nicotine pouches.
Through these businesses, Altria has built a significant presence in traditional tobacco markets while gradually broadening its portfolio to cater to changing preferences among adult nicotine consumers. As it looks to reduce its reliance on conventional cigarettes and accelerate its transition toward smoke-free alternatives, the company is investing in emerging product categories, including NJOY e-vapor products and on! nicotine pouches.
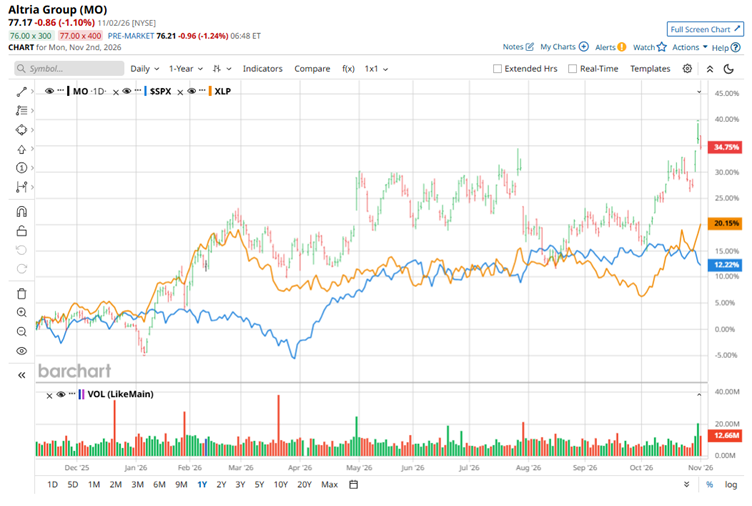
With a market capitalization of approximately $128.36 billion, Altria has proved that it still has plenty of firepower on Wall Street, even as adult smoking rates in the U.S. have steadily declined over the past several decades. The tobacco giant has delivered an impressive run, with its shares climbing 36.9% over the past 12 months and advancing another 33.8% so far in 2026. The outperformance becomes even more striking when stacked against the broader market
Over the same periods, the broader S&P 500 Index ($SPX) has gained just 10.3% and 10.2%, respectively. Altria's rally has also comfortably outpaced its consumer staples peers. The State Street Consumer Staples Select Sector SPDR ETF (XLP), a widely followed gauge of the sector, has advanced 19.1% over the past year and 17% in 2026.
While declining smoking rates have created a challenging backdrop for traditional tobacco companies, Altria has found ways to keep investors firmly interested. Its ability to generate substantial cash flows, reward shareholders with generous dividends, and maintain pricing power has helped the stock stand out on Wall Street. The company is also sticking to its tried-and-tested earnings playbook of price increases, cost discipline, and share repurchases, while stepping up investments in smoke-free alternatives such as NJOY e-cigarettes and on! nicotine pouches.
This two-pronged approach allows Altria to continue extracting value from its established tobacco business while building new revenue streams to reduce its long-term reliance on conventional cigarettes and cigars. Recently, Altria delivered a welcome surprise for investors with its fiscal 2026 third-quarter earnings report on Oct. 29, comfortably beating expectations and lifting its full-year outlook despite continued volume headwinds in its traditional cigarette business.
The results underscored the company's ability to protect its financial performance amid a challenging tobacco market, while continuing to advance its broader portfolio strategy. Investors wasted little time rewarding the performance, driving Altria shares up 5.2% on the day of the announcement.
For the fiscal year ending in December, Wall Street expects Altria to deliver diluted EPS of $5.70, representing a 5.2% increase from the previous year. However, the company's earnings track record has been somewhat inconsistent. Over the past four quarters, Altria has surpassed analysts' expectations twice but fallen short on two other occasions.
Overall, Wall Street remains cautiously optimistic, assigning MO stock a consensus “Moderate Buy” rating. Of the 15 analysts covering MO, five recommend a “Strong Buy,” eight rate it “Hold,” while one each recommends “Moderate Sell” and “Strong Sell.” This current setup has remained unchanged over the past three months.
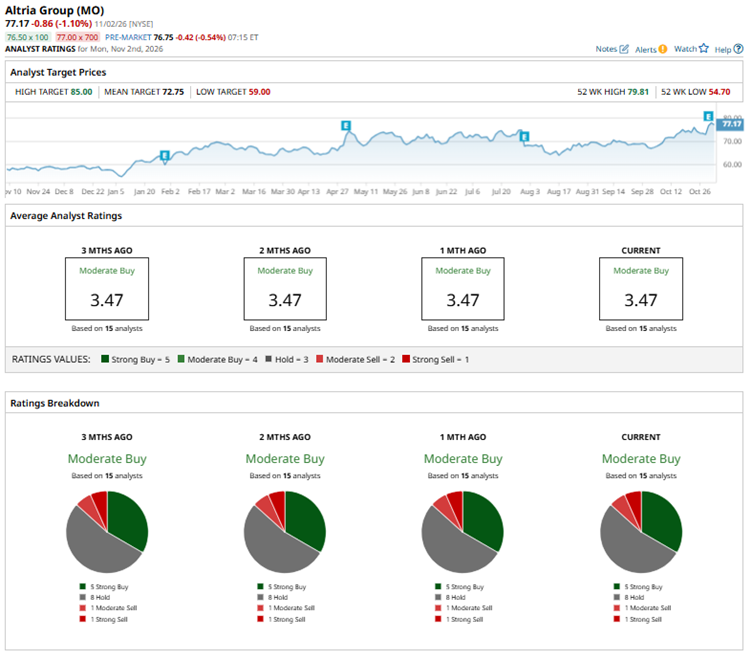
Recently, UBS has sweetened its outlook on Altria, raising its price target to $83 from $79 while sticking with its “Buy” recommendation. The revised target reflects the firm's confidence following Altria's fiscal 2026 third-quarter results, which delivered encouraging revenue growth. Although the stock is already trading above its average price target of $72.75, the Street-high target of $85 suggests a potential upside of 10.1%, leaving room for further gains.
On the date of publication, Anushka Mukherji did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.