


Elevance Health has delivered a strong 34.7% share price gain over the past year, helped by steady earnings and renewed optimism around its core health insurance and services operations. For anyone looking at the stock today, the key issue is whether that earnings profile is enough to justify the current price tag.
- The 34.7% return over the last 12 months puts real pressure on the question of whether Elevance Health's earnings now fully reflect that rerating or still leave room for further upside or downside.
- Recent updates around cost control, Medicaid and ACA margins and the performance of Carelon businesses can reshape how durable investors expect Elevance Health's earnings power to be.
- The analysts covering Elevance Health have run their own numbers. See what analysts think Elevance Health's shares could be worth.
The stock's next move may depend on whether Elevance Health's current earnings justify a valuation in line with, or away from, the Fair Ratio benchmark.
To test whether Elevance Health's earnings story and recent rerating feel compelling or stretched, compare it with a wider set of 34 high quality undervalued stocks.
Is Elevance Health Still Cheap on Earnings?
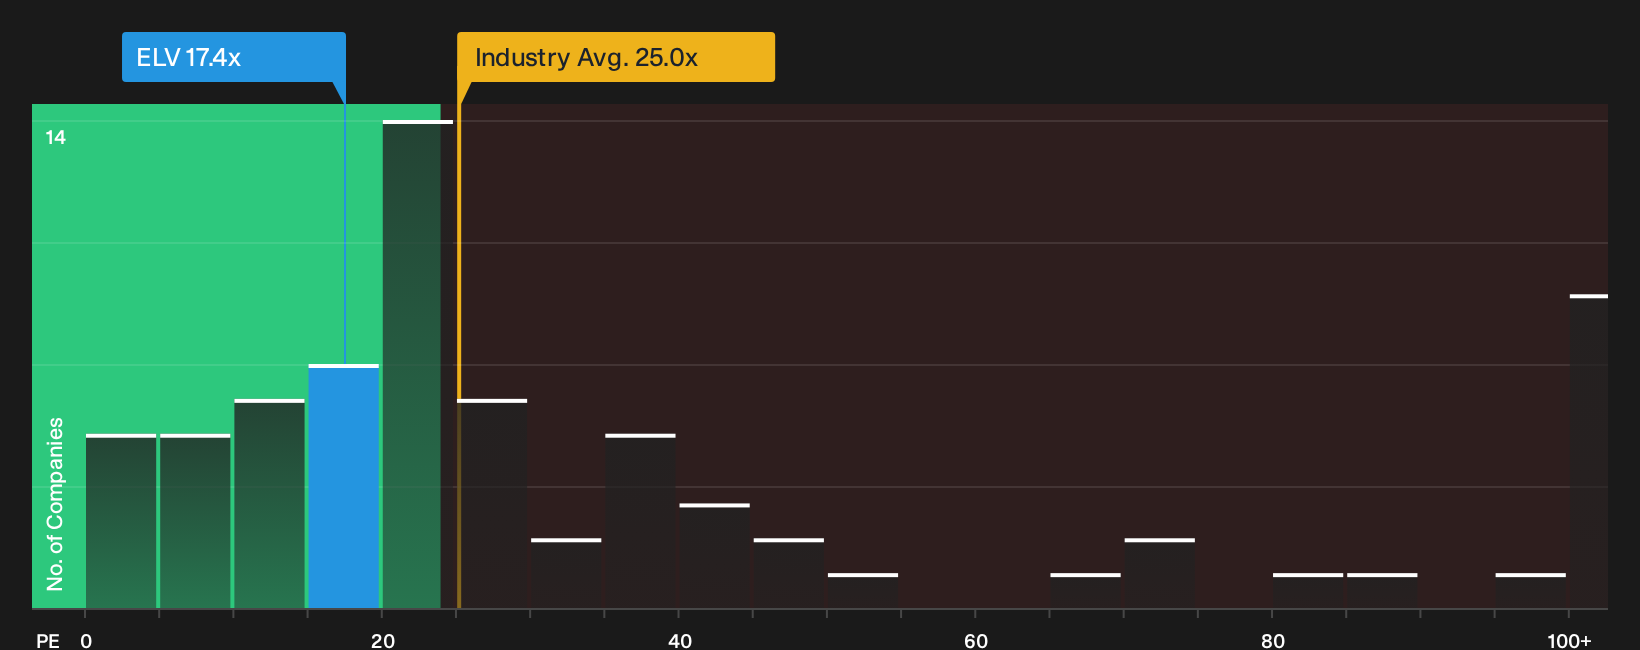
The P/E ratio suits Elevance Health because earnings remain a key anchor for how investors look at large, established insurers. On this measure, the stock trades at about 17.4x earnings, which is below the wider healthcare sector on roughly 25.0x and also under the peer group average near 30.0x. That gap suggests investors are not paying the same per dollar of profit as they are for many comparable healthcare stocks.
Because the current P/E sits below the level suggested by the Fair Ratio model, which blends Elevance Health's business profile, risk mix and sector context, the shares screen as undervalued on this yardstick. Because the company recently beat Q3 2026 earnings expectations and lifted guidance, yet the P/E still trails sector and peer benchmarks, the market appears to be pricing that stronger outlook cautiously rather than aggressively. Explore the numbers behind Elevance Health's P/E valuation.
The Elevance Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Elevance Health pick up where the P/E discussion leaves off and explain what kind of future growth, profitability and earnings path would need to occur for the stock to be worth materially more or materially less than it is today on the market. Rather than relying on a single multiple or model line, each narrative sets out the assumptions behind its own view of fair value so you can track those inputs against Elevance Health's reported results over time.
Community views on Elevance Health split between those who see meaningful upside left and those who think most of the story is already in the price.
Bull case: 13% undervalued
"Expansion of Carelon’s complex and behavioral care programs, including initiatives that have shown around 10% cost savings and reduced inpatient admissions…"
Discover why this Narrative puts Elevance Health at 13% undervalued.
Bear case: roughly fairly valued
"Bearish analysts expect Elevance Health to struggle to offset elevated system costs in government-backed plans as Medicaid margins remain under pressure…"
Explore why this Narrative puts Elevance Health at roughly fairly valued.
One more Elevance Health check investors should weigh beside the valuation work
Price and earnings only tell part of the story, because Simply Wall St checks have also flagged specific areas of concern that thoughtful investors may want to review before deciding what to do next. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com