


- Nextpower reported second quarter 2026 sales of US$1,109.28 million and net income of US$165.45 million, with both basic and diluted EPS from continuing operations above the prior year, and raised its fiscal 2027 revenue and GAAP earnings guidance.
- The business paired these results with a completed US$162.4 million share repurchase program, which reduced the share count while management projected higher full year revenue and GAAP net income.
- We will now look at how Nextpower's raised 2027 guidance reshapes the existing investment narrative around backlog quality and earnings mix.
Scan how Nextpower's latest earnings beat and raised 2027 outlook compare with other high quality operators by reviewing the hand picked 34 high quality undervalued stocks that share solid fundamentals and potential mispricing.
Nextpower Investment Narrative Recap
To own Nextpower, you generally need to believe the record backlog, storage and inverter buildout, and software tools can keep turning into higher quality earnings despite choppy project timing. The latest quarter showed higher sales, higher net income, and EPS from continuing operations, which supports that basic thesis without radically changing it.
The key near term swing factor is still execution on that contracted work while managing input costs and mix so margins do not erode further. Interconnection delays and any repeat of past guidance misses remain the biggest operational risk, and the new outlook narrows some concern but does not remove it.
The clearest update tied to this story is the raised fiscal 2027 guidance. Management now projects revenue of US$4.2b to US$4.45b, GAAP net income of US$559 million to US$598 million, and GAAP diluted EPS of US$3.62 to US$3.87. Those figures sit above the prior ranges.
For you, that means the most important catalyst is still whether Nextpower can deliver that higher bar while converting its multibillion dollar backlog on time and at acceptable margins. Analysts remain generally constructive, but any stumble against this upgraded guidance could quickly refocus attention on forecasting and execution risk.
What The Long Term Consensus Implies For Nextpower
Analysts are effectively telling you that for Nextpower, the story now stretches well beyond the upgraded 2027 targets into the back half of the decade. The consensus view links the current backlog and product mix shift to a much larger business by the end of that period, with both top line and earnings power stepping up if execution holds.
Nextpower's narrative projects US$6.3b revenue and US$967.9 million earnings by 2029, which ties back to an assumed 18.1% yearly revenue growth rate and an earnings increase of about US$355 million from the current US$612.6 million base.
Those assumptions carry some tension. Forecast earnings of US$967.9 million by 2029 come with an expected margin drift from 16.0% today to 15.3% in 3 years, so the consensus view leans on scale rather than richer profitability to do most of the work. For you, the question is whether an 18.1% annual revenue climb with slightly lower margins feels realistic given project timing, interconnection issues and the mix of trackers, storage and software in the backlog.
The earnings path is also far from settled. Forecasts for 2029 range from US$821.2 million to US$1.1b, which leaves a wide gap between the most cautious and most optimistic views on how Nextpower converts its order book and new product lines into profit. That spread effectively measures how much disagreement there is around execution on storage, inverters and higher margin software tools, and how much slippage investors are willing to tolerate along the way.
On these analyst numbers, the implied valuation framework is clear. To line up with the consensus narrative, you would be assuming roughly US$6.3b of sales and US$967.9 million of earnings in 2029 and a P/E of 28.1x applied to those projected profits, compared with about 19.6x on earnings today and a current US Electrical industry multiple cited at 31.2x. The required P/E uplift sits below that sector level, so the bigger swing factor becomes whether the growth and backlog story actually produces the forecast earnings rather than whether the multiple itself is extreme.
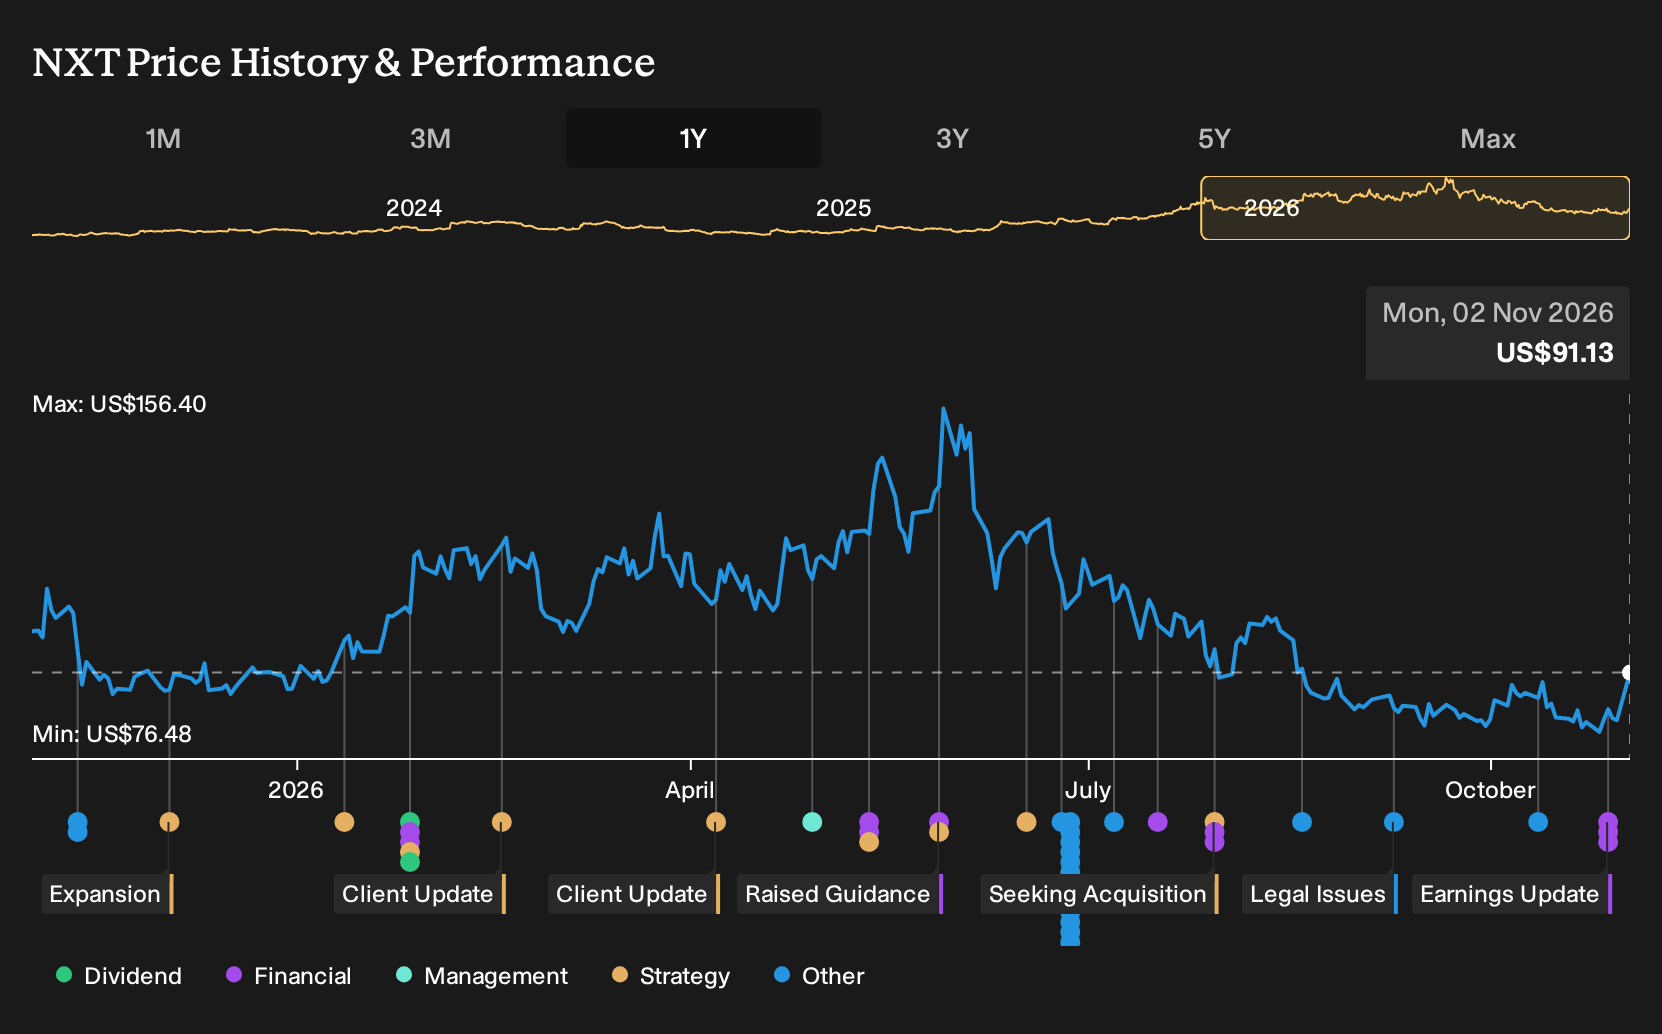
Price targets reflect that same push and pull. With the stock at US$79.33 as of the latest report and a consensus target of US$129.39, analysts are building in meaningful upside if the 2029 profile plays out, while individual expectations stretch from US$70.00 to US$170.00. That gap, combined with the roughly 32% share price decline over six months after softer results and guidance issues, shows how quickly sentiment can adjust when reported EBITDA and revenue prints do not match the narrative on backlog quality and margin resilience.
Uncover why Nextpower's fair value indicates a 42% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on margins rather than backlog. The most optimistic analysts were already penciling in profit margin expansion to 17.0% and earnings of about US$1.1b by 2029, versus roughly US$612.6 million today. That is a far brighter path than consensus, and it predates this latest Nextpower earnings beat and guidance hike. You may want to compare how that optimistic view could shift once these fresh numbers are fully baked into the models.
Explore 4 other Nextpower fair value estimates, including one that suggests as much as 87% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nextpower research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nextpower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nextpower's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nextpower?
If you want to cross check Nextpower against other potential opportunities, a quick sweep through the Simply Wall St Screener can help you spot businesses with different risk and return profiles that might better match your goals.
- For investors who care most about balance sheet strength and fundamental resilience, review the list of solid balance sheet and fundamentals (24 results) to see which companies might handle stress better.
- If capital preservation and steadier profiles matter more to you than chasing headline growth, scan the 29 resilient stocks with low risk scores for businesses that score well on risk metrics.
- When you want to cast a wider net for lesser known opportunities with robust fundamentals, check out the 19 high quality undiscovered gems and see which smaller stocks analysts may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com