


PayPal Holdings has seen its stock climb back to US$58.78 after a long stretch of mixed sentiment, which puts a fresh spotlight on whether that price is properly supported by the business’s earnings power. With the turnaround story gaining attention, the key issue is how much of that earnings profile is already reflected in the current valuation.
- Over the past 5 years the share price has fallen about 74%, so any reassessment of earnings quality and durability carries extra weight for investors who stayed through the drawdown or are considering re-entry.
- Recent earnings outperformance and higher profit guidance suggest management sees room for stronger margins and cash generation, which can reshape what investors are willing to pay for each dollar of PayPal’s earnings.
- The analysts covering PayPal Holdings have run their own numbers. See what analysts think PayPal Holdings's shares could be worth.
The issue now is whether PayPal’s current share price is justified by the earnings it is generating today and what those profits imply for the years ahead.
If you are reassessing PayPal against other opportunities that also focus on valuation and fundamentals, a focused stock screen such as 34 high quality undervalued stocks may be useful.
Does PayPal Holdings Look Undervalued on Earnings?
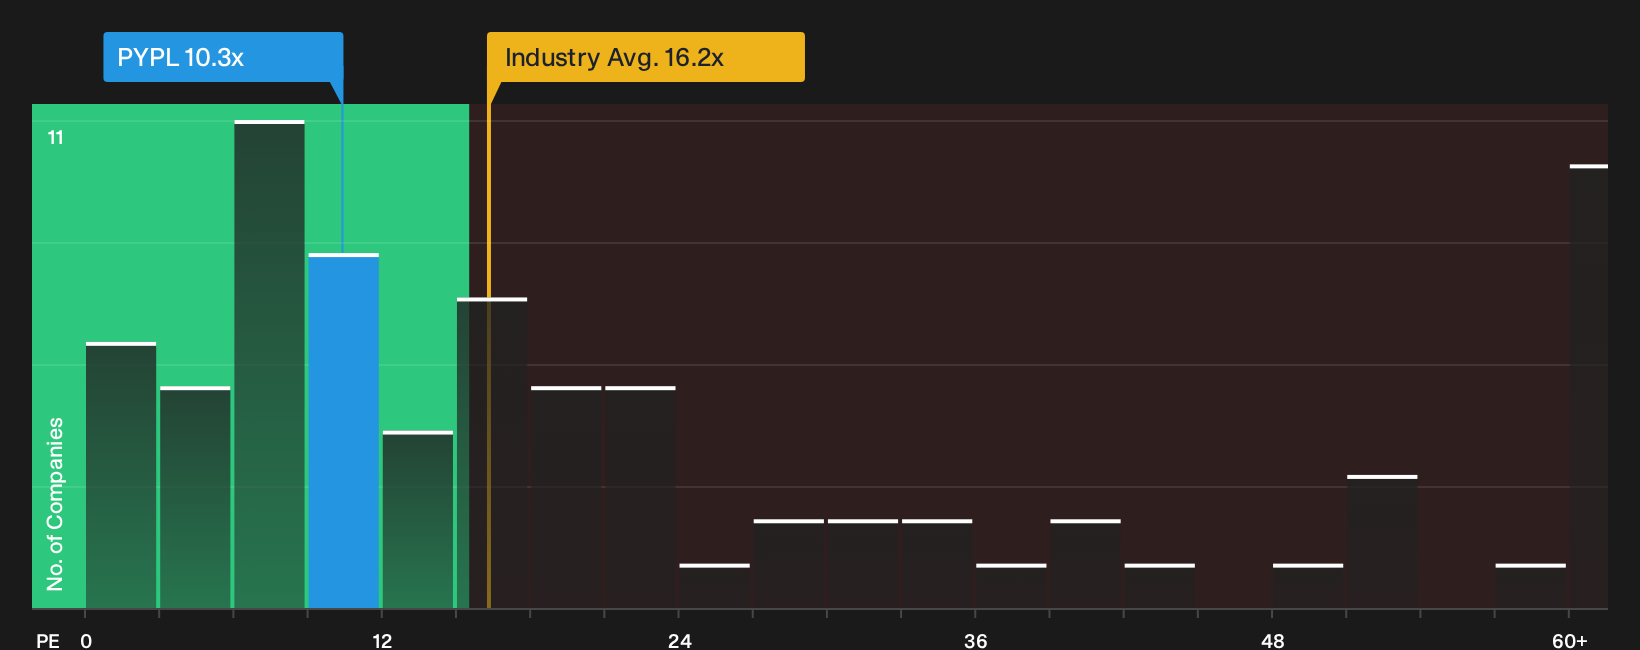
P/E is a good fit for PayPal Holdings because the business is already profitable and analysts focus heavily on earnings guidance. At a P/E of 10.3x, the stock trades well below the diversified financial industry average of 16.2x and far under the broader peer group near 54.3x. That gap suggests the market is putting a relatively low earnings multiple on PayPal compared with other listed payment and financial platforms.
The Fair Ratio model, which blends PayPal’s growth outlook, margin profile, size and risk, points to a higher multiple than where the shares change hands today, so the current P/E screens as undervalued on this framework. Management recently raised its 2026 earnings guidance, and the discount on the multiple persists despite higher profit expectations being in the price. Explore the numbers behind PayPal Holdings's P/E valuation.
The PayPal Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the PayPal Holdings valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than it trades for today on the market. Each one treats PayPal Holdings' fair value as a specific thesis about the business that you can revisit over time, not just a one-off snapshot, and they sit on Simply Wall St's Community page.
Community views on PayPal split between those who see extra upside in an asset light model and those who think most of the story is already in the price.
Bull case: 28% undervalued
"With the regulatory door slammed shut, PayPal’s path for 2026 is clear: do what it does best, but faster…"
Discover why this Narrative puts PayPal Holdings at 28% undervalued.
Bear case: roughly fairly valued
"The current valuation, which this narrative views as fair and bullish, implies the market already prices in continued execution on cost savings…"
Explore why this Narrative puts PayPal Holdings at roughly fairly valued.
One more angle on PayPal Holdings that could change how you see the stock
There is another lens worth checking before you move on, which is how professional analysts currently map out PayPal Holdings a few years from now and how that picture lines up with today's pricing. Explore where analysts expect PayPal Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com