


- PHIL Inc. and Harrow announced the launch of HarrowRx, an EMR-integrated prescribing and access platform that routes Harrow’s ophthalmic portfolio, including VEVYE, through a single digital entry point with embedded patient support and affordability programs.
- The HarrowRx rollout makes Harrow a more embedded part of eye care workflow. It may shift prescription capture, support costs, and patient access from fragmented specialty pharmacy channels into one coordinated pharmacy and services hub.
- The next area of focus will be how HarrowRx’s EMR integration and single-destination prescribing model may reshape Harrow’s broader investment narrative.
Scan beyond HarrowRx and consider other healthcare platforms that are reshaping patient access with our curated list of 33 healthcare AI stocks.
Harrow Investment Narrative Recap
To own Harrow, you need to believe the eyecare portfolio can scale through better access, not just new drug launches. HarrowRx fits that idea because it tries to make VEVYE and other branded therapies easier to prescribe and fill from inside the EMR. The key short term focus stays on converting prescriptions efficiently into paid, repeat usage.
The biggest operational risk still looks like dependence on a handful of flagship brands and the execution load around ambitious revenue goals. HarrowRx may ease friction for clinics, yet it also concentrates operational complexity in one pharmacy and services hub. If that hub underperforms, the access story can quickly work in reverse.
The HarrowRx launch is the announcement that most directly ties into Harrow’s near term catalysts. Management wants higher quality revenue from branded drugs by tightening the link between a doctor’s decision and actual product delivery. This access infrastructure could matter for areas like TRIESENCE, BYQLOVI, and the biosimilars portfolio as they mature.
For you as a shareholder, the question becomes whether Harrow can run this EMR integrated channel cleanly while facing pricing pressure, prior authorization hurdles, and potential competition to VEVYE, IHEEZO, and TRIESENCE. HarrowRx does not remove those risks. It just gives the business a clearer operational test of its execution and support model.
Harrow's analyst narrative points to revenues of US$784.8 million and earnings of US$246.0 million by 2029. This outlook is based on a forecast 42.9% yearly increase in revenue and an earnings swing of US$261.0 million from an earnings loss of US$15.0 million today.
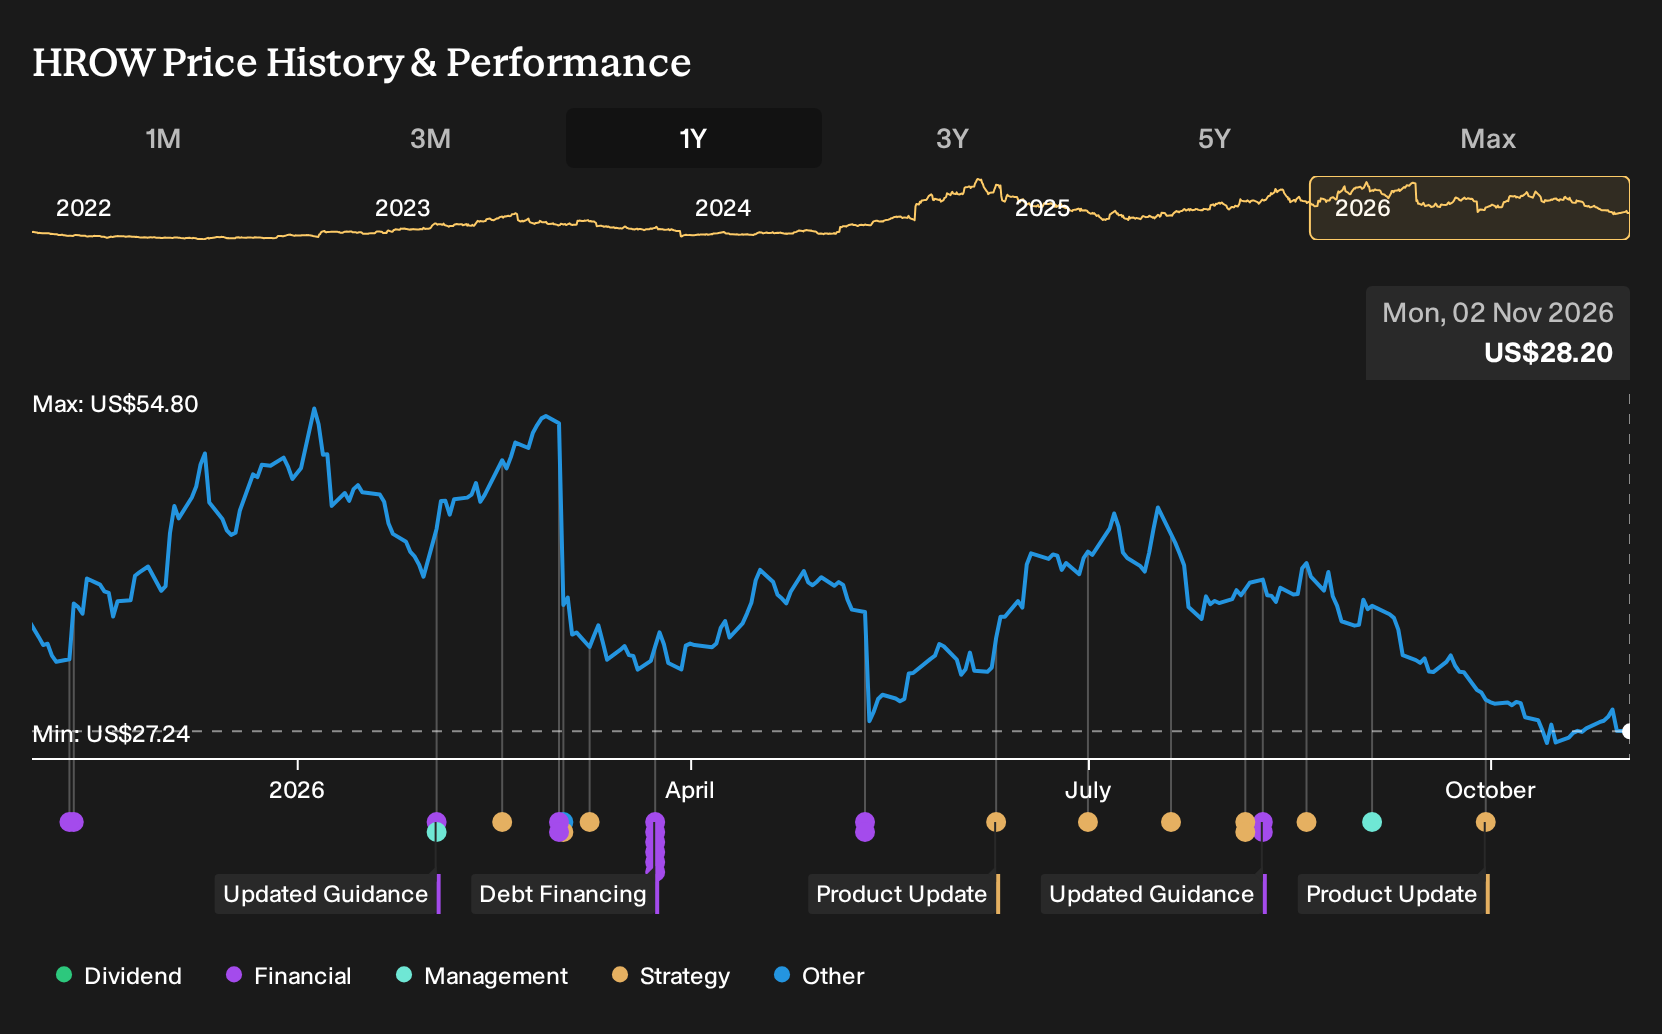
Uncover why Harrow's fair value indicates a 142% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts on Harrow lean hard into operating leverage as the key catalyst, expecting revenues of about US$946.8 million and earnings near US$306.2 million by 2029, versus the consensus US$784.8 million and US$246.0 million. Those views were set before HarrowRx, so forecasts may shift as opinions evolve.
Explore 2 other Harrow fair value estimates, including one that suggests as much as 1078% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Harrow research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Harrow. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harrow's overall financial health at a glance.
Looking for more investment ideas beyond Harrow?
Once you understand where Harrow fits in your portfolio, it can help to scan for other stocks with clear strengths that match your risk profile and income goals.
- If you want potentially steadier compounding with less drama, focus on resilience and filter for 29 resilient stocks with low risk scores that pass a disciplined risk screen.
- If balance sheet strength matters most to you, start with companies that carry less financial strain and work through the list of solid balance sheet and fundamentals (24 results) to find candidates worth a closer look.
- If you are hunting for mispriced potential, broaden the search to 19 high quality undiscovered gems that pair strong fundamentals with limited current attention from the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com