


With a market cap of $54.5 billion, Realty Income Corporation (O) is a leading REIT specializing in the acquisition and management of diversified commercial properties under long-term net lease agreements. With a global portfolio of over 15,600 properties across the U.S., U.K., and Europe, the company delivers consistent monthly dividends and has increased its dividend for more than 30 consecutive years.
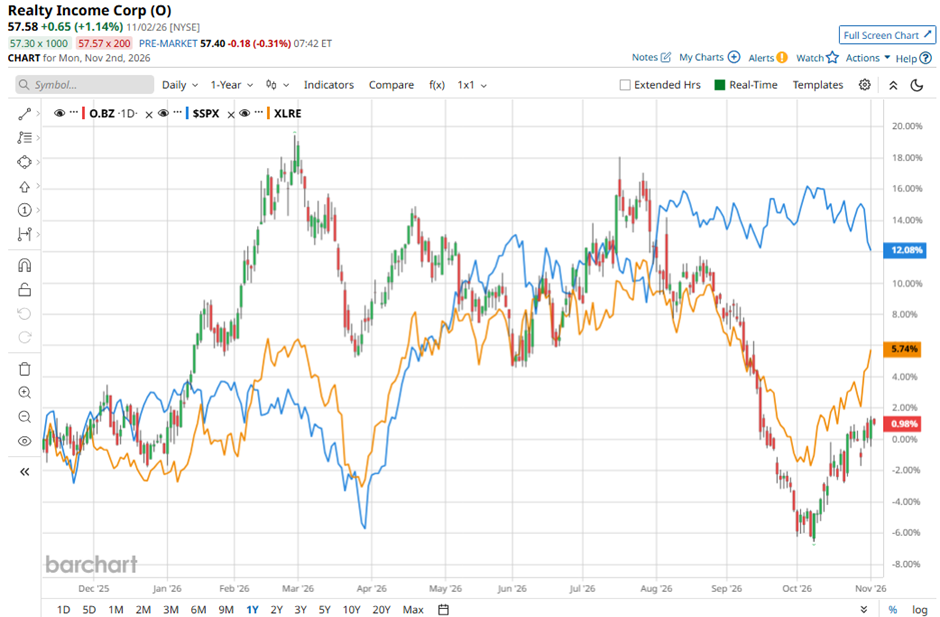
Shares of the San Diego, California-based company have lagged behind the broader market over the past 52 weeks. O stock has fallen marginally over this time frame, while the broader S&P 500 Index ($SPX) has increased 10.3%. Moreover, shares of the company are up 2.2% on a YTD basis, compared to SPX’s 10.2% rise.
Zooming in further, shares of the REIT have underperformed the State Street Real Estate Select Sector SPDR ETF’s (XLRE) 6.7% gain over the past 52 weeks and 8.2% YTD return.
Realty Income reported stronger-than-expected Q3 2026 results on Nov. 2, with adjusted FFO per share of $1.12 and revenue reached $1.62 billion. The company recorded nearly 7% year-over-year rental revenue growth to $1.48 billion, portfolio occupancy of 98.8%, and a 103.5% rent recapture rate on re-leased properties, with new annualized rent of $67.6 million.
Realty Income also raised its 2026 adjusted FFO guidance to $4.45 per share - $4.46 per share, above the consensus, reaffirmed 1.1% - 1.3% same-store rent growth, and $10 billion in investment volume expectations.
For the fiscal year ending in December 2026, analysts expect Realty Income’s AFFO per share to grow nearly 4% year-over-year to $4.45. The company’s earnings surprise history is mixed. It beat or met the consensus estimates in each of the last four quarters.
Among the 25 analysts covering the stock, the consensus rating is a “Moderate Buy.” That’s based on six “Strong Buy” ratings, one “Moderate Buy,” 17 “Holds,” and one “Strong Sell.”
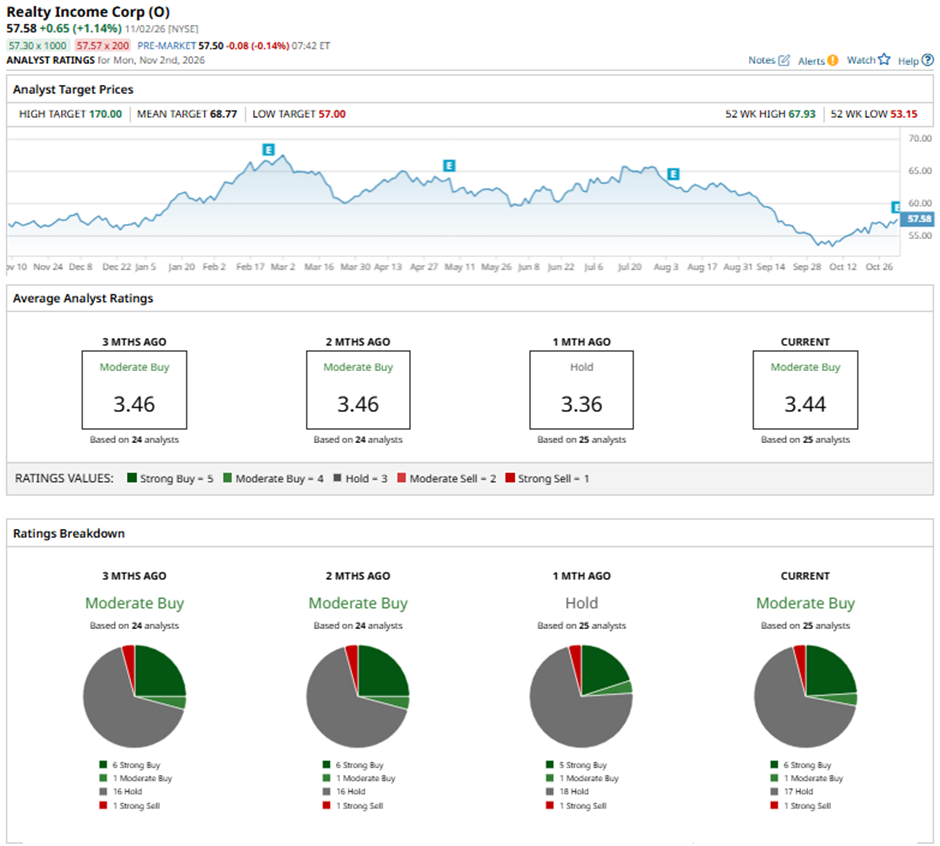
This configuration has remained unchanged over the past three months.
On Oct. 19, Wells Fargo cut its price target on Realty Income to $59, maintaining an “Equal Weight” rating.
The mean price target of $68.77 represents a 19.4% premium to Realty Income’s current price levels. The Street-high price target of $170 suggests a 195.2% potential upside.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.