


Why Regeneron’s latest quarter matters for investors
Regeneron Pharmaceuticals (REGN) just paired a revenue and earnings beat with fresh clinical and regulatory news, putting its key drugs DUPIXENT, EYLEA HD and LIBTAYO firmly in focus for shareholders.
Recent moves in Regeneron Pharmaceuticals reflect that this has been more than a one day reaction to earnings and trial updates. A 30 day share price return of 30.75% and a 1 year total shareholder return of 50.44% point to strong momentum that investors are linking to DUPIXENT, EYLEA HD, LIBTAYO, the Inmazeb supply extension with BARDA, the ongoing buyback and the newly affirmed dividend at a share price of $961.26.
Spot other healthcare opportunities showing similar momentum to Regeneron Pharmaceuticals by scanning our hand picked 33 healthcare AI stocks aligned with major clinical and regulatory catalysts.After a 30 day surge and a price near $961, Regeneron Pharmaceuticals forces a choice. Should investors lean into the move now, or wait and hope the valuation offers a cleaner entry later?
Most Popular Narrative: 11% Overvalued
On the most followed view, Regeneron Pharmaceuticals screens as overvalued, with a fair value estimate of $869.07 against a last close of $961.26. The recent share price surge now leans ahead of that narrative.
Current valuation implies the market is heavily discounting the durability of Dupixent, the conversion of the retinal business to EYLEA HD, and the potential from the late stage pipeline and expanded Sanofi collaboration. This is why this narrative views Regeneron Pharmaceuticals as undervalued and maintains a bullish stance on the stock.
See why 92 investors see Regeneron Pharmaceuticals as 11% overvalued.
Result: Fair Value of $869.07 (OVERVALUED)
Still, the bullish Regeneron Pharmaceuticals story can crack if EYLEA HD loses share to new retinal rivals or if litigation around Libtayo and fianlimab proves costly.
Find out about the key risks to this Regeneron Pharmaceuticals narrative.
Another View on Regeneron Pharmaceuticals’ Valuation
The analyst fair value narrative pegs Regeneron Pharmaceuticals at $869.07 and flags the stock as 11% overvalued against the $961.26 share price. A different lens tells a very different story. Our DCF model prices REGN at about $2,314 per share, which frames the current quote as far below its estimated future cash flow value and raises a simple question for investors: Which set of assumptions feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
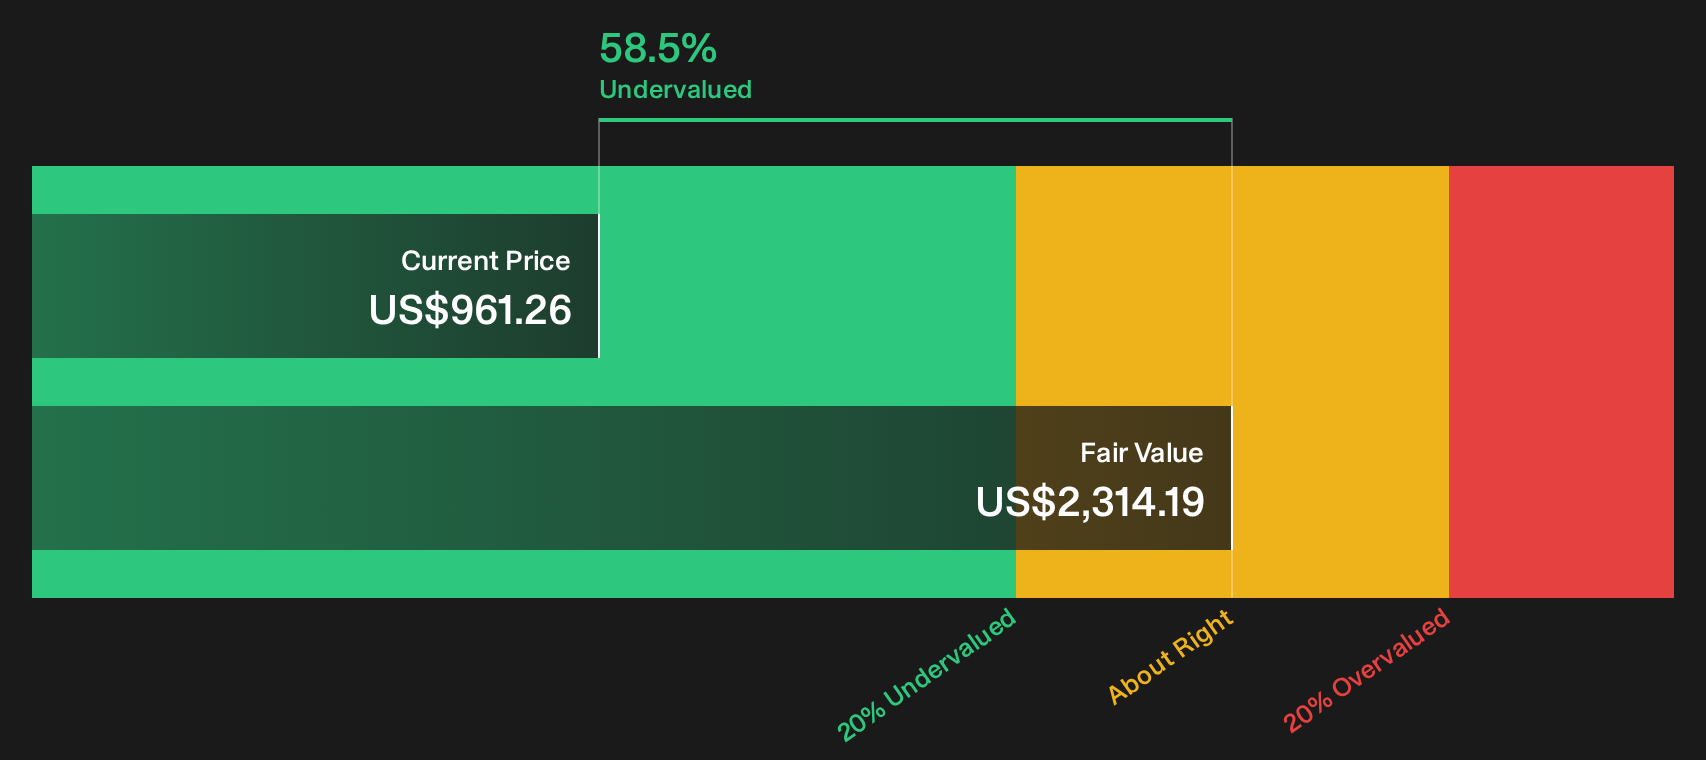
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Regeneron Pharmaceuticals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment this divided on Regeneron Pharmaceuticals, it pays to pressure test the numbers yourself and move before the consensus shifts again. To see what investors find attractive right now, review the 2 key rewards.
Ready for more ideas beyond Regeneron Pharmaceuticals?
Do not stop with one opportunity. Broader context across sectors and styles can sharpen your view on what really deserves a place in your portfolio.
- Target resilient total return by reviewing 4 dividend fortresses that prioritise income without ignoring balance sheet strength.
- Hunt for mispriced quality and scan the 19 high quality undiscovered gems that many investors have not analysed yet.
- Dial up defense in choppy markets and filter for a 29 resilient stocks with low risk scores that still leaves room for meaningful upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com