


Cenovus Energy has delivered a powerful run over the past several years, even with recent share price weakness. With the stock now around $42.95, the key question for investors is whether that level is adequately supported by the company’s earnings profile.
- Over the past 5 years, Cenovus Energy has returned about 200.9%, which puts a lot of past optimism and current expectations about its profit power under the microscope.
- The planned $5.7b acquisition of Athabasca Oil, expected to add roughly 45,000 barrels of oil equivalent per day and targeted annual synergies of about $85 million, can reshape how investors think about Cenovus Energy’s future margins and the timing of its cash generation.
- Your read on Cenovus Energy is one view; the desks covering it have another. See what analysts think Cenovus Energy's shares could be worth.
The issue now is whether Cenovus Energy’s current share price is justified by the earnings it is generating today and what those profits reasonably point to over time.
If you are weighing whether Cenovus Energy’s 84.1% one year gain and 5 year run of about 200.9% align with its earnings power, it can help to compare that question across 5 high quality undervalued stocks.
Does Cenovus Energy Look Undervalued on Earnings?
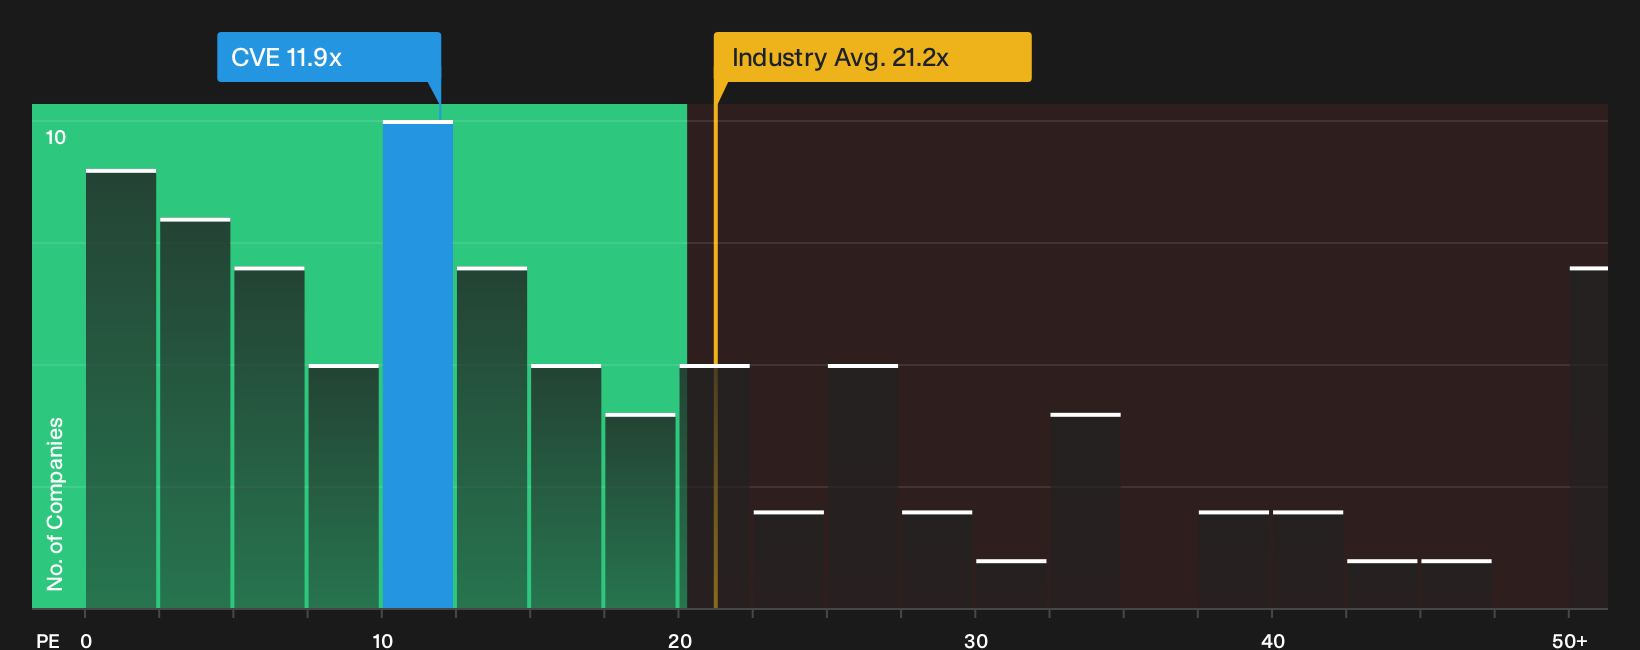
The P/E ratio is a useful lens for Cenovus Energy because earnings are a central focus for investors in large, established oil and gas producers. Cenovus trades on roughly 11.9x earnings, which is well below the Oil and Gas sector average of about 21.2x and also under the peer group level around 16.7x. That gap means the market is currently paying less for each dollar of Cenovus earnings than for many comparable producers.
Because the Athabasca Oil deal is front of mind after the October 2026 announcement, it matters that this lower P/E also sits beneath the multiple suggested by a more tailored fair ratio model that takes Cenovus Energy’s size, profitability profile and risk into account. Despite that acquisition raising expectations around future production and integration work, the current valuation still reflects a discount on this earnings yardstick. Explore the numbers behind Cenovus Energy's P/E valuation.
The Cenovus Energy Narrative: What Would Justify Today's Price?
Narratives on Cenovus Energy sit just after that P/E puzzle and spell out which earnings paths, margin levels and growth profiles would need to hold for the shares to look meaningfully higher or lower than today’s price. Where a single valuation ratio or model gives one headline figure, these scenarios describe the future that figure relies on so you can judge over time whether Cenovus Energy's progress is tracking that script or drifting away from it.
One of the top community narratives on Cenovus Energy: 18% undervalued
"The main thing that has to go right is that Cenovus successfully integrates recent oil sands acquisitions while delivering the planned ramp in thermal production…"
Discover why this Narrative puts Cenovus Energy at 18% undervalued.
Cenovus Energy’s valuation story leaves one key behaviour in the spotlight
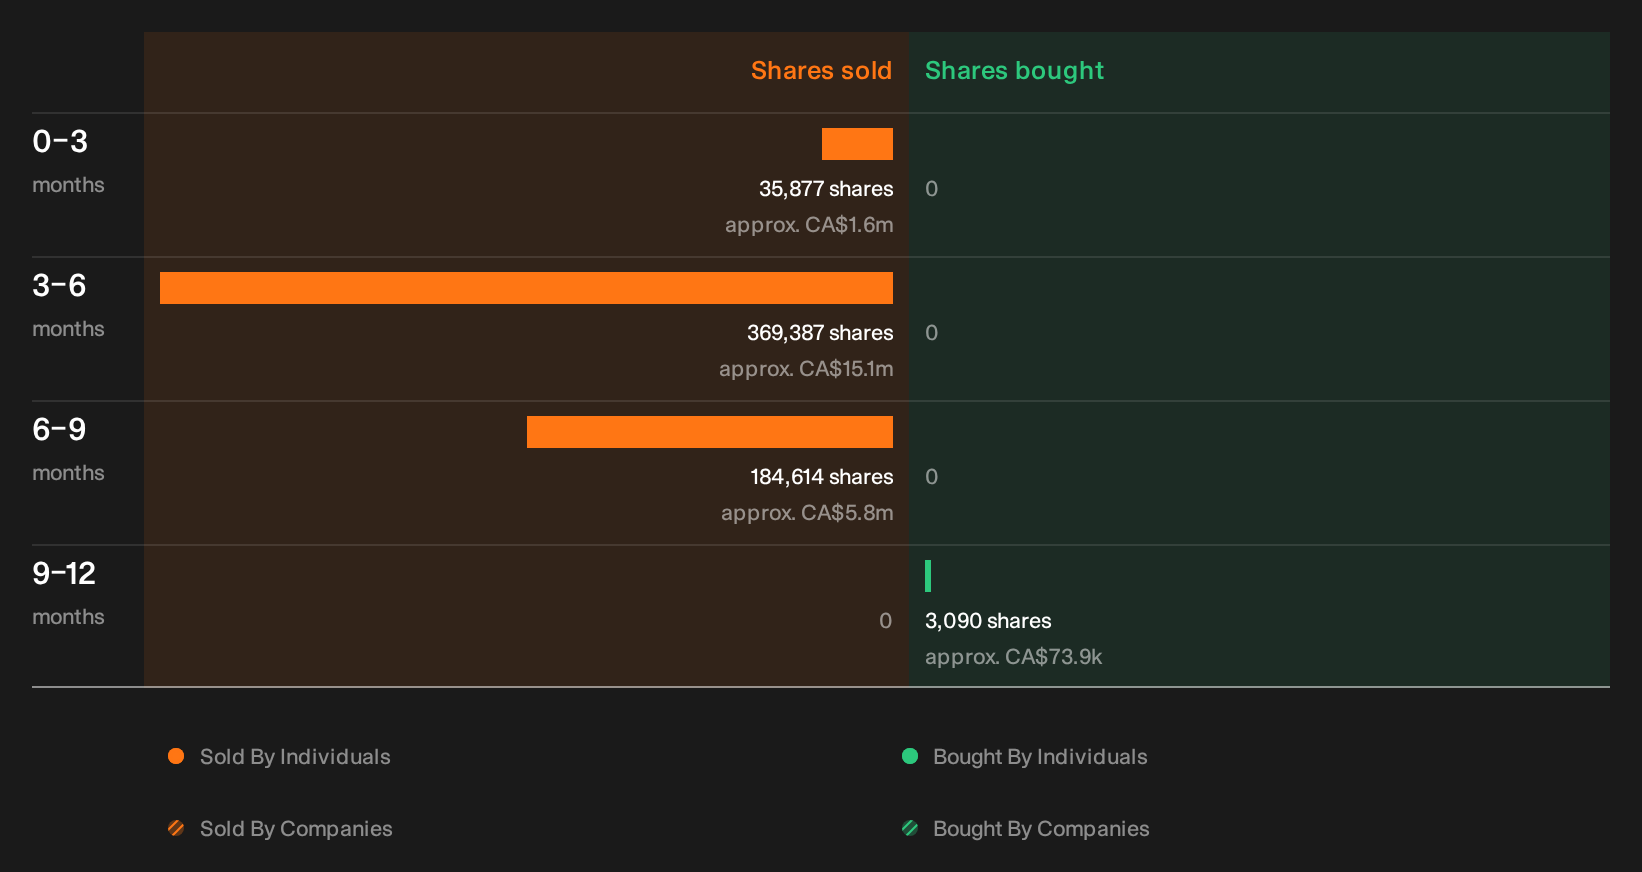
Price multiples tell one story about Cenovus Energy, but our checks also pick up recent insider transactions that raise a different set of questions about what executives and directors are doing with their own holdings. See the recent insider selling flagged for Cenovus Energy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com