


Dividend affirmation puts Wolverine World Wide in focus
Wolverine World Wide (WWW) drew fresh attention after its board affirmed a quarterly cash dividend of $0.10 per share, matching the prior payout and indicating continuity in shareholder cash returns.
The recent dividend decision follows a strong run in Wolverine World Wide's share price, with a 1-month share price return of 11.46% and a year-to-date share price gain of 17.52%. This comes even as the 1-year total shareholder return declined 1.98% and the 3-year total shareholder return remains very large at roughly 17x. This suggests momentum has picked up again as investors respond to Saucony's reported 31.1% revenue growth and the upgraded full-year outlook.
Scan beyond Wolverine World Wide and see which other footwear and apparel players are showing similar momentum and dividend support in our hand picked 34 high quality undervalued stocks.
Wolverine World Wide now appears to be a stronger footwear platform, with Saucony and Merrell driving more of the momentum and the dividend still in place. After this latest share price jump, are investors paying a fair price for that improvement, or are they stretching it?
Most Popular Narrative: 12% Undervalued
On the most followed narrative, Wolverine World Wide screens as undervalued, with a fair value estimate of $24.30 against a last close of $21.40. This puts fresh focus on whether Saucony and Merrell can continue to carry the heavier load in this footwear portfolio.
Portfolio optimization, supply chain improvements, and continued brand investment are strengthening market position, protecting margins, and supporting long-term earnings growth.
See why 14 investors see Wolverine World Wide as 12% undervalued.
Result: Fair Value of $24.30 (UNDERVALUED)
Still, the story can break if wholesale partners pull back faster than Wolverine World Wide grows direct channels, or if lagging legacy brands continue to absorb cash and attention.
Find out about the key risks to this Wolverine World Wide narrative.
Another View on Wolverine World Wide's Valuation
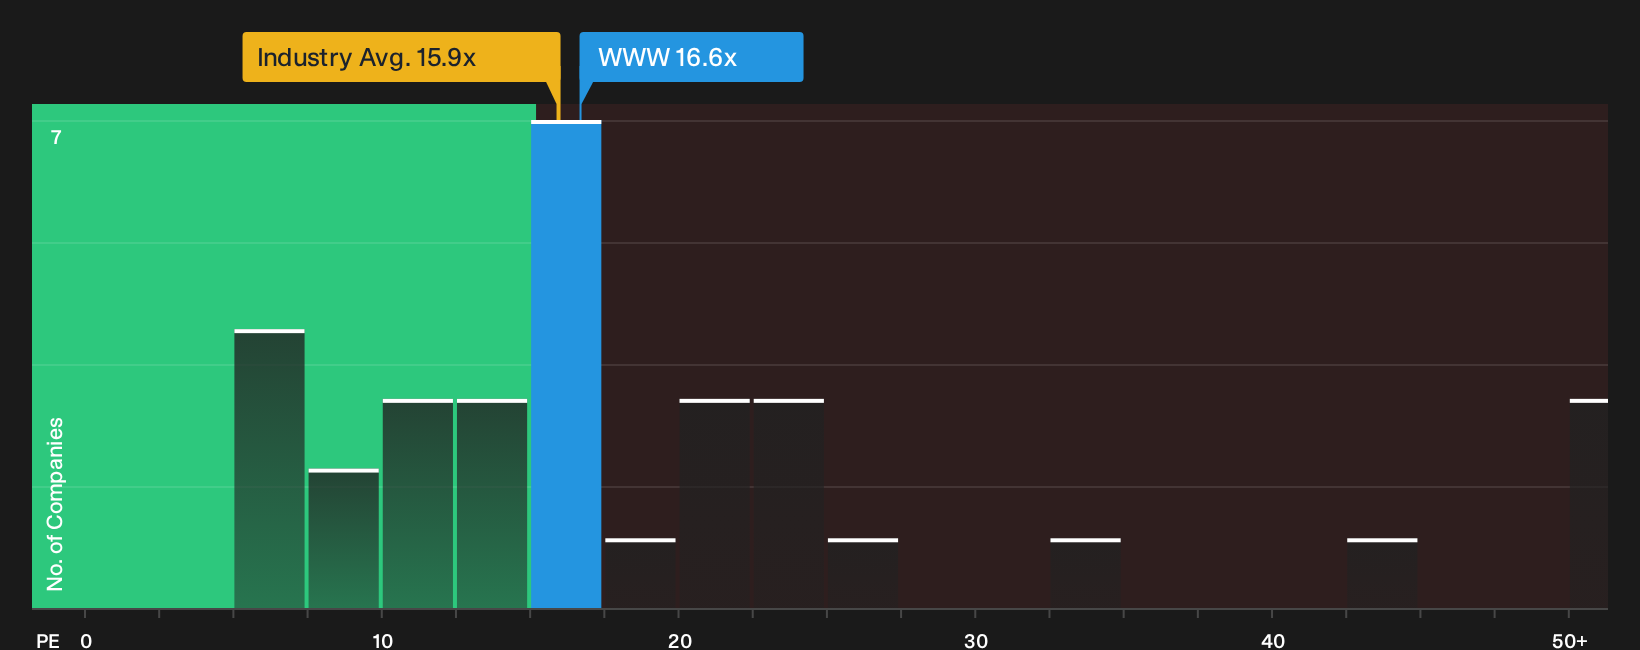
Those analyst targets and fair value models lean positive on Wolverine World Wide. The P/E picture is more cautious. At 16.6x earnings, the stock trades above peers at 15.2x, yet below a fair ratio of 19.2x that the market could move toward. Is that a margin of safety or a premium creeping in?
To see how this pricing gap lines up with quality and risk across the sector, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or quiet opportunity? Move quickly, review the full set of numbers, and weigh both sides with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Wolverine World Wide?
Do not stop with Wolverine World Wide. Broaden your watchlist now, compare fresh ideas side by side, and avoid leaving potential opportunities sitting on the table.
- Target resilience by reviewing companies with robust finances and low leverage in the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality and see which businesses screen as compelling across value and fundamentals in the 19 high quality undiscovered gems.
- Reduce portfolio stress by focusing on companies that currently carry lower risk scores through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com