


Huntington Bancshares Incorporated (HBAN) provides commercial, consumer, and mortgage banking services. With a market cap of $32.3 billion, the company offers financial products and services to consumer and business customers, including deposits, lending, payments, mortgage banking, dealer financing, investment management, trust, brokerage, insurance, and other financial products and services.
Shares of this regional bank holding company have underperformed the broader market over the past year. HBAN has gained 4.6% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.3%. In 2026, HBAN stock is down 7.3%, compared to the SPX’s 10.2% rise on a YTD basis.
Narrowing the focus, HBAN’s underperformance is also apparent compared to the iShares U.S. Regional Banks ETF (IAT). The exchange-traded fund has gained about 22.9% over the past year. Moreover, the ETF’s 10.4% gains on a YTD basis outshine the stock’s single-digit losses over the same time frame.
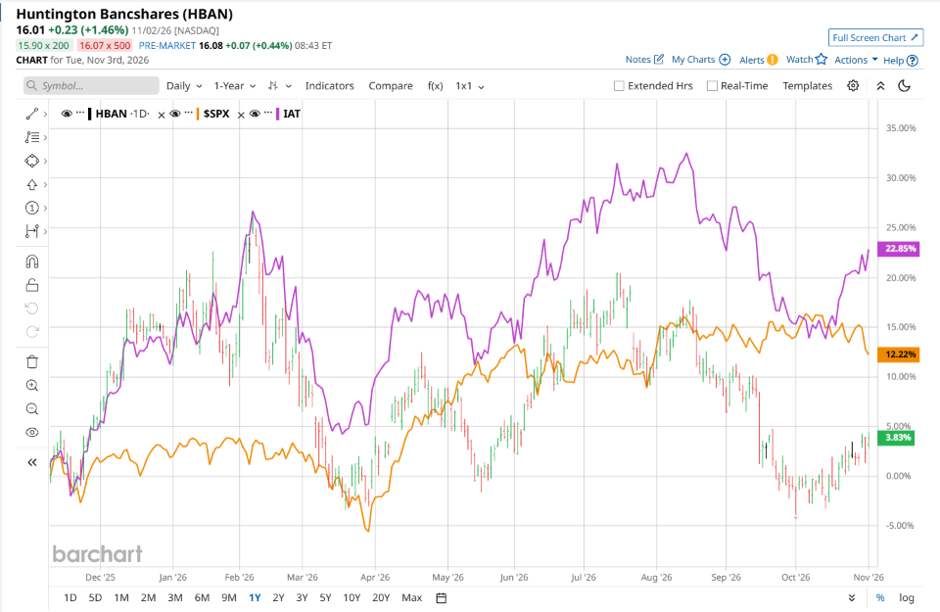
HBAN has faced relative underperformance due to persistent pressures on loan growth and fee income, alongside management's downward revisions to forward guidance. Sluggish commercial real estate and consumer loan volumes have tempered earning asset expansion, while lower capital markets fees and unfavorable equity valuation adjustments have weighed on noninterest income. Additionally, macroeconomic headwinds and concerns over credit quality trends, such as rising nonperforming asset and net charge-off ratios, have caused investors to adopt a more cautious stance on the regional bank's near-term earnings momentum.
On Oct. 22, HBAN shares closed down marginally after reporting its Q3 results. Its adjusted EPS of $0.38 met Wall Street expectations. The company’s revenue was $2.81 billion, missing Wall Street forecasts of $2.82 billion.
For the current fiscal year, ending in December, analysts expect HBAN’s EPS to grow 3.4% to $1.54 on a diluted basis. The company’s earnings surprise history is mixed. It beat or matched the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
Among the 22 analysts covering HBAN stock, the consensus is a “Moderate Buy.” That’s based on 13 “Strong Buy” ratings, one “Moderate Buy,” seven “Holds,” and one “Strong Sell.”
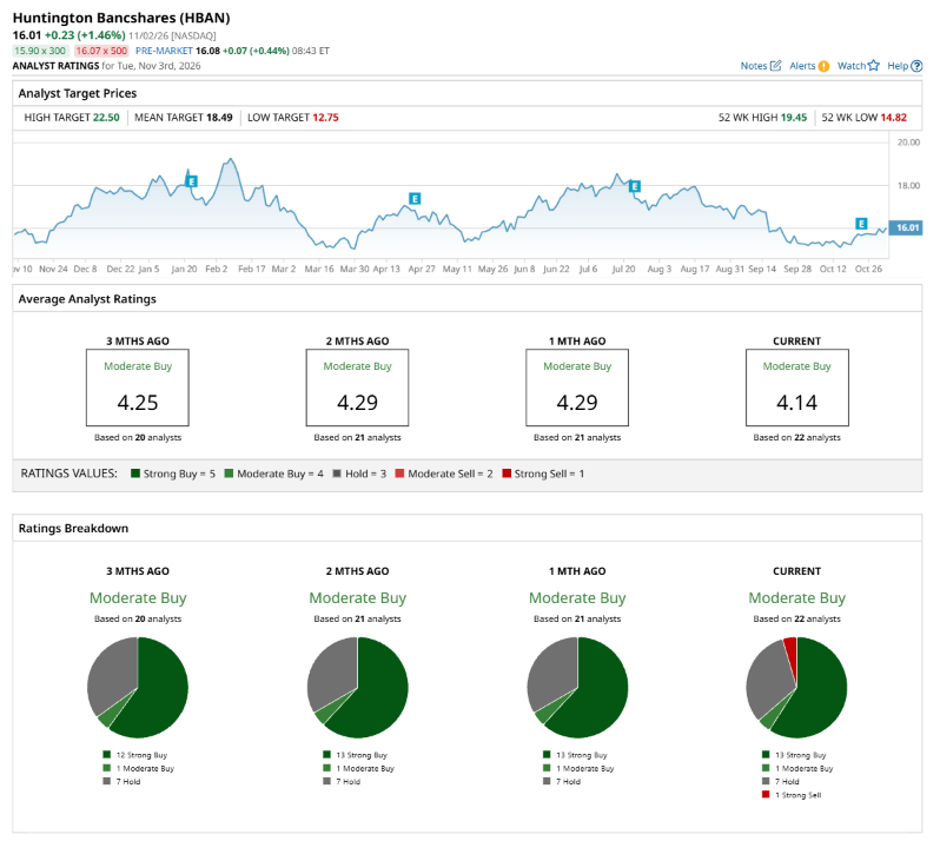
This configuration is more bullish than three months ago, with 12 analysts suggesting a “Strong Buy.”
On Oct. 30, JPMorgan Chase & Co. (JPM) kept a “Neutral” rating on HBAN and raised the price target to $18, implying a potential upside of 12.4% from current levels.
The mean price target of $18.49 represents a 15.5% premium to HBAN’s current price levels. The Street-high price target of $22.50 suggests a notable upside potential of 40.5%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.