


- Sartorius confirmed and refined its 2026 guidance, flagging tariff and customer compensation effects that could trim sales by up to €40 million. The company is still aiming for operational constant currency revenue growth around the midpoint of its 5% to 9% bandwidth.
- The group set out a new operating model from 2027. It will replace its current divisions with Bioprocessing Solutions and Research Solutions and reshape Executive Board roles to concentrate commercial and product responsibilities under a One Sartorius structure.
- Next comes a look at how Sartorius's refined growth guidance amid tariff headwinds could reshape the investment narrative around the business.
Scan how Sartorius handles tariffs and restructuring, then size up similar setups across our curated 215 resilient stocks with low risk scores that balance resilience with measured growth targets.
What Is Sartorius' Investment Narrative?
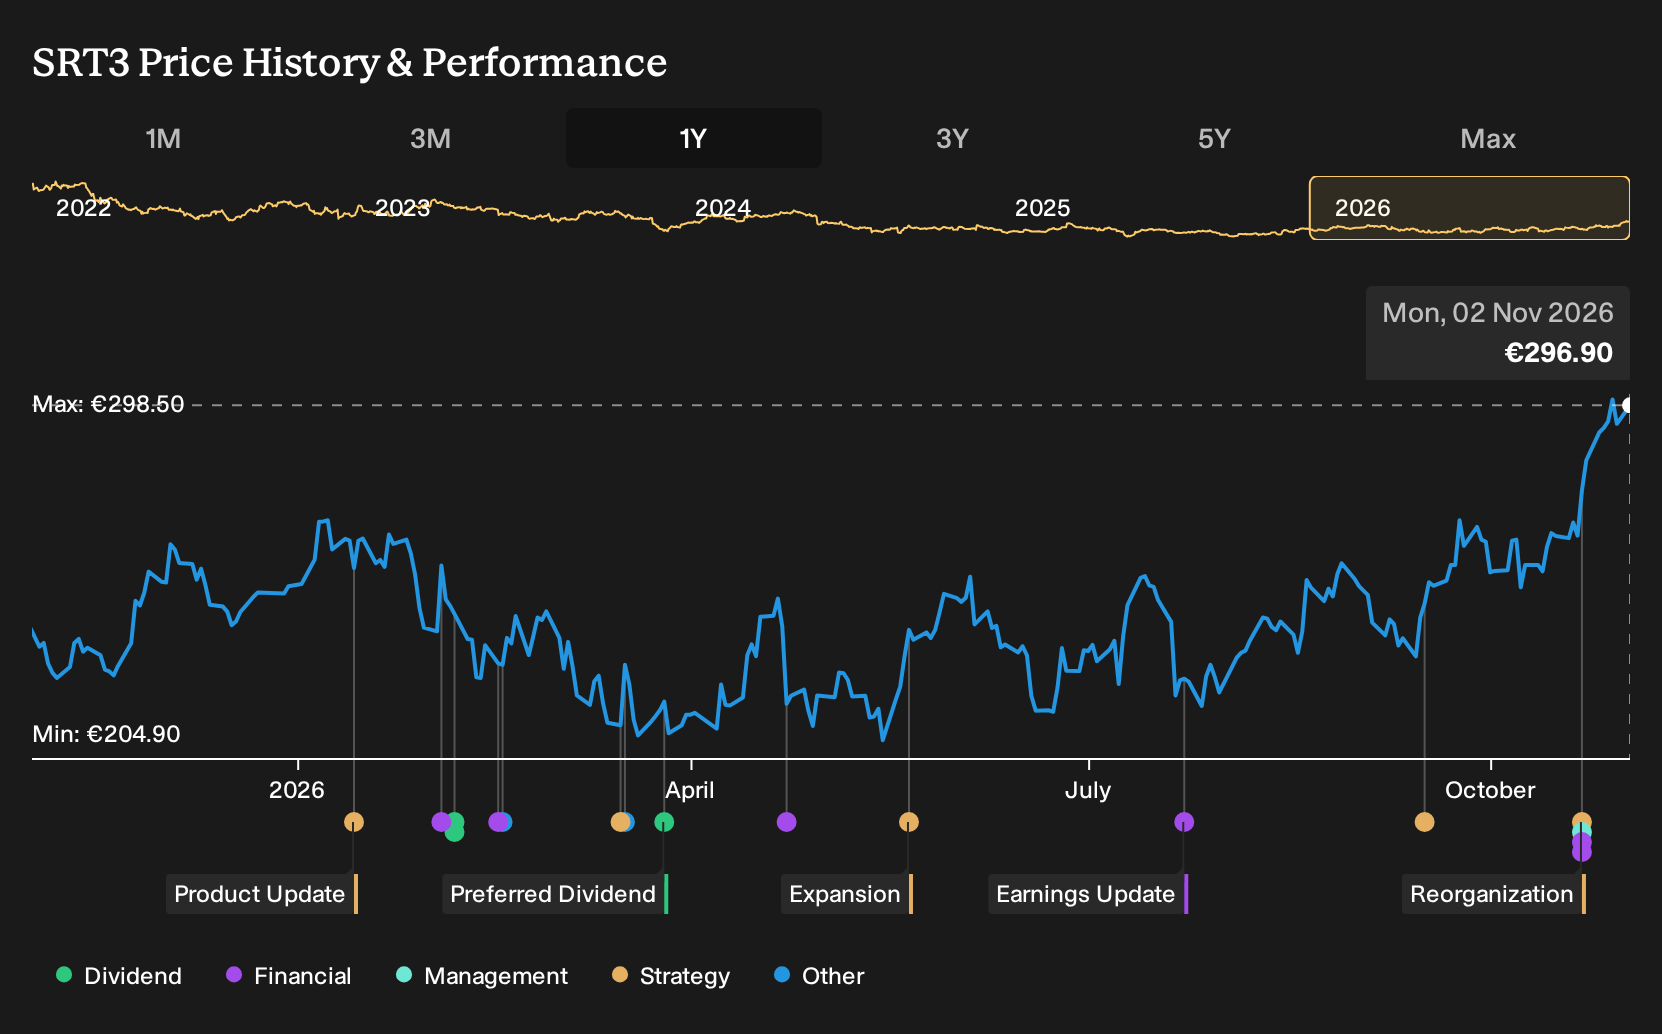
Sartorius appeals to investors who buy into a long term need for bioprocessing kit and lab tools, and who are comfortable paying up for quality and growth rather than optically low multiples. The refined 2026 guidance acknowledges tariff and compensation effects of up to €40 million, yet still points to operational constant currency growth around the midpoint of the 5% to 9% range. Third quarter sales of €926.3 million and net income of €66.1 million, together with nine month figures of €2,737.2 million and €188.3 million, provide a current snapshot of execution.
The updated operating model from 2027 and Board role shifts tighten the One Sartorius setup around product and customer focus, which matters if you care about execution rather than headlines. In the near term, the bigger swing factors appear to be the capital intensity of manufacturing, tariff treatment, and whether high P/E expectations remain supported by earnings that recently grew 63.5% year on year, set against a balance sheet that already carries a high level of debt.
That said, beneath the growth story and the new structure sits one pressure point that could quickly matter more than the tariff noise.
There's only one way to know the right time to buy, sell or hold Sartorius. Head to Simply Wall St's company report for the latest analysis of Sartorius's Fair Value.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sartorius research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sartorius. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sartorius' overall financial health at a glance.
Looking For More Investment Ideas Beyond Sartorius?
Once you have a view on Sartorius, it helps to compare that thesis with other businesses that fit different risk and income profiles using the Simply Wall St Screener.
- If you want potential mispricing with quality to back it up, scan a curated set of 194 high quality undervalued stocks that combine fundamentals with more attractive valuations.
- For investors who care most about getting paid while they wait, focus on income opportunities across a hand picked group of 222 dividend fortresses that aim to balance yield with resilience.
- When capital protection comes first, filter for stability across a list of solid balance sheet and fundamentals (196 results) and compare how those businesses stack up against Sartorius on financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com