


Why Targa Resources Stock Is Back in Focus
Fresh analyst updates around Targa Resources (TRGP) and its next earnings release are drawing attention, with expectations for higher quarterly EPS and stronger natural gas liquids activity shaping sentiment toward the stock.
Targa Resources has pulled back in the very short term, with the share price down 6.43% over the last day and 3.27% over the past week. However, a 12.07% 90 day share price return and a 57.80% year to date share price gain sit alongside a 1 year total shareholder return of 92.38% and a 5 year total shareholder return of 467.59%. This shows strong momentum as investors weigh recent export and pipeline expansions against expectations for higher earnings.
Scan beyond Targa Resources and see how other infrastructure driven energy plays are priced by checking the hand picked 34 high quality undervalued stocks shaping this corner of the market.
Short term weakness in Targa Resources after a strong run can signal a healthy reset in expectations. Is this drop more about sentiment cooling than any change in what the business is worth on the numbers?
Most Popular Narrative: 9% Undervalued
The most followed narrative pegs Targa Resources fair value at $325.14 per share, above the last close of $294.73. This puts the recent pullback in a different light and frames the current debate around whether the Permian buildout and export slate are being fully reflected in the price.
An expanding set of long dated growth projects, including the Speedway NGL system with initial 500,000 barrels per day of capacity, multiple Permian gas plants scheduled through early 2028, a 20 year processing and downstream volume agreement with a large producer and a 230 megawatt behind the meter power deal to support Permian processing, collectively increases Targa’s potential share of basin volumes and can support higher revenue and adjusted EBITDA over time.
See why 19 investors see Targa Resources as 9% undervalued.
Result: Fair Value of $325.14 (UNDERVALUED)
Still, the Targa Resources narrative can be tested quickly if Permian infrastructure becomes crowded or if project capex runs hotter than current plans assume.
Find out about the key risks to this Targa Resources narrative.
Another View: What Targa Resources Looks Like On Earnings Multiples
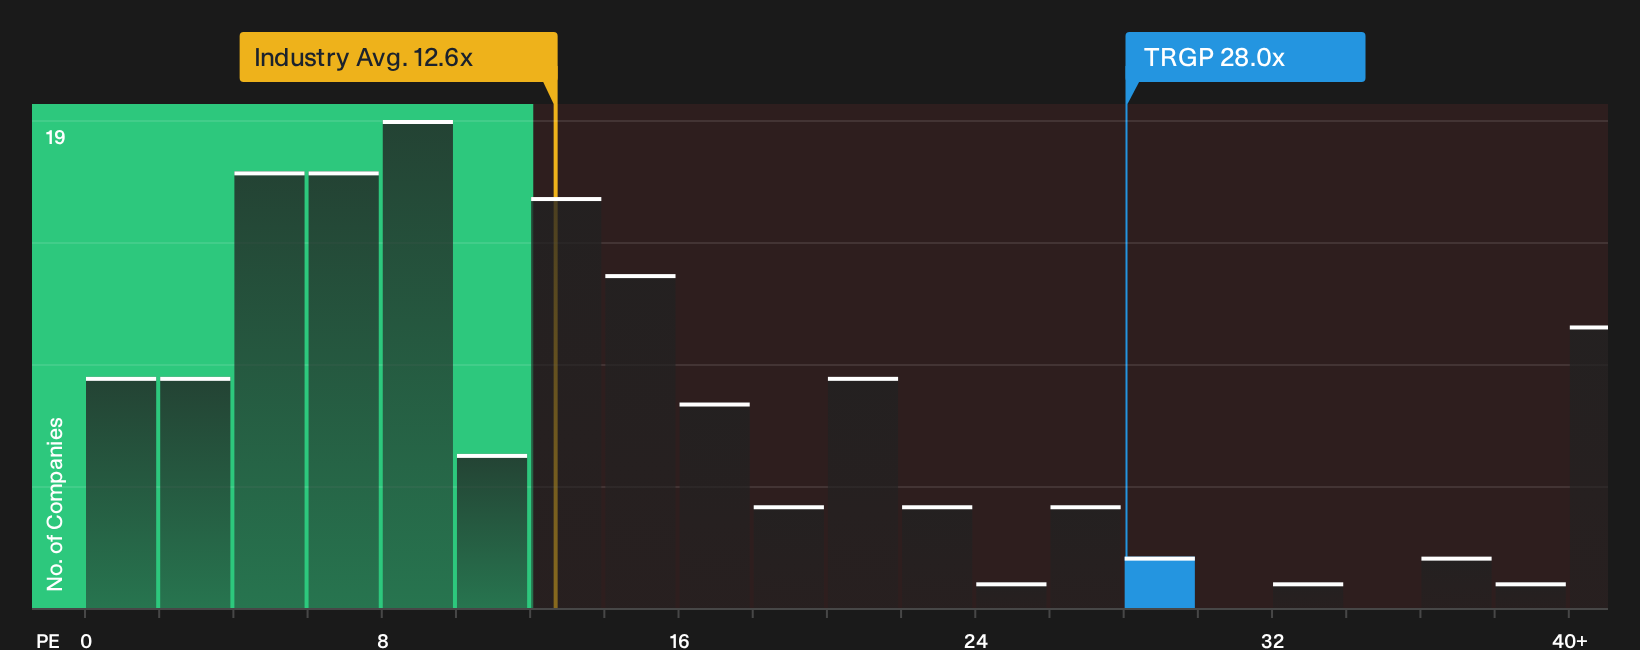
On the flip side of that fair value narrative, the current P/E of 28x screens expensive for Targa Resources against the US Oil and Gas sector on 12.6x and close peers on 17.1x. It is also above an estimated fair ratio of 23.1x that the market could eventually lean toward. If sentiment cools, would a shift toward that fair ratio hurt more than the DCF style upside helps?
To see what the earnings based ratios imply in more detail, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Targa Resources can be exciting or uncomfortable, depending on your risk appetite. Move quickly, review the data, and pressure test the bullish and cautious angles for yourself by weighing its 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Targa Resources?
If Targa Resources has your attention, do not stop here. Broaden your watchlist so you are not relying on a single story for potential returns.
- Target resilience first and scan a 29 resilient stocks with low risk scores that focuses on businesses with more durable profiles when markets turn choppy.
- Hunt for value by reviewing a 19 high quality undiscovered gems that highlights companies with strong fundamentals that fewer investors are watching closely.
- Put quality front and centre and use a list of solid balance sheet and fundamentals (24 results) to focus on enterprises with sturdier finances backing their operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com