


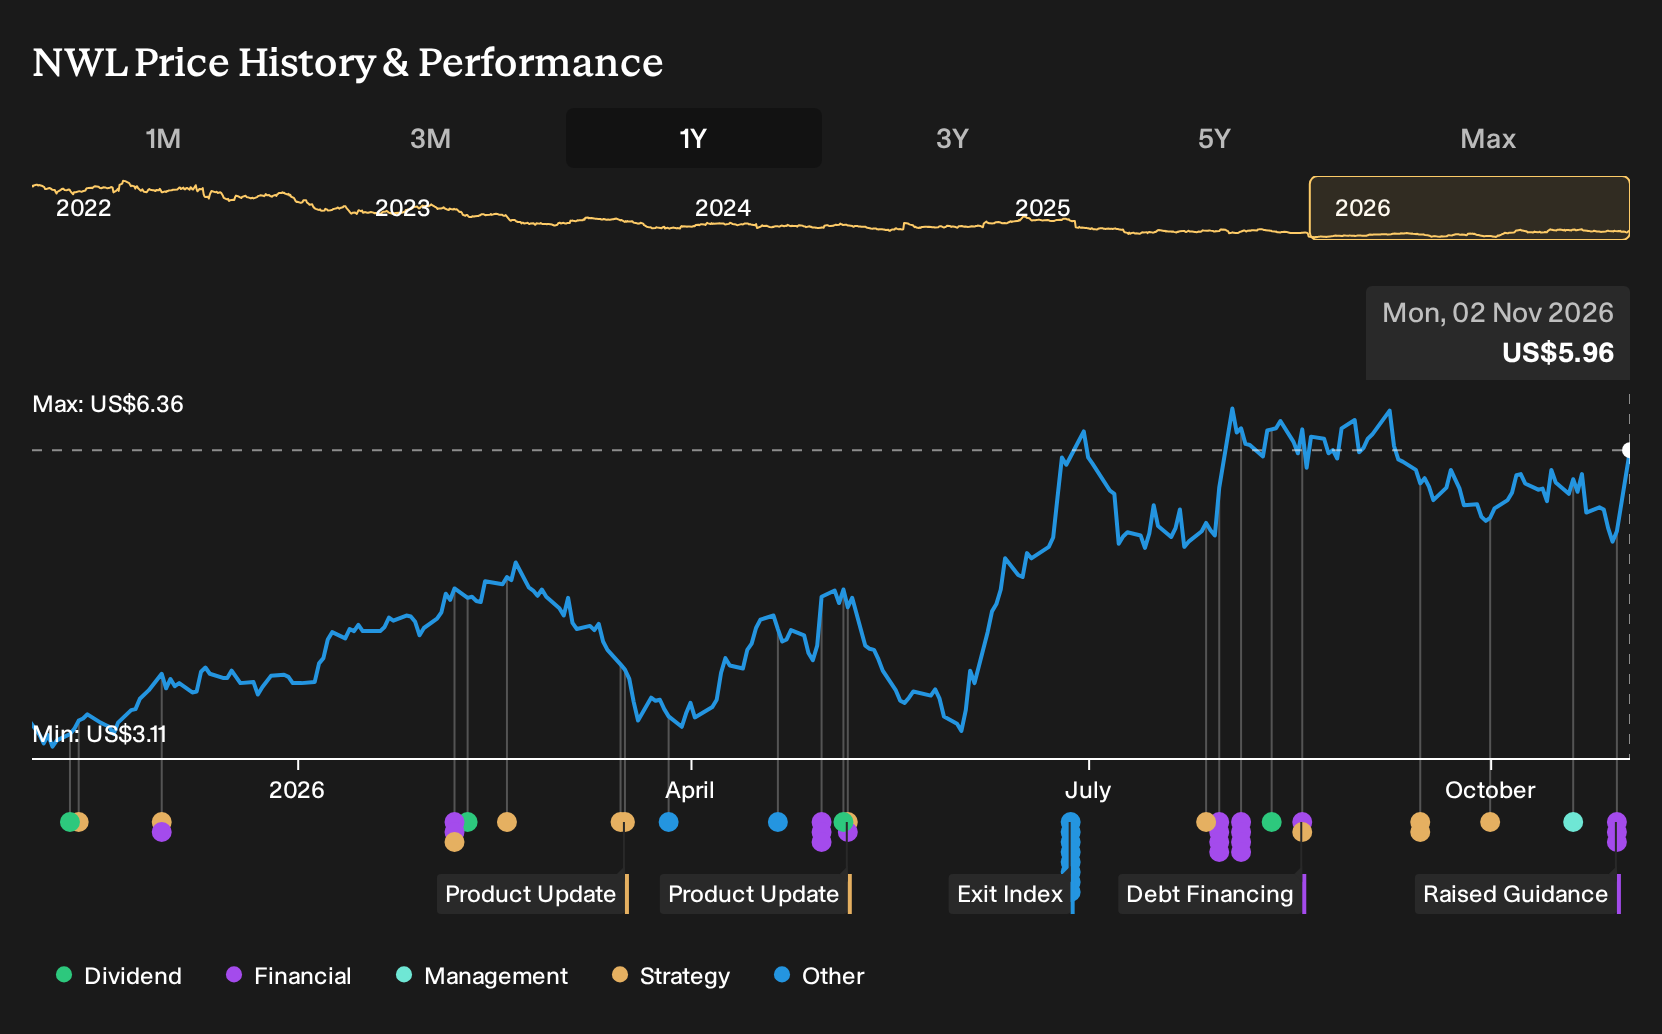
- Newell Brands reported third quarter 2026 sales of US$1.873b and a net loss of US$81 million, and raised full year 2026 net sales growth guidance to 2% to 3% after two consecutive quarters of year over year sales gains and margin expansion.
- The upgraded outlook followed net sales and core sales growth that exceeded guidance ranges. Normalized operating margin for the quarter reached 9.8% as higher sales and productivity improvements offset inflation pressure.
- We will look at how Newell Brands' raised full year sales outlook reshapes the investment narrative built around margin recovery.
Scan how Newell Brands' margin recovery story compares with other consumer stocks by reviewing our hand picked 34 high quality undervalued stocks that pair resilient cash generation with disciplined balance sheets.
Newell Brands Investment Narrative Recap
To own Newell Brands, you need to believe that gradual sales momentum and productivity gains can eventually outweigh current losses and a stretched balance sheet. The latest quarter supports that thesis on operations. Net sales grew versus last year and normalized margins improved, and management felt confident enough to raise full year net sales growth guidance to 2% to 3%.
The near term catalyst is sustained volume and margin improvement while the business is still reporting losses, including the US$81 million loss in the quarter and US$8 million loss year to date. The key risk remains execution under elevated leverage and interest costs if consumer demand softens again.
The appointment of Guillermo Beade as Chief Operating Officer looks closely tied to the operational story investors are watching. He takes responsibility for global marketing, sales, and supply chain, which are exactly the areas that influence whether higher volumes and productivity persist beyond a couple of quarters.
Newell Brands already leans on cost savings, product refreshes, and better omnichannel execution as core catalysts. A seasoned CPG operator with experience across North America and international regions can help tighten that playbook and pressure test where pricing, mix, and distribution still leave money on the table or expose the business to share loss risk.
What The Newell Brands Consensus Is Pricing In
Newell Brands' analyst story is built on a slow rebuild. Forecasts point to revenue rising by about 1.9% a year over the next three years and a swing in profit margins from a 3.0% loss today to 7.3% in roughly three years.
On earnings, the shift is even more pronounced. Analysts see the business moving from a loss of US$221.0 million today to earnings of US$557.1 million by around 2029. This represents an earnings improvement of roughly US$778 million. The consensus path implies earnings per share of about US$1.29 by that year, supported by modest share count growth of 1.6% a year.
To make those assumptions line up with current analyst targets, the stock would need to trade on a P/E of 7.6x those 2029 earnings, compared with the current multiple of 11.0x on today's loss making base. That 7.6x level sits below the US Consumer Durables sector average of 12.8x cited in the report. This leaves some room if the business overshoots expectations, but also limits the valuation safety net if forecasts prove too optimistic.
Newell Brands' narrative projects US$7.7b revenue and US$557.1 million earnings by 2029. This requires 1.9% yearly revenue growth and an earnings increase of roughly US$778 million from the current US$221.0 million loss.
Uncover why Newell Brands' fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate Newell Brands storyline puts less weight on sales guidance and more on tariff and cost headwinds. The most bearish analysts were only assuming about 1.2% annual revenue growth and roughly US$390 million of earnings by 2029 before this update. That is a much harsher view. Consider using it as a prompt to compare several angles and stress test your own expectations as this new information filters into forecasts.
Explore 3 other Newell Brands fair value estimates, including one that suggests it could be worth just $6.41.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Newell Brands research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Newell Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newell Brands' overall financial health at a glance.
Looking For More Investment Ideas Beyond Newell Brands?
If Newell Brands has helped sharpen your view on turnarounds and margin rebuild stories, use that same lens across the wider market. The Simply Wall St Screener lets you quickly filter for companies that fit the risk, balance sheet strength, and income profile that matches your own approach.
- If you want potential mispricing paired with quality fundamentals, start with a curated 19 high quality undiscovered gems that many investors may not be watching yet.
- If downside resilience matters most to you, run your eye over a 29 resilient stocks with low risk scores that filters for businesses with more measured risk scores.
- If balance sheet strength is non negotiable in your process, narrow your watchlist using a list of solid balance sheet and fundamentals (24 results) that filters for companies with sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com