


Xero (ASX:XRO) just rolled out a first of its kind embedded integration with Bookkeeper360, powered by Melio, letting accounting firms offer branded AP and AR tools inside their existing platforms.
For context, Xero’s share price has climbed 8.9% over the past month but is still down 43.9% year to date, and the 1 year total shareholder return is weaker again at a decline of 56.8%. This points to recent momentum improving off a low base despite longer term holders still sitting on sizeable losses.
Scan beyond Xero and see how other software and payments players are setting up for the next leg by reviewing our hand picked 14 high quality undiscovered gems.
The rebound in Xero after a heavy year of losses leaves you with a familiar fork in the road. Is this the early stage of a reset worth paying up for now, or a bounce that still asks you to wait for a cheaper shot?
Most Popular Narrative: 53% Undervalued
Against Xero's last close at A$63.02, the most followed narrative pegs a fair value of A$133.38. This implies a wide gap for investors to weigh against the recent share price rebound.
Increasing subscriber numbers alongside increasing ARPU yields 20% annual revenue growth as more and more businesses turn to cloud based accounting solutions with strong integrations and eventual AI features to run their businesses. Xero has high scalability of its products, with current gross margin of ~88%.
See why 23 investors see Xero as 53% undervalued.
According to KiwiInvest, the story hinges on Xero using that high gross margin and scalable platform to push more revenue through relatively stable operating costs, with AI tools used to speed up feature development rather than replace the core accounting product. The narrative also flags that trust in data accuracy and platform uptime remains critical for any accounting software. This could separate resilient providers from weaker SaaS peers as AI tools spread through the sector.
Result: Fair Value of A$133.38 (UNDERVALUED)
Still, the thesis around Xero leans heavily on AI tools helping rather than hurting, and on accounting customers trusting automation that mishandles neither numbers nor uptime.
Find out about the key risks to this Xero narrative.
Another View On Xero’s Valuation
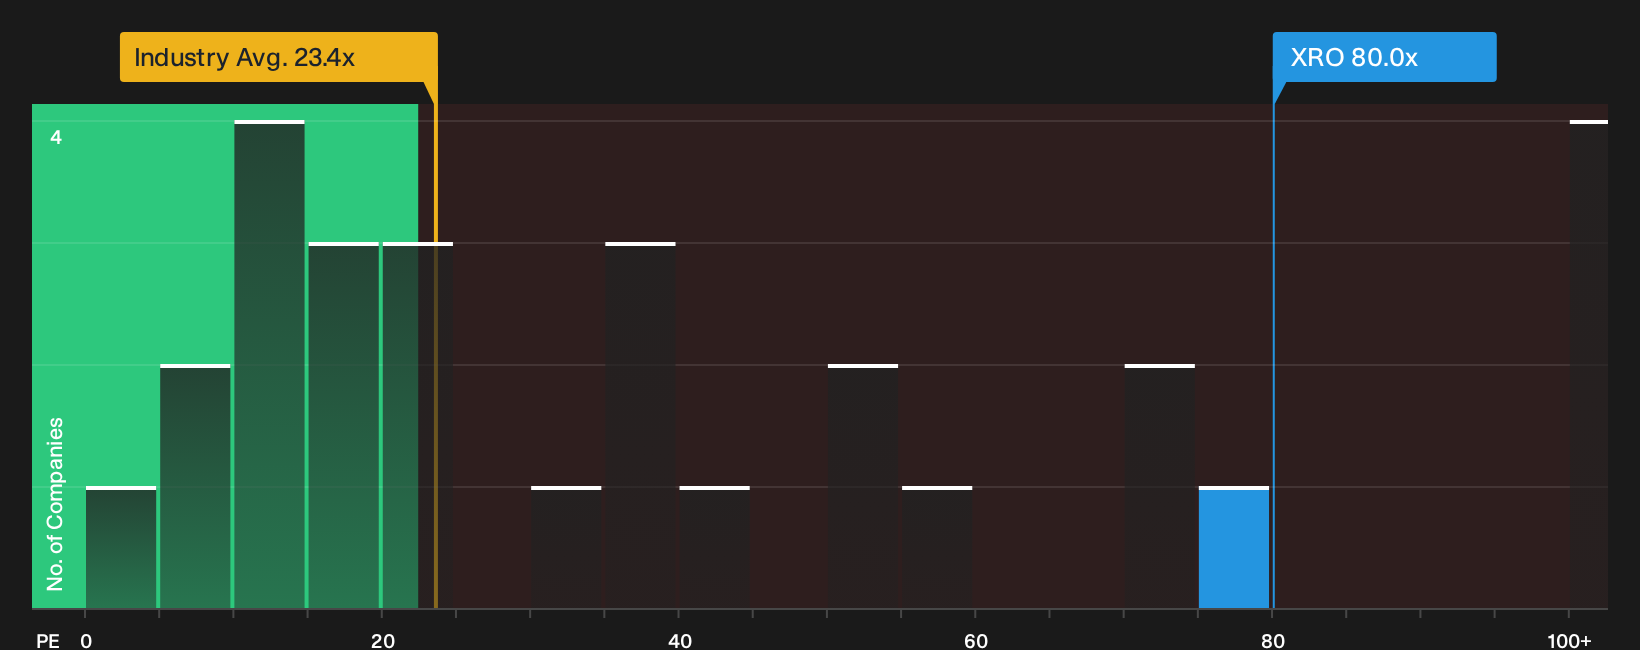
The first narrative leans on Xero being materially undervalued, yet the current P/E of 80x paints a tougher picture. The fair ratio sits at 49.6x, the Australian software average at 23.4x, and peers around 41.6x. That premium piles more pressure on execution. How comfortable are you paying that much up front for potential growth years away?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone of Xero’s story so far leaves you undecided, consider acting promptly: review the numbers yourself and weigh both sides through 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Xero?
Do not stop with one stock. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match how you like to invest and manage risk.
- Target resilient balance sheets by reviewing companies in the list of solid balance sheet and fundamentals (12 results) that pair financial strength with room for future potential.
- Hunt for mispriced quality and see which candidates in the 2 high quality undervalued stocks currently trade at a discount to their fundamentals.
- Prioritise stability and sleep-at-night comfort by scanning the 6 resilient stocks with low risk scores that filters for businesses with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com