


Peace talks over Ukraine have shifted from distant headline to live event, and markets are already weighing what a possible reconstruction wave might mean for European infrastructure stocks. If rebuilding gains political backing and funding, capital could start hunting for companies tied to concrete, cables and cranes. This article walks through three stocks from our Ukraine Reconstruction Beneficiaries screener and explains why each might deserve a place on your watchlist.
The stocks covered below are only a small sample of the idea, and the full screen surfaced 51 more European infrastructure, engineering and materials businesses with equally compelling reconstruction narratives that do not fit into a single article. To see the wider field and start sorting for your own highest conviction watchlist, head straight to the European Infrastructure, Engineering and Materials – Ukraine Reconstruction Beneficiaries screener.
Grupa Kety (WSE:KTY)
Overview: Grupa Kety is a Poland based producer of aluminum profiles, architectural systems, and sun shading solutions that supply construction and infrastructure projects across Europe.
Operations: Grupa Kety generates about PLN 2.3b from Extruded Products, PLN 2.1b from Architectural Systems, PLN 1.2b from Flexible Packaging and PLN 1.1b from Sun shading Systems, with revenue concentrated in Poland and the wider EU.
Market Cap: PLN 12.4b
For investors looking at Ukraine reconstruction as a long term theme, Grupa Kety offers direct exposure to aluminum based building products that could feed into everything from frames to facades across the region.
"As the estimated PLN 20–50m raw material FIFO uplift in the Extruded Products Segment in Q3 2026 falls away and management expects this effect to be insignificant in Q4, EBITDA can reset lower once this temporary benefit is gone, which would pressure earnings and could expose how much of the recent profit strength was non repeatable."
The real swing factor for Grupa Kety is whether underlying demand and pricing can keep profit margins resilient once that one off tailwind fades.
If you want to see whether that margin reset masks a stronger long term story, read the full narrative for Grupa Kety to see what could keep Grupa Kety compounding quietly.

Budimex (WSE:BDX)
Overview: Budimex is a Polish construction group that builds roads, rail, bridges and public infrastructure across Poland and the wider European Union.
Operations: Budimex generates about PLN 9.1b from Construction Activity and PLN 1.1b from Service Activities, with roughly PLN 8.9b of revenue coming from Poland.
Market Cap: PLN 18.2b
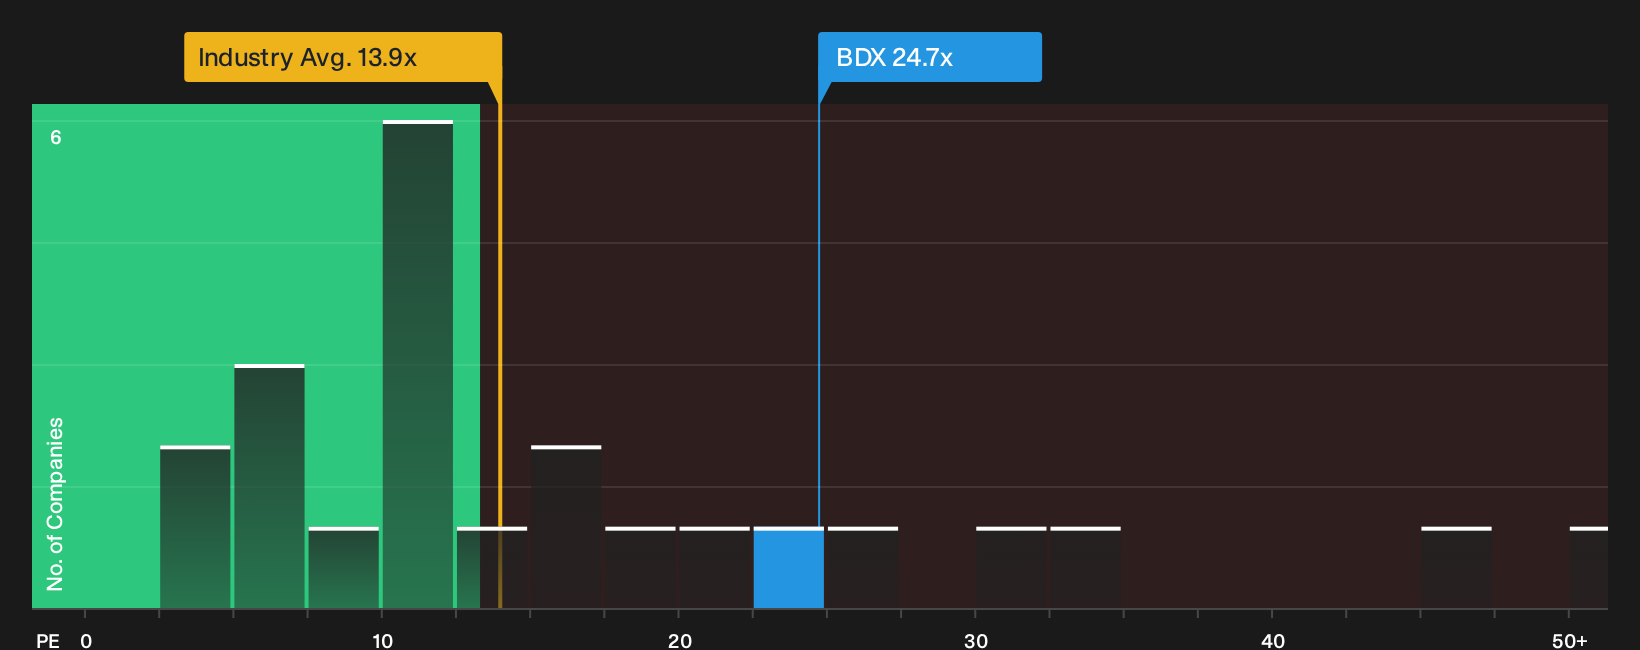
Budimex provides direct exposure to large scale civil engineering in Poland and nearby EU markets, at a time when governments are preparing for Ukraine reconstruction and related infrastructure spending. Strong earnings momentum and high return on equity indicate that the builder is executing well on current projects. However, the premium P/E and heavy reliance on external funding represent a pressure point that could change how future work translates into shareholder returns.
Those pressure points matter for future returns, so check the 2 key rewards and 1 important major warning sign to see whether Budimex's premium P/E is stretching or just tracking execution.
HOCHTIEF (XTRA:HOT)
Overview: HOCHTIEF is a Germany-based construction group that builds and manages large civil, industrial and infrastructure projects worldwide.
Operations: HOCHTIEF generates about €27.7b from Turner, €10.5b from CIMIC and €1.7b from Engineering and Construction in Europe and North America.
Market Cap: €28.4b
For investors focusing on Ukraine reconstruction, HOCHTIEF brings long experience in complex civil works and large project delivery. This is the kind of capability governments often look for when committing multi year rebuilding budgets.
"Surging demand for AI driven digital infrastructure, with HOCHTIEF reporting around €16.8 billion of data center orders in 2025 and data centers already at 21% of the backlog, provides multi year visibility that could support higher revenue and operational earnings if margins in this segment remain firm."
The real test comes if a quiet shift in its project mix changes how much of that future backlog ultimately translates into cash profit.
If that shift in mix is what really steers future cash, read the full narrative for HOCHTIEF to see whether HOCHTIEF’s backlog is quietly decoupling earnings from risk.

Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout themes, new momentum and quietly flying under the radar stories tend to get caught early by prepared investors, not bystanders. Do not delay. Get in early.
- Target reliable income streams while others chase headlines by reviewing the 222 dividend fortresses that have been filtered for yield and balance sheet strength.
- Spot potential future leaders in fast moving tech by scanning the 159 AI small caps before their momentum shows up on everyone else's radar.
- Hunt for resilient balance sheets and disciplined capital allocation using the list of solid balance sheet and fundamentals (196 results) so you are focusing on sturdier businesses while it still matters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com