


Key Points
Plug Power grew sales at a brisk pace between 2015 and 2025.
However, cash flow from operations has been consistently in the red.
Plug's share count has also risen dramatically in the last decade.
While Plug Power (NASDAQ: PLUG) stock has captured growth investors' hopes and dreams for over two decades, I've consistently preferred a bearish stance. My icy feelings toward the fuel cell stock, however, have recently started to thaw with the company's improving financials and a change in management.
But the thought of clicking the buy button on Plug stock remains unlikely for the time being. This could certainly change, though, after the company reports third-quarter 2026 financial results in the coming days.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »

Image source: Getty Images.
Poor cash flow has represented a perennial woe
Let's give Plug Power credit where credit is due. The company has excelled at growing sales over the past decade. From 2015 through 2025, Plug has seen sales rise at a 21.3% compound annual growth rate (CAGR).
The company's achievement on the income statement hasn't translated to the cash flow statement. Over the past decade, Plug has consistently reported negative cash from operations -- a troubling sign in and of itself but especially concerning when juxtaposed with the success that fuel cell peer Bloom Energy (NYSE: BE) has demonstrated. In the first half of 2026, Bloom Energy has reported $300 million in operating cash flow, while Plug has reported negative $244 million in operating cash flow during the same period.
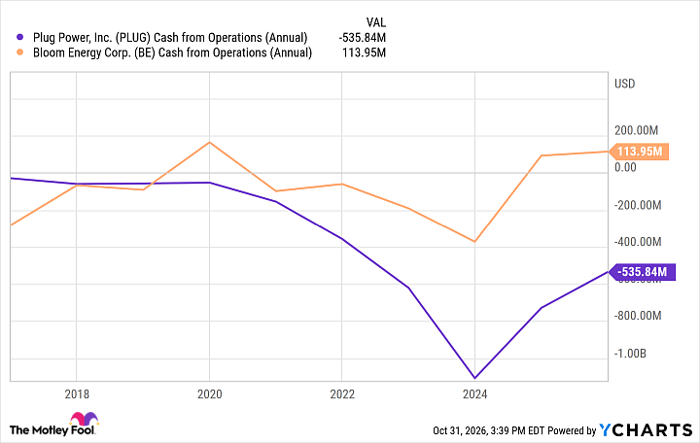
PLUG Cash from Operations (Annual) data by YCharts
While both companies have struggled to generate operating cash flow for years, Bloom has blossomed in this regard over the past two years.
Due to its inability to generate organic cash flow, the company has resorted to raising capital through equity issuance, thereby subjecting investors to shareholder dilution. From March 2016 to February 2026, Plug's outstanding share count grew from over 180 million to about 1.4 billion.
Don't be dazzled by the income statement
It's likely that Plug will continue to post sales increases in the coming quarters, but it's all for naught if the company can't generate organic cash. Until it can achieve this feat, Plug Power stock is essentially a sinkhole for shareholder value -- not a sound investment.
Scott Levine has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Bloom Energy. The Motley Fool has a disclosure policy.