


Waters (WAT) stepped into the spotlight after third quarter results came in ahead of expectations, prompting an increase to full year guidance and coinciding with the purchase of an advanced molecular analysis specialist.
Waters shares have eased in the very short term, with a 1-day share price return of 2.85% lower and a 7-day share price return of 1.41% lower. However, the stock has built clear momentum over 2026, with a 90-day share price return of 13.49% and a year-to-date share price return of 17.69%. This has contributed to a 1-year total shareholder return of 30.08% and a 3-year total shareholder return of 78.28%, as investors weigh the stronger earnings guidance alongside product launches and new partnerships in clinical diagnostics and AI-enabled software.
Scan beyond Waters and compare this earnings momentum and AI push with a hand-picked group of lab, diagnostics, and tools companies in the 33 healthcare AI stocks.
Waters now combines a long-established lab tools franchise with fresh AI and clinical diagnostics deals, and the share price has already reacted. The next step is simple: Are investors paying a fair price for that strength today?
Most Popular Narrative: 2% Undervalued
Waters last closed at $449.53, a touch below the most followed narrative fair value of about $458.22. This frames the current debate around how much of its AI and diagnostics pipeline is already reflected in the price.
Waters is set up to benefit from a prolonged instrument replacement and pharma reshoring cycle, with LC and LC MS instruments showing a strong replacement backlog that management expects to run at least through 2027 and an additional outfitting wave linked to about US$100b of U.S. pharma CapEx from 2027 to 2030. This can support sustained equipment revenue and related service growth.
See why 17 investors see Waters as 2% undervalued.
Result: Fair Value of $458.22 (UNDERVALUED)
Still, the Waters narrative could be knocked off course if BD integration stumbles and if China weakness in the acquired units drags on longer than investors expect.
Find out about the key risks to this Waters narrative.
Another View: What Multiples Say About Waters
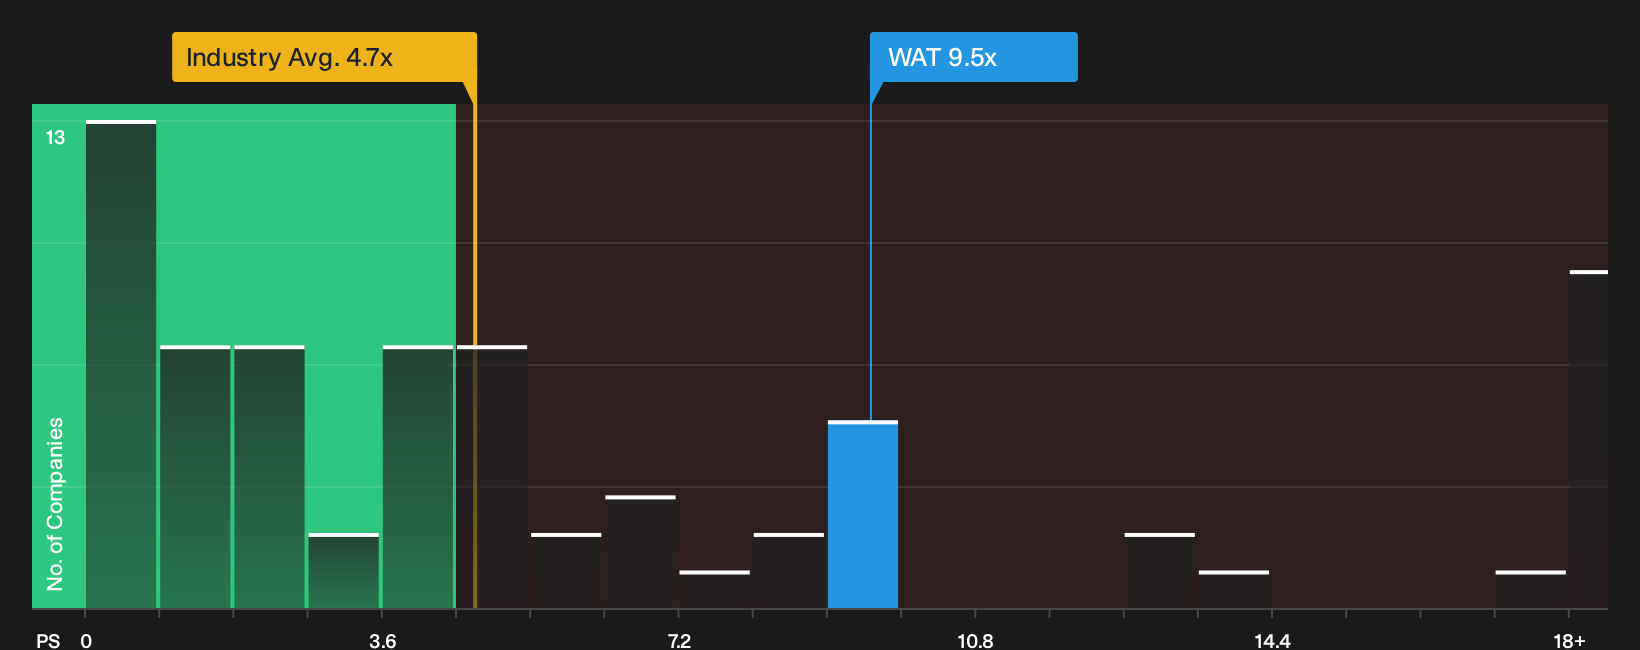
The narrative fair value pegs Waters at about $458 per share and frames the stock as roughly 2% undervalued. The market is not quite as generous when you look at sales based valuation. Waters trades on a P/S of 9.5x, compared with 4.7x for the US Life Sciences group and 6.2x for its peer set, and a fair ratio of 8.2x. That gap points to investors already paying a premium for quality and execution. The open question is whether you are comfortable paying above both peers and the fair ratio for this AI and diagnostics story.
For a closer look at how these multiples compare with what the fair ratio suggests the market could move toward over time, and what that might indicate for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Opinions are mixed about whether Waters is priced fairly after this run. Take a moment to weigh the potential upside and downside, then stress test your own thesis against the 1 key reward and 3 important warning signs.
Looking for more Waters-sized investment ideas?
Do not stop with just one opportunity. Broaden your watchlist now and pressure test your Waters thesis against other stocks that fit different roles in a portfolio.
- Target potential mispricings by scanning companies that show strong fundamentals yet trade at a discount using the 34 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that combine robust yields with staying power in the 4 dividend fortresses.
- Dial back risk while keeping upside on the table by filtering for resilient businesses through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com