


Frontier Group Holdings (ULCC) has become a live case study in how macro forces intersect with company fundamentals, with a sharp move in oil prices and fresh quarterly results pulling investor focus to fuel costs, breakeven potential, and ongoing losses.
The latest move in oil has hit Frontier Group Holdings at a moment when momentum is already volatile, with the 1 day share price return of 15.19% and 7 day share price return of 51.32% coming after a 90 day share price decline of 7.01% and a 5 year total shareholder return decline of 57.03%.
Scan other fuel sensitive airlines showing similar volatility with our 34 high quality undervalued stocks as a reference point beside Frontier Group Holdings today.
Frontier Group Holdings now trades near US$7.43 while analyst targets cluster closer to US$6.61 and one intrinsic estimate implies a far higher figure. Where might fair value realistically sit after this oil driven surge?
Most Popular Narrative: 11% Overvalued
Against the most followed fair value estimate of $6.67, Frontier Group Holdings at $7.43 screens as richer than that narrative implies. This places more weight on execution than on multiple expansion from here.
The company's focus on serving cost-conscious travelers in growing secondary and Sun Belt markets is well aligned with the broader shift toward value-driven consumer preferences and ongoing U.S. population migration, Frontier's demand outlook in these markets supports expectations of higher load factors and consistent revenue growth.
See why 13 investors see Frontier Group Holdings as 11% overvalued.
Result: Fair Value of $6.67 (OVERVALUED)
Still, ongoing losses of $413 million, along with concerns around oversupply and cost pressures, could quickly challenge this Frontier Group Holdings fair value story.
Find out about the key risks to this Frontier Group Holdings narrative.
Another View: Frontier Group Holdings Through A Cash Flow Lens
The market may see Frontier Group Holdings as 11% above the most followed fair value estimate of $6.67, yet the SWS DCF model points in a very different direction. In that framework, ULCC at $7.43 trades well below an implied value of $47.94, which frames the current quote as heavily discounted rather than rich. Which narrative do you think better reflects the risk around fuel costs, debt and future profitability?
Look into how the SWS DCF model arrives at its fair value.
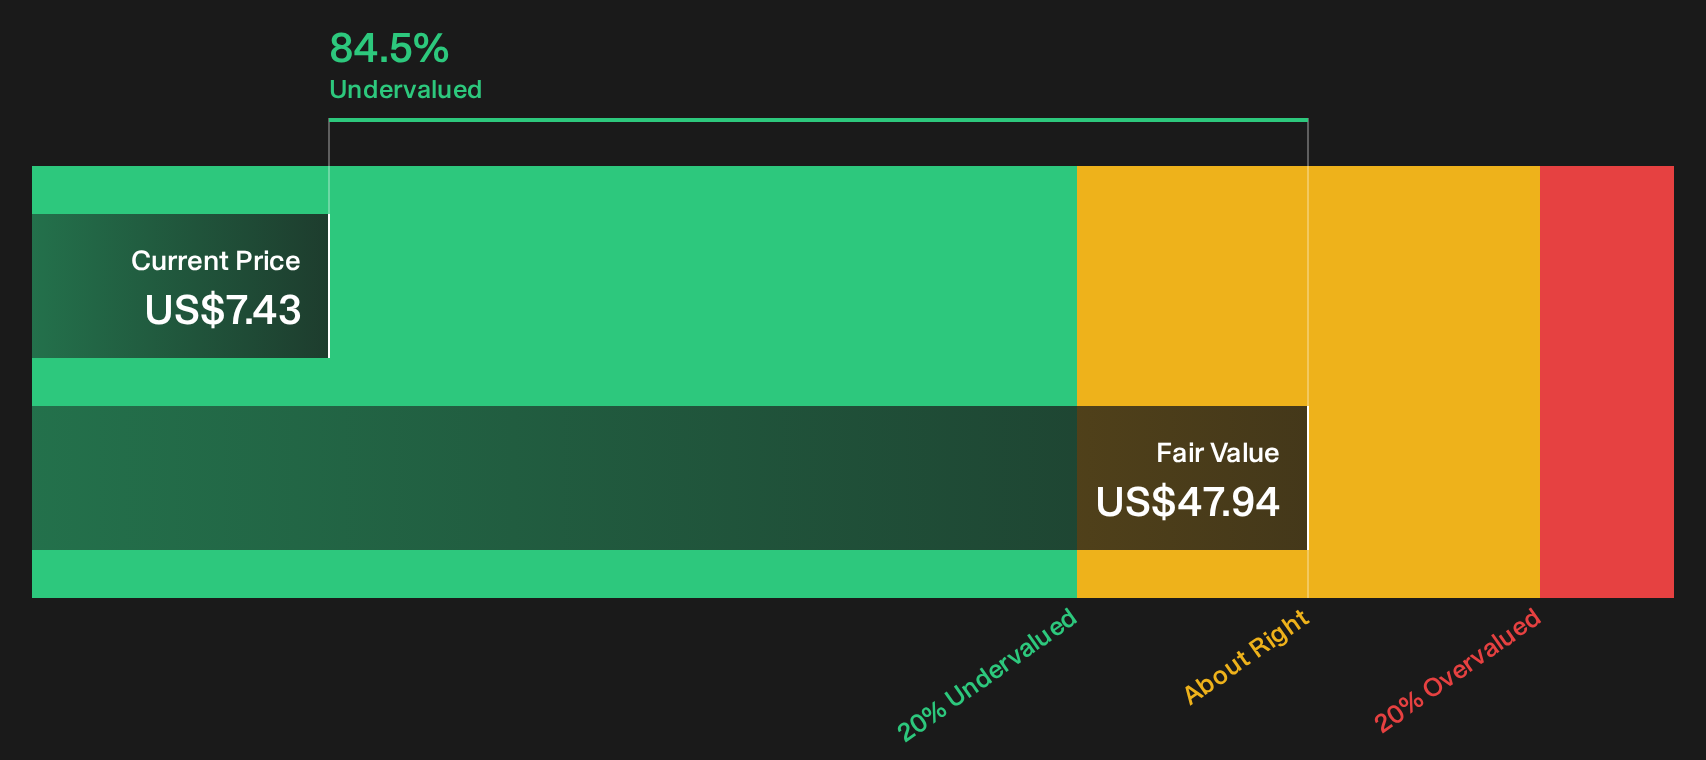
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Frontier Group Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Frontier Group Holdings is clearly split, with fuel risk on one side and potential upside on the other. Weigh the evidence quickly and decide where you stand by reviewing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Frontier Group Holdings?
You do not need to stop with Frontier Group Holdings. Use the Simply Wall Street Screener to widen your watchlist and stress test your thinking across other sectors.
- Target resilient opportunities by reviewing companies in the 29 resilient stocks with low risk scores that may better match your comfort with volatility.
- Hunt for mispriced quality and see which businesses in the 19 high quality undiscovered gems align with your view on fundamentals.
- Focus on financial strength and scan the list of solid balance sheet and fundamentals (24 results) to compare balance sheet resilience across your shortlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com