


Coherent has shifted from a sharp multiyear surge to a steep recent pullback. That mix of outcomes puts a simple question in front of you as an investor: Does the current share price line up with what the company is actually earning today and what those earnings may reasonably support over time?
- Over the past 3 years the stock has delivered a very large gain, which makes it important to ask how much of that move is backed by underlying earnings power rather than changing sentiment alone.
- Recent analyst upgrades that emphasize Coherent's photonic device capacity and AI related customer interest point to expectations for higher earnings in future years, which can affect how much investors are prepared to pay for each dollar of current profit.
- There is a second opinion on Coherent worth weighing. See what analysts think Coherent's shares could be worth.
The issue now is whether Coherent's current valuation is justified by its earnings profile once you set the recent share price swings and news flow against what the business is actually generating.
If you are weighing Coherent against other AI related plays that are also tied to chip and photonics themes, a focused stock screen can be a useful second starting point for research through 39 AI small caps
Is Coherent Getting Expensive on Earnings?
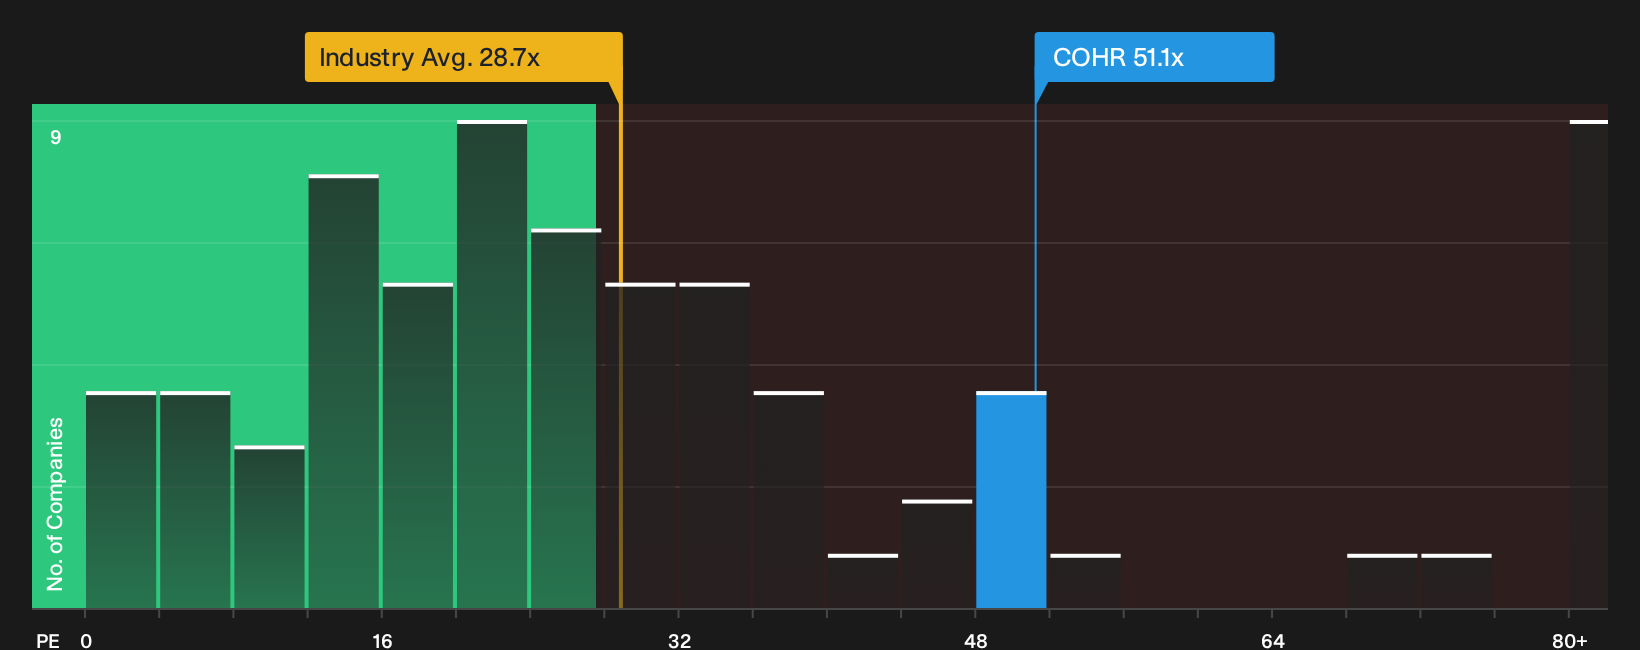
P/E fits Coherent because the current debate is about how much investors are paying for today’s earnings relative to other chip and photonics plays. On this yardstick, Coherent trades at about 51.1x earnings, well above the Electronic industry average of roughly 28.7x and ahead of the peer group near 38.5x. The share price is therefore placing a much richer tag on each dollar of profit than many comparable hardware and component makers.
The fair multiple implied by a more tailored model that factors in Coherent's growth runway, margins, scale and risk profile sits below the current 51.1x P/E. This flags the stock as overvalued on this framework. Because recent analyst upgrades linked to AI photonics interest have pushed expectations higher, the current premium P/E already reflects a lot of that optimism relative to sector benchmarks. That leaves you weighing whether Coherent's earnings profile can justify paying this kind of mark up or whether the present P/E leaves limited room for disappointment. Explore the numbers behind Coherent's P/E valuation.
The Coherent Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle leaves off for Coherent by spelling out which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than it is today. Each scenario ties a grounded fair value to a particular mix of potential catalysts and practical risks, so you can track over time which version of Coherent's story is actually unfolding on Simply Wall St's Community page.
One of the top community narratives on Coherent: 24% undervalued
"The current valuation implies that Coherent’s share price does not fully reflect management’s targets for over $3 billion in quarterly revenue…"
Discover why this Narrative puts Coherent at 24% undervalued.
One more angle on Coherent that is easy to miss
There is a final clue worth checking before you move on, because professional estimates for Coherent a few years from now offer a separate reality check against everything that is priced in today. Explore where analysts expect Coherent to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com