


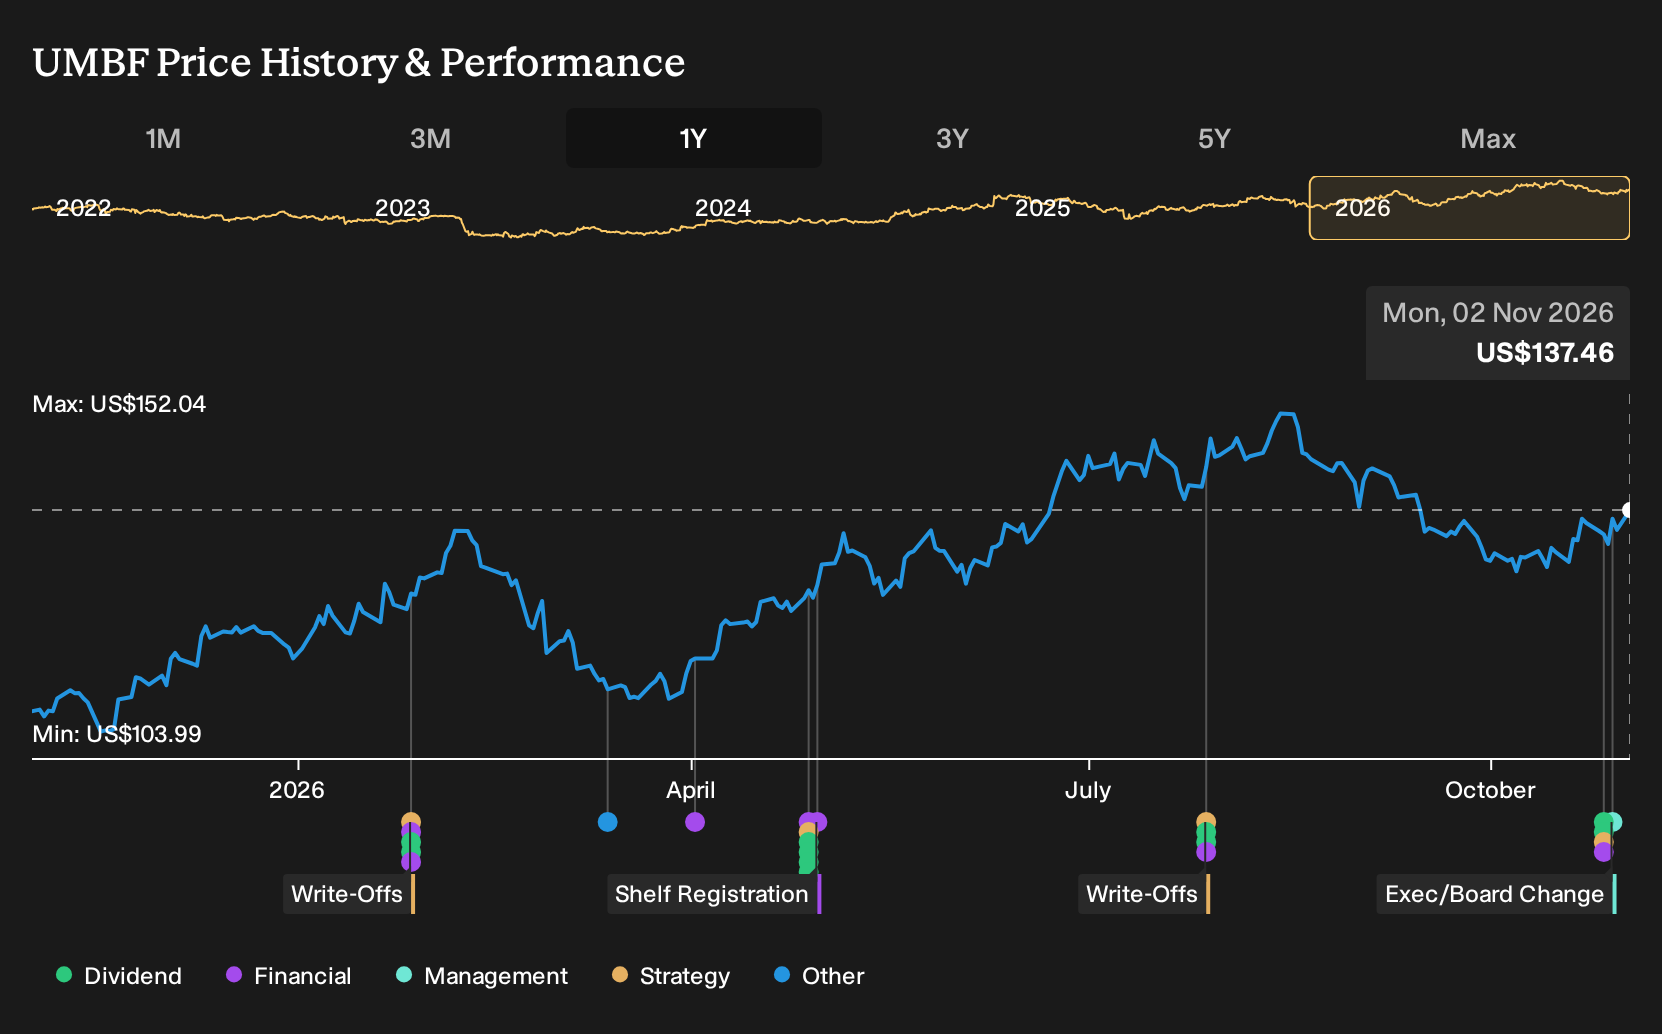
- UMB Financial reported third quarter 2026 net interest income of US$540.01 million and net income of US$278.09 million, with dividend declarations on both common and Series B 7.75% preferred stock and a decision for Chief Risk Officer Shannon A. Johnson to focus solely on the corporate risk function after stepping away from the Chief Administrative Officer title.
- This combination of stronger reported earnings metrics, continued common and preferred dividend payments, and a clearer risk governance structure provides investors with more concrete data points to assess UMB Financial’s ability to balance lending activity, fee businesses, capital return and risk management execution.
- We will look at how UMB Financial’s investment narrative is shaped by stronger reported earnings that supported an analyst rating upgrade.
UMB Financial Investment Narrative Recap
For UMB Financial, the core belief is that the bank can keep turning a mix of commercial lending and institutional fee businesses into consistent earnings, even as temporary purchase accounting accretion fades. The recent third quarter showed US$540.01 million in net interest income and US$278.09 million in net income, which gives you current proof of earnings power rather than just a story.
The key near term swing factor is whether organic activity in loans and institutional services stays solid as that accretion steps down. The biggest risk is that those high growth engines normalise or become choppier, which could blunt operating leverage. The latest results and credit costs, including US$14.00 million of net charge offs, do not materially change that equation.
The dividend declarations on both common and Series B 7.75% preferred stock matter most here. A US$0.50 common dividend and US$0.484375 per preferred depositary share, both payable in early January 2027, indicate that UMB Financial is running the business with enough capital flexibility to keep returning cash while funding loan growth and fee driven projects.
For you as an income focused holder, that payout track record intersects directly with the main catalyst and the main risk. If organic earnings from commercial banking and institutional services comfortably cover those dividends as purchase accounting fades, the story appears resilient. If growth cools or fee flows soften, the board might have less room to juggle expansion, risk appetite and ongoing distributions at the current level.
What The UMB Financial Forecasts Assume
UMB Financial's analyst playbook leans heavily on a clear set of numerical targets rather than vague optimism. The current consensus builds around earnings today of US$917.3 million and a path to forecast earnings of US$1.2 billion by 2029, supported by expected annual revenue expansion of 7.7% and a modest lift in profit margins from 32.6% to 34.2% over roughly three years.
On that math, the step up from US$917.3 million of earnings to US$1.2 billion implies an increase of about US$282.7 million. That is the earnings gap analysts are effectively asking you to underwrite when you look at UMB Financial as an income oriented bank stock with capital return ambitions.
UMB Financial's narrative projects US$3.5 billion revenue and US$1.2 billion earnings by 2029. This assumes 7.7% yearly revenue growth and an earnings increase of about US$282.7 million from US$917.3 million.
Uncover why UMB Financial's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for UMB Financial from 2 members of the Simply Wall St Community range from US$163.13 to US$241.76, so you are looking at a wide band of expectations. Set those crowdsourced views against the recent dividend affirmations and the sharpened Chief Risk Officer focus, and you get different angles on how future execution could reshape the story. Explore the full set of opinions before deciding where you sit.
Explore another UMB Financial fair value estimate, including one that suggests as much as 76% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your UMB Financial research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UMB Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMB Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond UMB Financial?
Once you have formed a view on UMB Financial, it can help to compare its income profile and risk balance with a wider watchlist of potential holdings. The Simply Wall St Screener lets you filter for cash generation, balance sheet quality and dividend reliability so you can build a shortlist that matches your goals rather than relying on headlines.
- If you want potential mispricing with quality still front and center, start with a curated set of 34 high quality undervalued stocks that pair fundamental strength with more modest expectations baked into current prices.
- For readers who care most about durable payouts, use the screener highlighting 4 dividend fortresses to compare yield, coverage and balance sheet support across income oriented companies.
- When capital preservation comes first, filter for resilience using the screener focused on 29 resilient stocks with low risk scores so you can prioritise businesses with steadier risk profiles before you commit capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com