


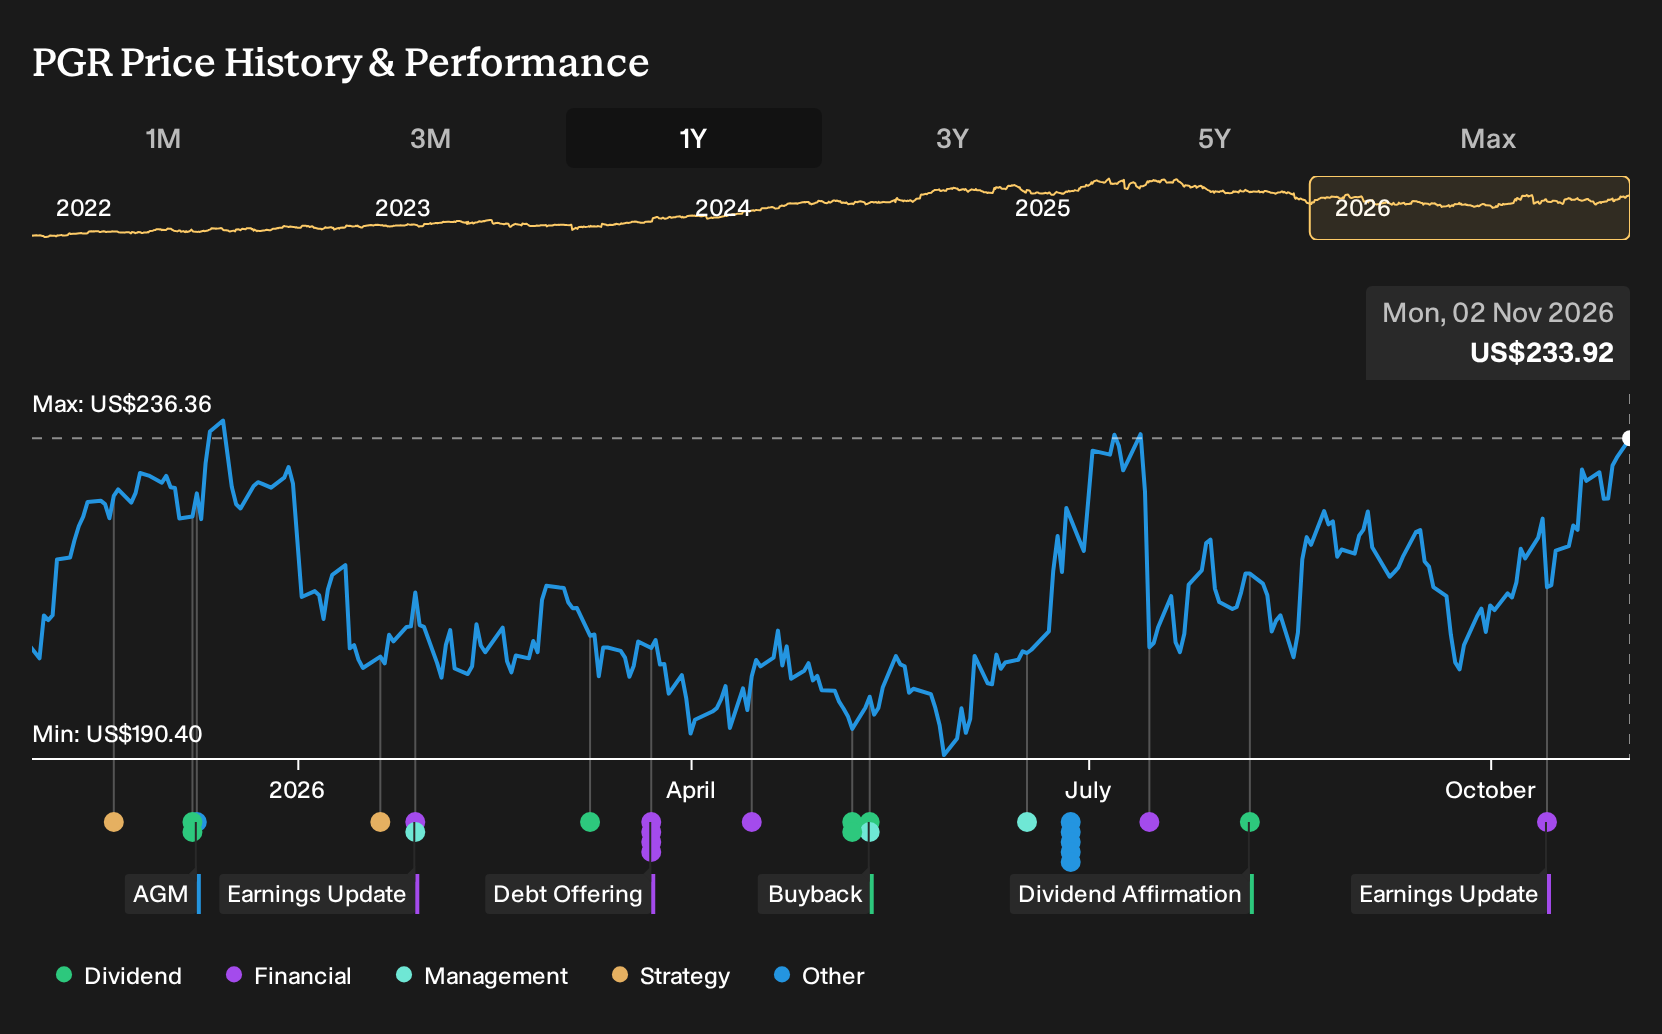
If you had backed Progressive on 2 November 2025, you were stepping into a live argument about whether its data driven underwriting could outrun rising claim costs, climate risk and the threat of autonomous vehicles shrinking the personal auto pool. Holding Progressive over the past year would have returned 22.3%, including dividends. If that decision were in front of you again today, how much weight would you put on those early worries about profit pressure versus scale advantages?
The easy part of this move is behind Progressive. Zero in on 34 high quality undervalued stocks for companies trading below our estimates.
What Progressive Investors Were Really Arguing About
The shares cost US$206 at the start of the period, and you had to decide whether Progressive’s data advantage could outweigh worries about claims inflation, regulation and changing mobility.
The bullish story pointed to a Fair Value of US$278, a notional price based on assumptions that revenue could rise 8.2% with profit margins around 9.1%, supported by data analytics, telematics and rapid pricing changes.
The bearish view focused on a Fair Value of US$189, based on concern that autonomous vehicles, climate related losses and tighter rules on data use would erode net margins over time.
What The Results Changed For The Progressive Thesis
The clearest test of the Progressive debate came from Q3 2026, when revenue reached US$23.18b versus US$22.50b a year earlier, while net income slipped to US$2.54b from US$2.62b and net margin eased from 11.6% to 11.0%. That mix of higher sales and slightly weaker profitability cut both ways for the original bullish scale story and the cautious profit pressure case.
The useful takeaway is simple. When weighing a data edge like Progressive’s, keep checking whether margin trends, not just premium growth, line up with any story about durable underwriting strength.
What Progressive's Current Price Already Assumes
Progressive trades at US$234 today, after a 22.3% gain over the past year. The selected Narrative places its Fair Value below that level, arguing that the current quote already bakes in disciplined underwriting and steady capital returns in a softer auto market.
The core question for you is what needs to keep working. A buyer at today’s price has to judge whether slower premium growth, thinner margins and higher advertising can still support the profitability that current expectations imply.
"The main requirement for success is for Progressive to convert its larger base of personal auto customers into more bundled Robinsons households while keeping property combined ratios in the mid 70s to low 80s range and catastrophe volatility in check. The numbers imply the share price already reflects Progressive maintaining its current underwriting discipline and capital return approach in a softer auto market, leaving limited room for disappointment if growth or margins slip."
The price and this Narrative do not agree. → Uncover what this Narrative says Progressive is actually worth
Looking Beyond Progressive's Data Edge
Progressive has shown how sharp pricing and data can reshape personal cover. You could also look at where similar tools are being pushed further.
One large insurer is wiring AI into everyday underwriting, claims handling and customer service. The focus is on controlling expenses while still broadening reach.
It is also pushing digital health and protection products that link cover with prevention and care delivery. That echoes Progressive’s push to deepen relationships across a household.
Expansion into emerging markets and more digital distribution give this group different ways to spread risk. The open question is how that mix adapts if consumer demand shifts or cost savings grow harder to capture.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 21% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com