


- Smurfit Westrock reported Q3 2026 sales of US$8,161 million and net income of US$222 million, with quarterly earnings per share of US$0.42 on both a basic and diluted basis.
- The nine month figures show a similar pattern, with sales of US$23,904 million alongside lower net income and earnings per share than the prior year, which points to cost or mix pressures behind the headline growth.
- The key question is how Smurfit Westrock's investment narrative could be affected by higher sales alongside weaker earnings per share trends.
Smurfit Westrock Investment Narrative Recap
To own Smurfit Westrock, you need to be comfortable with a simple idea. The thesis rests on the packaging group turning its large integrated footprint, synergy program and contract cleanup work into healthier margins over time, even as freight, energy and regulatory costs keep biting.
The latest quarter supports that tension. Sales for both Q3 and the nine month period were higher than a year earlier, but net income and earnings per share were lower. That keeps the short term focus on whether pricing, mix and synergy gains can offset inflation, and on the risk that weaker profitability limits financial flexibility.
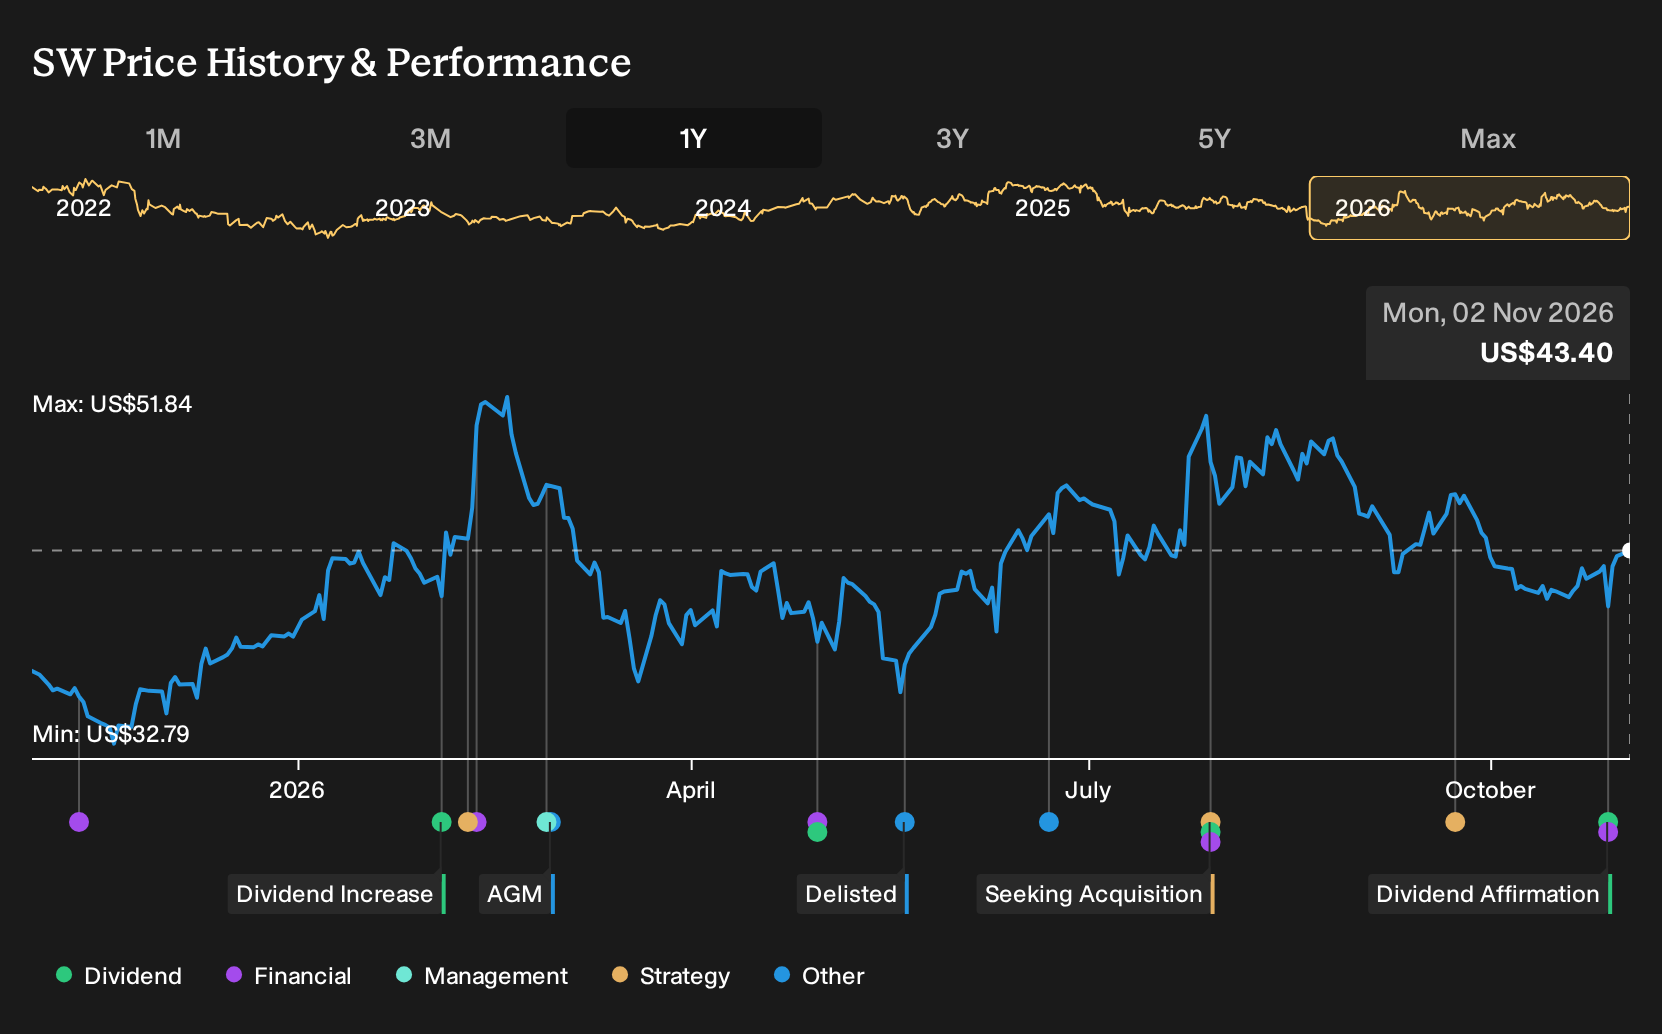
The most relevant update for that debate is the fresh dividend affirmation. Smurfit Westrock's board approved a quarterly payout of US$0.4523 per share, payable on 10 December 2026 to holders on 13 November. That decision sits against commentary that the dividend is not well covered by earnings or free cash flow.
For you as a shareholder, this creates a clear trade off to monitor. A maintained cash return offers income while earnings are under pressure, but it can also heighten sensitivity to freight, energy and interest costs. If operating execution on synergies and pricing gains stalls, the dividend policy and balance sheet strength could quickly become the central catalysts.
Smurfit Westrock's narrative projects US$35.7b revenue and US$3.0b earnings by 2029. This assumes revenue growth of 4.4% per year and an earnings increase of about US$2.5b from US$497.0m today.
Uncover why Smurfit Westrock's fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Smurfit Westrock focuses on asset optimization as the real earnings lever. The most optimistic analysts were modeling about US$37.8b of revenue and US$3.1b of earnings by 2029 before this Q3 update. You can treat those higher margin and EBITDA expectations as one end of the spectrum and explore how this latest earnings and dividend news might shift that story.
Explore 3 other Smurfit Westrock fair value estimates, including one that suggests as much as 155% upside from the current price!
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Smurfit Westrock research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Smurfit Westrock. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Smurfit Westrock's overall financial health at a glance.
Looking for more investment ideas beyond Smurfit Westrock?
Once you have formed a view on Smurfit Westrock, it can help to cross check that thinking against other companies with different balance sheets, dividend profiles and valuation setups. The Simply Wall St Screener lets you quickly filter for stocks that match the type of risk, income and quality mix you prefer.
- If you want income to do more of the heavy lifting, scan for payout opportunities in the 4 dividend fortresses that have already been filtered for higher yields.
- For investors who care most about quality at a sensible entry point, start with the 34 high quality undervalued stocks and focus on companies with stronger cash generation and healthier fundamentals.
- If capital preservation is high on your list, narrow the field using the 29 resilient stocks with low risk scores so you are only comparing stocks that screen with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com