


Diamondback Energy has delivered a strong share price run over the past few years, which puts a sharper spotlight on whether the current valuation still lines up with the profits the business is generating. With the stock now trading near recent highs after an active period of capital returns and investment, the key issue is how firmly its earnings support that price tag.
- Over the past 5 years the stock has returned 113.3%, which puts real pressure on investors to ask whether the current earnings profile can carry that kind of gain.
- Recent updates on production, cost control and infrastructure investments, including exposure to Permian Basin pipeline and power projects, can shape how durable Diamondback Energy's margins and cash generation look over the next few years.
- There is a second opinion on Diamondback Energy worth weighing. See what analysts think Diamondback Energy's shares could be worth.
The issue now is whether Diamondback Energy's current share price is adequately supported by the earnings power that investors are paying for today.
If you want a broader watchlist while you assess whether Diamondback Energy's earnings justify its recent 113.3% five year return, a focused screen of 34 high quality undervalued stocks can be a useful next step.
Has Diamondback Energy Run Too Far on Earnings?
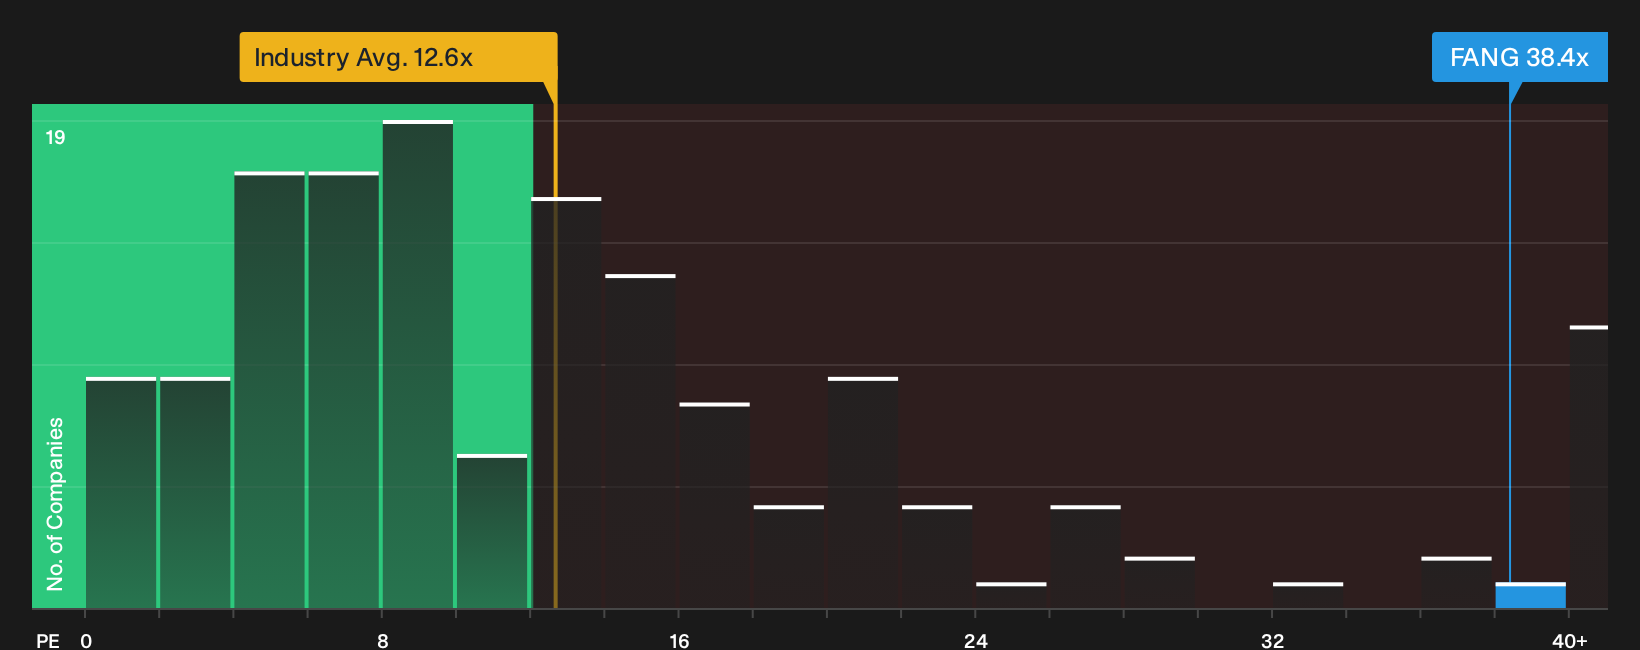
P/E works well for Diamondback Energy because earnings are a key focus for investors in established oil producers. On this yardstick, the stock trades on a P/E of 38.4x, which is far above both the Oil and Gas industry average of 12.6x and the peer group around 14.7x. That kind of gap means buyers today are paying a much higher price for each dollar of recent profit than is typical across the sector.
The fair P/E that would be expected for Diamondback Energy, based on its own fundamentals rather than raw averages, sits meaningfully lower than the current 38.4x. As a result, the shares screen as overvalued on this framework. Despite the strong Q3 2026 update and higher dividend feeding optimism, the present multiple still builds in a rich earnings profile compared with both the tailored fair range and other oil producers, which is worth weighing carefully before leaning on the recent rally as a guide to value. Explore the numbers behind Diamondback Energy's P/E valuation.
The Diamondback Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for Diamondback Energy by spelling out what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than it is today on the screen. Each scenario links its number to a clear view of how Diamondback Energy's future profitability and risks might evolve, which you can revisit as new information emerges on the Community page.
One of the top community narratives on Diamondback Energy: 17% undervalued
"Growing exposure to natural gas linked to power and data centers, including the shovel ready Bryant Ranch project that is expected to take 200 to 250 MMcf/d of gas…"
Discover why this Narrative puts Diamondback Energy at 17% undervalued.
Diamondback Energy’s valuation is only part of the story
Before you lean too heavily on the current multiple or any narrative, it is worth checking the specific risk flags our research has picked up on Diamondback Energy and weighing what they might mean for your thesis. Take a closer look at 4 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com