


Nebius Group has had a volatile run, with strong longer term gains sitting alongside a sharp pullback in recent weeks. That mix now puts the focus squarely on whether the current share price makes sense relative to the revenue the business is generating. For anyone watching AI infrastructure plays, the question is how much of Nebius’s sales story is already baked into the US$141.39 stock price.
- Over the past 5 years the stock has returned 63.5%, which makes the link between Nebius’s sales base and today’s valuation especially important for new money going in.
- The new US$3.5b senior secured loan from Citi can support data center build out and GPU purchases. It also sets clearer expectations for future funding needs and the level of revenue required to service that larger capital structure.
- Your read on Nebius Group is one view; the desks covering it have another. See what analysts think Nebius Group's shares could be worth.
The issue now is whether Nebius’s current market value is adequately supported by its sales power once you set the recent share-price swings alongside its revenue footprint.
If you want another starting point for research alongside Nebius Group, a focused screen of 53 AI infrastructure stocks.
Where Does Nebius Group Sit on Sales?
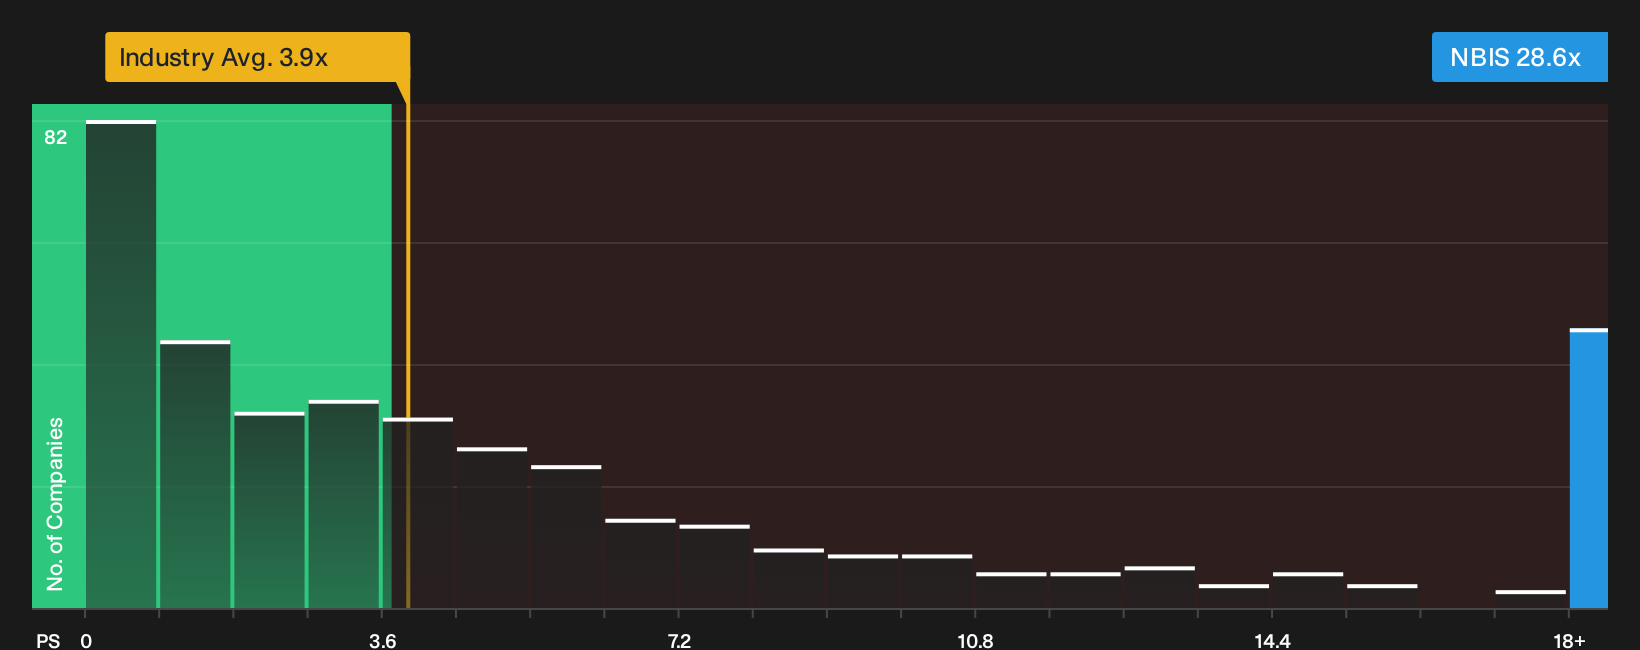
P/S fits Nebius Group because revenue remains the clearest anchor, while earnings metrics like the current 914.0x P/E are hard to interpret. On that lens, the stock trades on a P/S of 28.6x, which is far above the broader software sector at 3.9x and also ahead of a more focused peer group on 8.3x.
The fair-value model, which blends Nebius Group’s growth profile, margins, size and risk into a tailored benchmark, indicates that this rich P/S is roughly in line with what you would expect rather than outright stretched or cheap. Despite the fresh US$3.5b Citi facility raising questions about funding costs and execution risk, the current sales multiple still reflects a valuation that the model treats as broadly about right. Explore the numbers behind Nebius Group's P/S valuation.
The Nebius Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Nebius Group pick up where the valuation puzzle leaves off and explain what future growth, margins and earnings would need to look like for the stock to be worth materially more or materially less than today. Rather than stopping at a single ratio or model output, Narratives set out the underlying assumptions so you can monitor how Nebius Group's actual progress aligns with the future that number implies. All of this is housed on the Community page.
Community views on Nebius Group are split between those who see a powerful AI infrastructure franchise and those who focus on funding and consolidation risk.
Bull case: 50% undervalued
"Nebius leverages rapid AI demand, global expansion, strategic partnerships, advanced technology, and strong funding to drive recurring revenue, margin growth, and long-term profitability…"
Discover why this Narrative puts Nebius Group at 50% undervalued.
Bear case: 30% overvalued
"Bearish analysts expect Nebius Group to remain a high risk story where extreme capital needs, tighter credit and the possibility that many neocloud peers may not stay independent leave the business exposed…"
Explore why this Narrative puts Nebius Group at 30% overvalued.
One last cross check for Nebius Group before you move on
Price ratios and community views tell only part of the story, since broker models sketch out where they think Nebius Group could be a few years from now. This gives you a different benchmark to compare with today. Explore where analysts expect Nebius Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com