


Supernus Pharmaceuticals has delivered a strong 75.7% gain over the past three years. However, recent news around its acquisition by Indivior and a changing index role means the story is no longer just about momentum. The question now is whether the current US$41.92 share price can be squared with what the business is generating in sales.
- The 75.7% return over three years puts real weight on whether Supernus Pharmaceuticals' current valuation can be supported by the scale and quality of its revenue base.
- Recent developments around new products, regulatory exclusivity and a broader combined pipeline can influence how much investors are willing to pay for each dollar of sales, because they may affect future top line durability and pricing power.
- Your read on Supernus Pharmaceuticals is one view; the desks covering it have another. See what analysts think Supernus Pharmaceuticals's shares could be worth.
The issue now is whether Supernus Pharmaceuticals' present market value is justified by its sales when stacked against the Fair Ratio yardstick.
If you want a broader watchlist built around similar questions of what investors are paying for each dollar of sales, a focused screener of 34 high quality undervalued stocks.
Does Supernus Pharmaceuticals Look Undervalued on Sales?
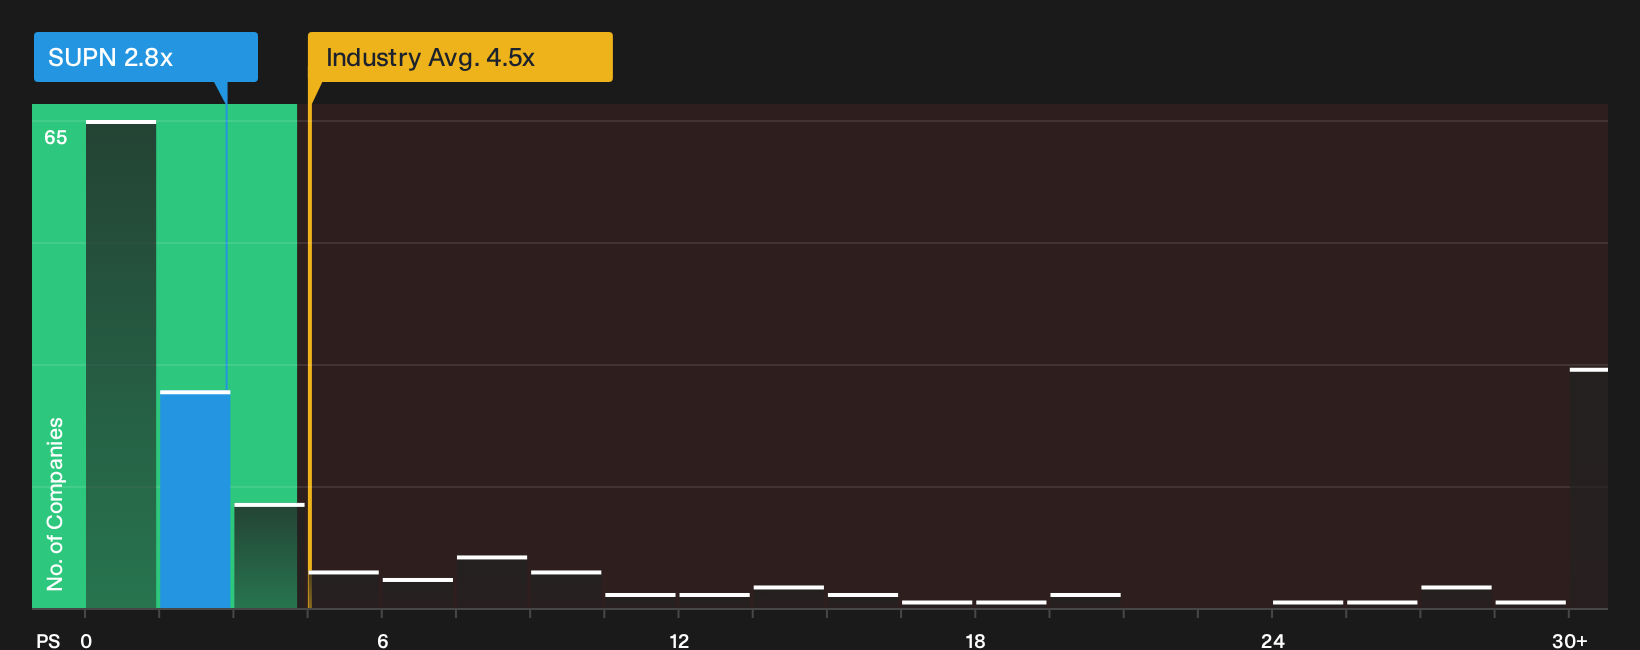
P/S is a useful lens for Supernus Pharmaceuticals because revenue is the cleaner yardstick when earnings and free cash flow can swing around product launches and research spend. On this measure, the stock trades on a P/S of 2.8x, which is below both the broader pharmaceuticals industry on 4.5x and the peer group on 6.3x. The tailored Fair Ratio, which adjusts for Supernus Pharmaceuticals' own growth profile, margins, size and risk, also points to a higher P/S than the current market level, so the shares screen as undervalued on this framework.
Because the Indivior deal ties Supernus Pharmaceuticals into a larger central nervous system portfolio, recent enthusiasm around cost synergies and pipeline breadth has not yet closed that P/S gap implied by the Fair Ratio. For you as a shareholder or potential buyer, the key question is whether the durability and pricing of that combined revenue base justify the market continuing to value each dollar of sales below these benchmarks. Explore the numbers behind Supernus Pharmaceuticals's P/S valuation.
The Supernus Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Supernus Pharmaceuticals valuation puzzle leaves off. They spell out which paths for revenue growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each scenario ties a specific fair value to a clear set of potential catalysts and risks so you can track over time which version of events appears to be taking shape.
One of the top community narratives on Supernus Pharmaceuticals: 32% undervalued
"The main execution priority is that Supernus successfully integrates the Indivior merger while continuing to grow key products such as SUBLOCADE, Qelbree, ZURZUVAE, GOCOVRI and ONAPGO…"
Discover why this Narrative puts Supernus Pharmaceuticals at 32% undervalued.
One more Supernus Pharmaceuticals check that belongs alongside the price tag
Who steers Supernus Pharmaceuticals, how they are rewarded and whether those incentives line up with your priorities can matter as much as any multiple you have just read about. See who runs Supernus Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com