


- Flight Centre Travel Group has shifted capital toward cruise, luxury, Meetings & Events and foreign exchange, while cutting guidance after a business mix move toward lower margin carriers raised questions about profitability.
- The combination of higher value segments and lower margin airline partners leaves Flight Centre balancing growth ambitions against pressure on unit economics and returns.
- This article examines how Flight Centre's investment narrative is tested by the guidance cut tied to lower margin carrier exposure.
Compare Flight Centre Travel Group's recalibrated mix with peers by scanning list of solid balance sheet and fundamentals (12 results) that may pair capital discipline with more resilient unit economics.
Flight Centre Travel Group Investment Narrative Recap
To own Flight Centre Travel Group, you need to believe the shift toward cruise, luxury, Meetings & Events and foreign exchange can offset pressure from lower margin airline partners over time. The near term swing factor is whether productivity tools and higher value leisure products can keep supporting net profit margins while that business mix resets.
The biggest risk right now sits in external shocks and leisure volatility, given past disruption from geopolitical events and periods where Leisure was unprofitable. If conflicts or routing changes hit international travel again, the combination of lower margin air and weaker touring could pressure earnings despite solid total transaction value.
The recent guidance cut linked to lower margin carriers puts more weight on earlier commentary about cost efficiency and automation. Management has already connected tools like Melon, FCM Booking and Sam with a 34% lift in TTV per consultant since 2023 and a 9.5% cost margin. As the business mix shifts, execution on these programs matters even more.
Flight Centre Travel Group has also been reshaping its portfolio, including divesting Cross Hotels and its Pedal Group stake and completing a A$200m buyback that retired just over 7% of shares. With another buyback of up to A$200m flagged and cash released from sales, how that capital is deployed now interacts directly with the margin story and any future guidance moves.
Flight Centre Travel Group's current analyst story points to A$3.3b in revenue and A$266.8m in earnings by 2029, based on a 5.4% yearly revenue growth rate and a lift in profit from A$149.2m today, which means earnings would need to rise by about A$117.6m to reach the consensus target.
Discover how Flight Centre Travel Group's fair value indicates a 17% potential upside to its current price, which could narrow more quickly than some investors anticipate.
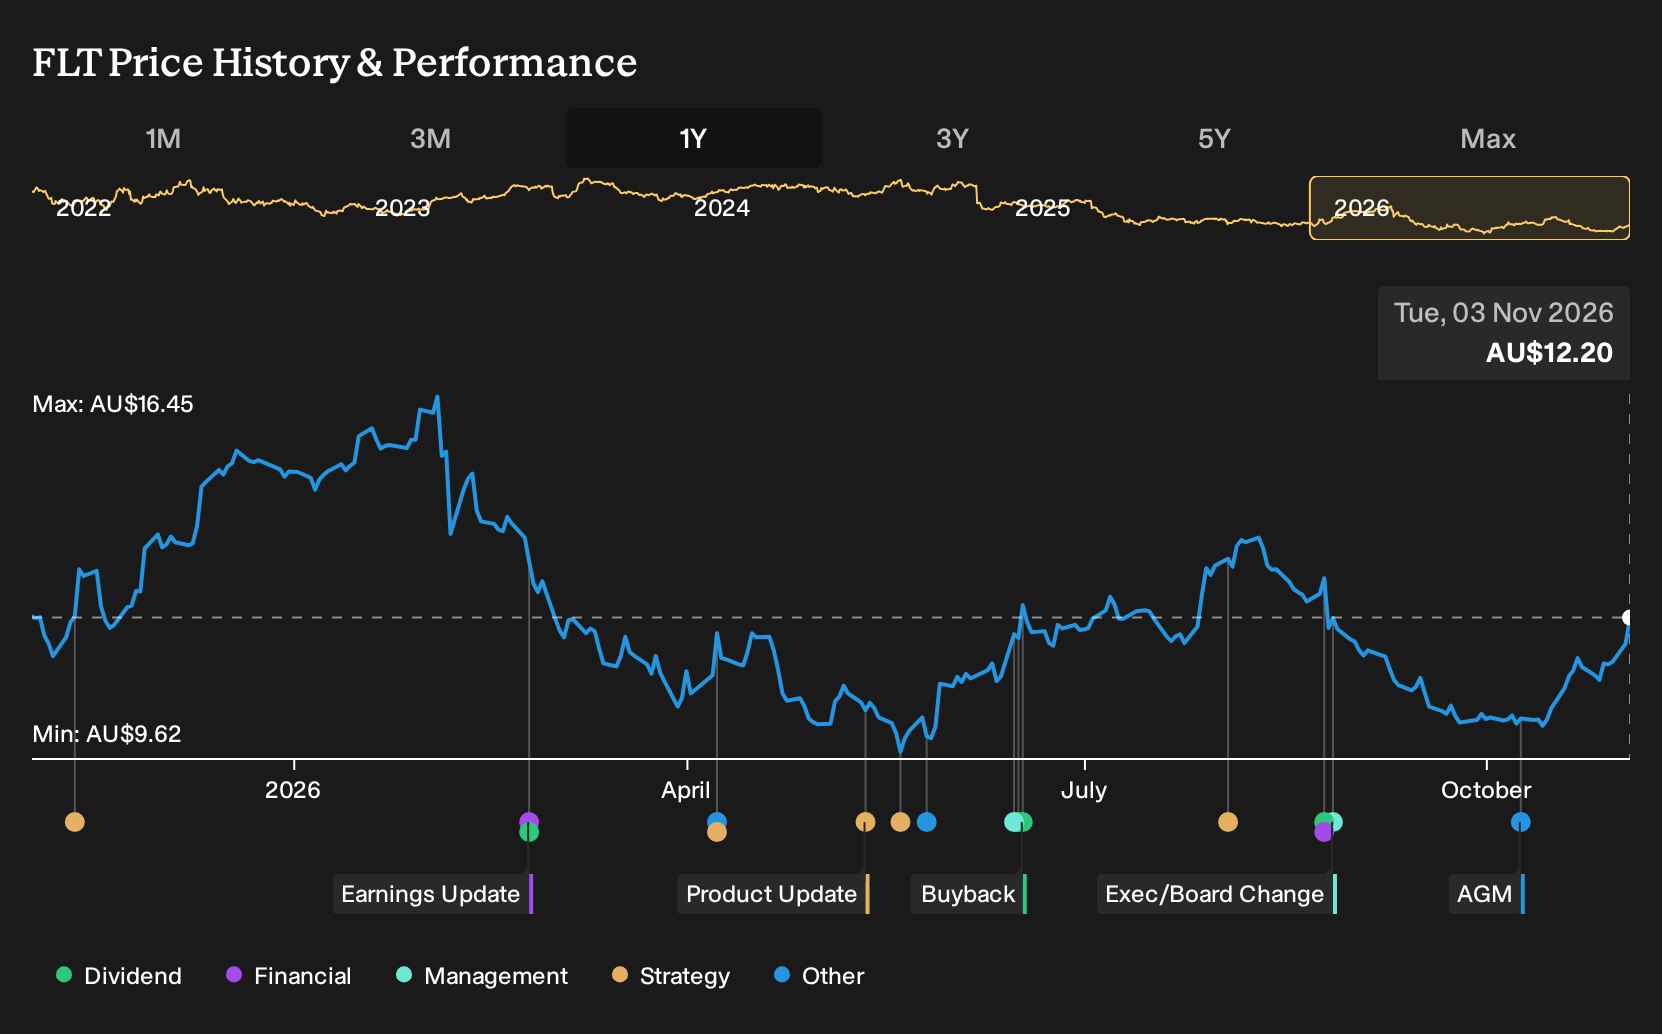
Exploring Other Perspectives
For Flight Centre Travel Group, the alternate, more optimistic angle leans on capital returns as the key catalyst. The most bullish analysts were banking on revenue of about A$3.8b and earnings of A$354.0m by 2029, well above consensus. That tells you opinions already span a wide range and may shift again after this guidance update.
Explore 3 other Flight Centre Travel Group fair value estimates, including one that suggests as much as 126% potential upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Flight Centre Travel Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Flight Centre Travel Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flight Centre Travel Group's overall financial health at a glance.
Looking for more investment ideas beyond Flight Centre Travel Group?
Once you have a view on Flight Centre Travel Group, it can help to broaden the watchlist with other companies that match the kind of quality or risk profile you want in your portfolio.
- If you want potential value combined with financial resilience, scan a curated 3 high quality undervalued stocks that pair attractive valuation metrics with healthier balance sheets and cash flows.
- For investors who care most about capital strength and fundamentals, filter opportunities using a list of solid balance sheet and fundamentals (12 results) so you can focus on companies that may better handle shocks.
- If you are hunting for less followed opportunities, widen the search with a 14 high quality undiscovered gems that surface quality businesses which are not yet widely tracked.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com