


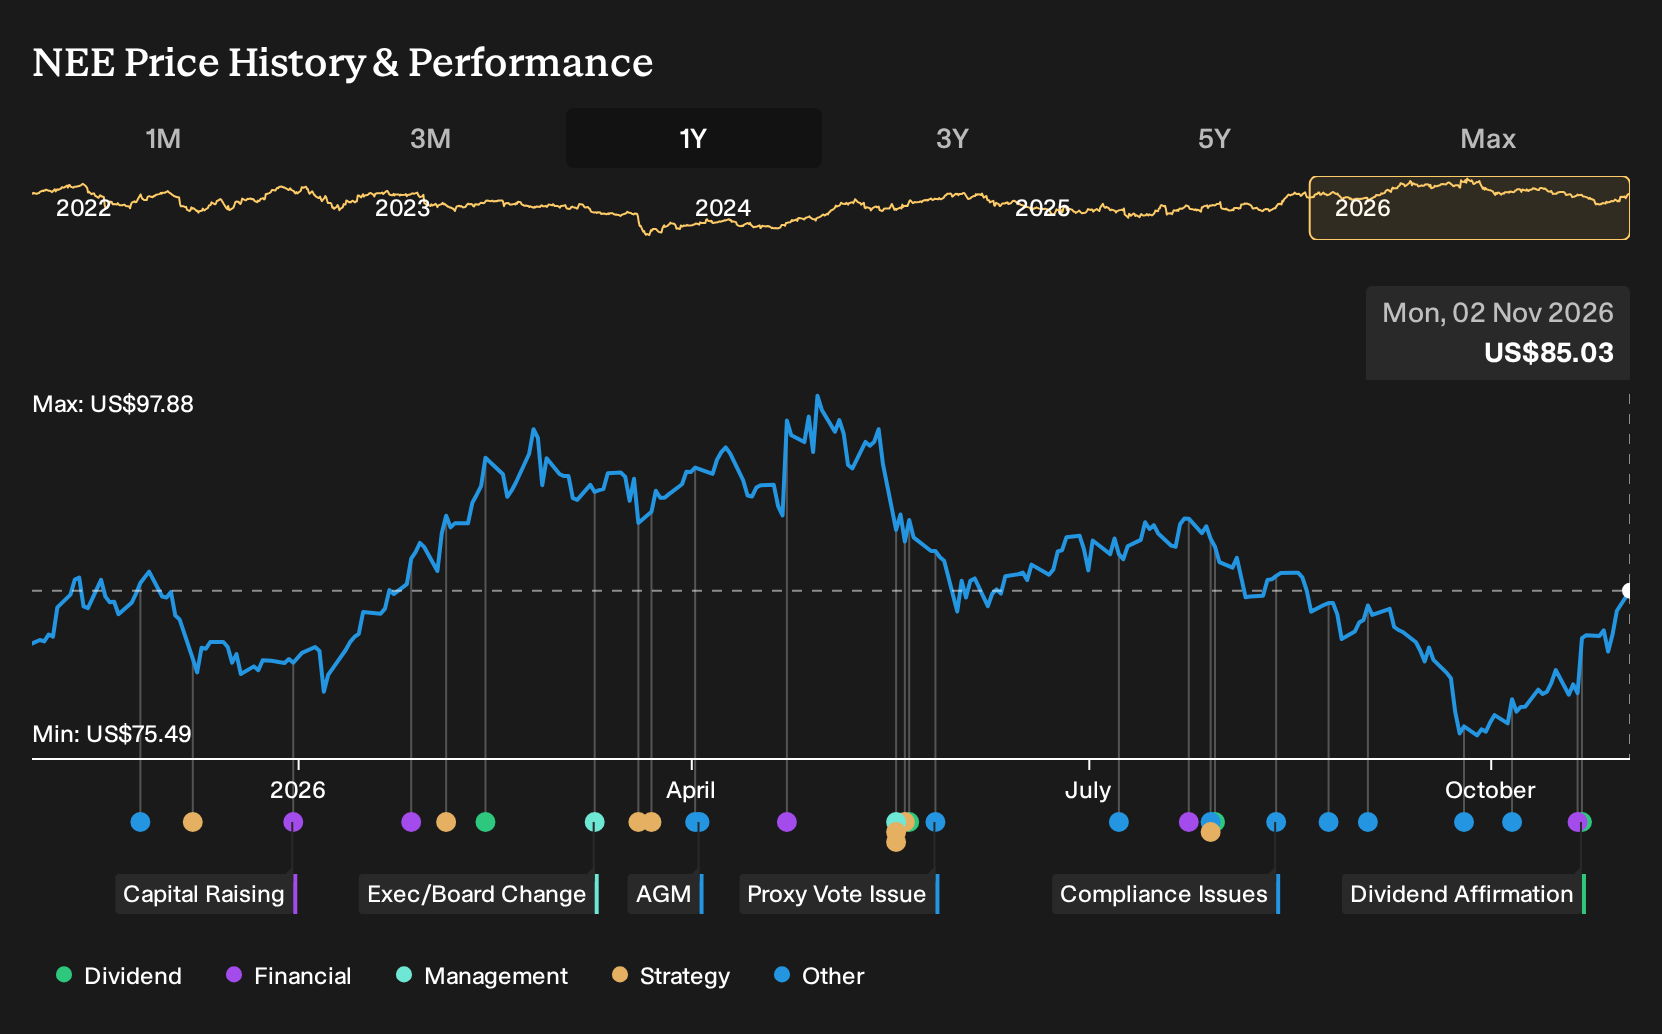
- NextEra Energy reported third quarter 2026 sales of US$8,090 million and net income of US$4,775 million, with basic EPS from continuing operations of US$2.29. The board affirmed a regular quarterly dividend of US$0.6232 per share paid in December 2026.
- The combination of higher year on year earnings and the continued cash return through the quarterly dividend reflects a business that is currently generating substantial profit while still committing capital to shareholders.
- We will now look at how NextEra Energy's stronger quarterly earnings influence the broader investment narrative that investors rely on.
NextEra Energy Investment Narrative Recap
For a shareholder in NextEra Energy, the core belief is that a large regulated utility and renewables platform can keep turning electricity demand, especially from data centers, into durable earnings and cash generation. The latest quarterly results back up that earnings story in the short run. The key near term swing factor remains execution on large load projects while keeping reliability and customer bills on track.
The biggest operational risk still sits around policy and financing. Shifts in tax credits for wind and solar, combined with elevated funding costs, could squeeze project economics just as the capital plan ramps. The new earnings and dividend updates do not remove those pressures but they show the business currently absorbing them.
The most relevant update here is the dividend affirmation at US$0.6232 per share for December 2026. That decision links directly to whether NextEra Energy can balance heavy investment in renewables, nuclear and gas projects with returning cash to investors. It also intersects with concern that free cash flow coverage of the payout is currently thin.
For you as a holder or potential holder, that dividend call highlights a simple trade off. Management is signaling confidence in the earnings base and long term project backlog, while carrying debt that is not well covered by operating cash flow. The catalyst to watch is whether future quarters show enough cash generation from new assets to keep that mix comfortable.
NextEra Energy's current analyst narrative links forecast revenues of US$40.8b and projected earnings of US$10.8b in 2029 to an assumed 12.3% yearly top line expansion, while earnings are expected to decline by US$0.8b from US$11.6b today over that same period.
Uncover why NextEra Energy's fair value indicates an 11% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One bullish twist in the alternate NextEra Energy story centers on large data center hubs. The most optimistic analysts were penciling in revenue of about US$45.9b and earnings of roughly US$10.6b by 2029, before this earnings beat and dividend affirmation. You can treat those projections as one aggressive lens and then compare them with more cautious views.
Explore 7 other NextEra Energy fair value estimates, including one that suggests as much as 29% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NextEra Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NextEra Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NextEra Energy's overall financial health at a glance.
Looking for more investment ideas beyond NextEra Energy?
If the story around NextEra Energy has sharpened your investment thinking, it can be useful to compare it with other businesses that pass clear, rules based filters on quality, value, income or balance sheet strength.
- For investors who care most about resilience and capital preservation, you could start with companies screened for lower risk profiles through the 29 resilient stocks with low risk scores.
- If reliable income sits at the top of your checklist, you might review higher yielding payers that clear strict payout and coverage filters using the 4 dividend fortresses.
- To widen your watchlist with under the radar opportunities that still have solid fundamentals, you can scan a curated 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com