


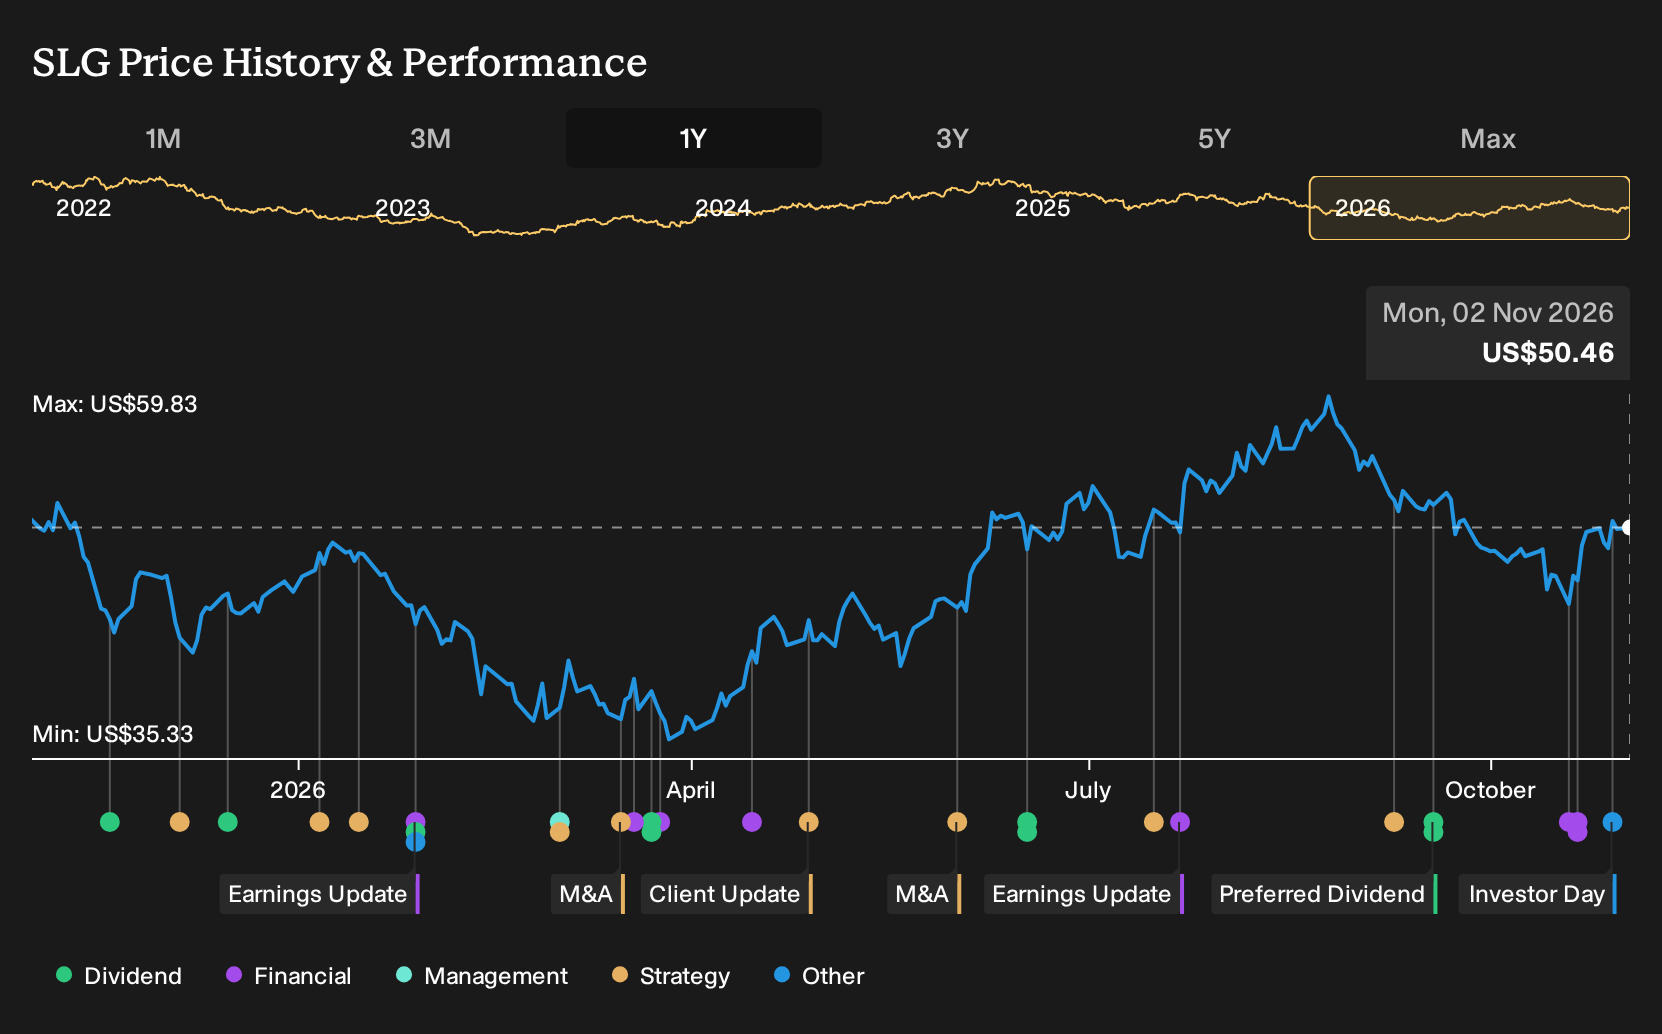
- SL Green Realty reported third quarter 2026 revenue of US$273.03 million and net income of US$78.19 million, with earnings per share from continuing operations of US$1.01, and also updated nine month results that included a reported net loss of US$20.78 million.
- The real estate investment trust raised its 2026 net income guidance to a range of US$0.40 to US$0.60 per share, which indicates that management is aligning expectations with the recent quarterly profitability while full year results still reflect earlier losses.
- This article examines how SL Green Realty's raised full year earnings guidance may influence the investment narrative built around Manhattan office demand.
See how SL Green Realty compares with other real estate opportunities by reviewing our hand picked list of 34 high quality undervalued stocks that feature stronger balance sheets and attractive fundamentals.
SL Green Realty Investment Narrative Recap
To own SL Green Realty, you need to be comfortable with a Manhattan office story that still leans heavily on premium assets, leasing traction and capital recycling to offset pressure from interest costs and lumpy investment gains. The recent profitable quarter and higher full year earnings guidance tighten the short term focus on whether that profitability can be repeated without relying too much on one off transactions.
The biggest near term swing factor remains leasing and occupancy in a market where remote and hybrid work are still a structural question. The key risk is that high interest expenses and refinancing needs meet slower than expected asset sales or weaker lease rollovers, which would keep earnings volatile even as individual quarters, like this one, look strong on paper.
The raised 2026 net income guidance to US$0.40 to US$0.60 per share sits at the center of this earnings update. It indicates that management now expects the year to end with a modest profit despite a reported net loss of US$20.78 million over the first nine months, helped by a strong third quarter.
That new range makes the guidance itself a short term catalyst. Investors will likely watch how recurring rental income, interest costs and any complex investment gains line up with that target, especially given analyst expectations that SL Green Realty may remain unprofitable over the next few years and that interest payments are not well covered by current earnings.
SL Green Realty's narrative projects US$674.8 million revenue and US$39.0 million earnings by 2029. This assumes revenue decreases 12.2% per year and earnings move from a loss of US$192.1 million today to a profit of US$39.0 million, a swing of about US$231 million.
Uncover why SL Green Realty's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a very different take on SL Green Realty, some of the most optimistic analysts lean hard into the fee income story. Before this earnings report, they were modeling 2029 revenue around US$697.7 million and earnings of about US$79.0 million, while others saw earnings closer to a US$292.1 million loss. That spread shows how wide opinions can run, and it illustrates why it can help to compare several narratives before deciding what this new guidance means for you.
Explore 2 other SL Green Realty fair value estimates, including one that suggests potential upside of as much as 51% from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SL Green Realty research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SL Green Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SL Green Realty's overall financial health at a glance.
Looking for more investment ideas beyond SL Green Realty?
If this SL Green Realty earnings story has sharpened how you think about risk, balance sheets and income potential, you can use that same lens across a broader watchlist with the Simply Wall St Screener.
- For investors who want income to do more of the heavy lifting, you can scan a curated universe of higher yield opportunities through 4 dividend fortresses that may appeal if you value regular cash returns.
- If capital preservation is your priority, you can narrow the field to sturdier businesses by reviewing a 29 resilient stocks with low risk scores that scores well on volatility and fundamental risk checks.
- To widen your opportunity set beyond widely followed tickers, you can look across a 19 high quality undiscovered gems that combines stronger balance sheets with under-the-radar fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com