


Iron Mountain (IRM) is back in focus as investors position ahead of its third quarter 2026 earnings on November 5, with attention on revenue, AFFO, data centers, and asset lifecycle management.
Iron Mountain’s share price has climbed strongly year to date, with a 38.37% share price return to US$115.18. However, the 90 day share price return has slipped 8.23%, hinting that momentum has cooled a little ahead of earnings, following a very strong 3 year total shareholder return of 110.40% and 5 year total shareholder return of 195.52%.
Scan beyond Iron Mountain and line up other income and infrastructure plays using our hand picked 4 dividend fortresses as you think about where this earnings story fits in your portfolio.
The recent pullback after a strong run raises a simple question for Iron Mountain investors. Is the price now tracking business fundamentals, or is it reflecting a mood swing in sentiment that the valuation section can help unpack?
Most Popular Narrative: 20% Undervalued
On the most widely followed view, Iron Mountain is worth about $144.91 a share, compared with the recent $115.18 close. This sets a clear gap between price and that fair value estimate, while hinging largely on how newer growth engines scale over time.
Use of cash flow from the physical records management business, which management describes as highly cash generative with stable to slightly rising volumes and consistent pricing, together with net lease adjusted leverage of about 4.8x and a US$1.5b senior notes issue maturing in 2035, underpins continued funding of growth projects in data centers, ALM and digital without relying on equity issuance. This can support future AFFO per share and dividend capacity.
See why 48 investors see Iron Mountain as 21% undervalued.
Result: Fair Value of $144.91 (UNDERVALUED)
Still, the Iron Mountain story can unravel if power constraints slow data center build outs, or if higher funding costs bite into cash generation and limit flexibility.
Find out about the key risks to this Iron Mountain narrative.
Another View: Iron Mountain Looks Expensive On Earnings
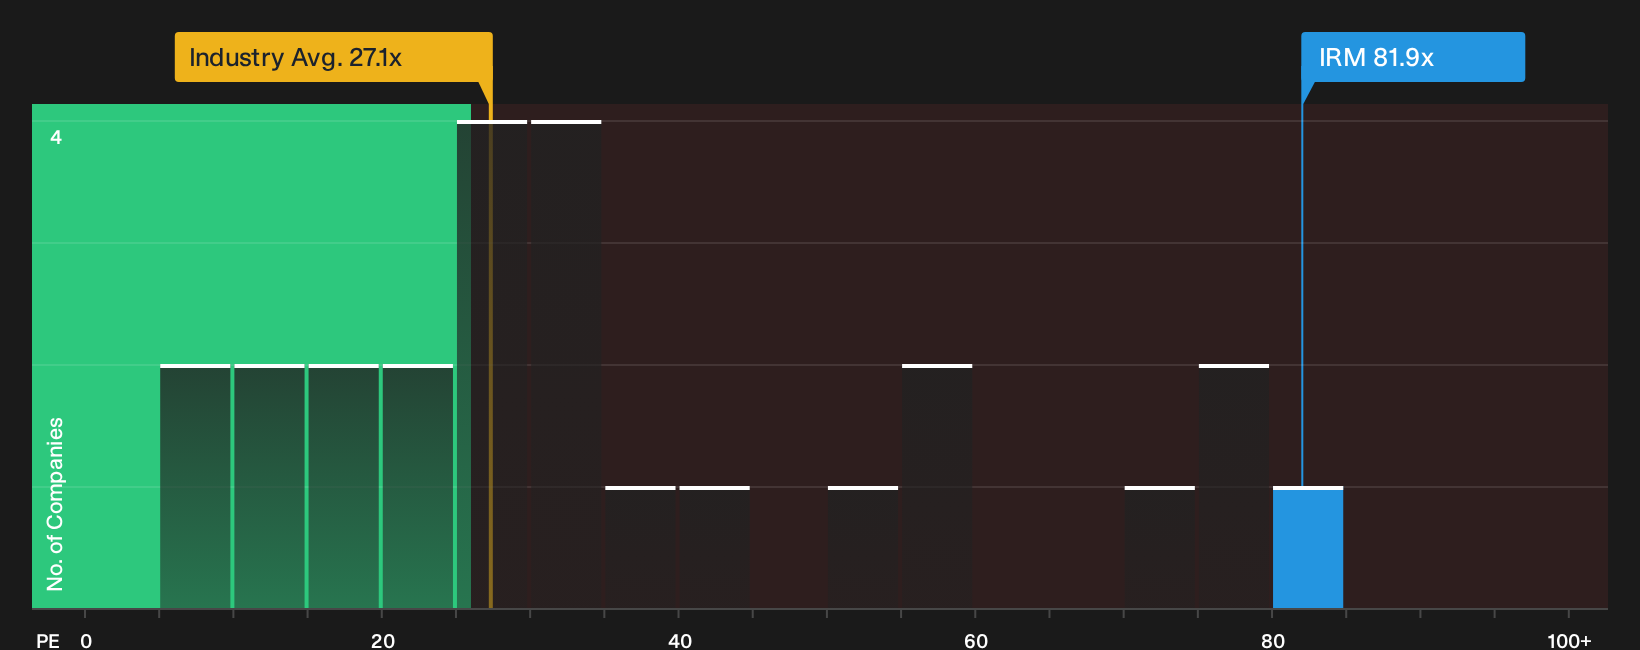
Switch lenses from fair value to the simple question of what you pay for each dollar of Iron Mountain earnings. On a P/E of 81.9x versus a North American Specialized REITs average of 27.1x and a fair ratio of 41.3x, the stock carries a heavy valuation premium that could amplify any disappointment.
That gap suggests plenty of optimism is already in the price. The real issue is whether you see that as upside optionality or downside risk if expectations reset. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Iron Mountain often come down to how you weigh its opportunities against the potential setbacks. Act quickly and review the full breakdown of 4 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Iron Mountain?
Do not stop your research with Iron Mountain. Broaden your watchlist using focused screeners that surface specific types of opportunities you might otherwise miss.
- Target resilience first by scanning companies on a 29 resilient stocks with low risk scores that may offer steadier profiles when volatility tests your convictions.
- Hunt for quality at a discount through a 34 high quality undervalued stocks that highlights businesses where fundamentals and current pricing look out of sync.
- Spot potential early-stage opportunities using a 8 elite penny stocks with strong financials that concentrates on smaller stocks with room for different return profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com