


Why Centerra Gold Is Back In Focus
Centerra Gold (TSX:CG) is back on investors' radar after its latest quarterly update combined higher sales with lower net income, a fresh dividend declaration, reiterated production guidance, and progress on its share buyback program.
The latest quarter, dividend affirmation, reiterated guidance and ongoing buybacks are landing against a share price that has climbed sharply over the year, with a 48.2% year to date share price return and a 1 year total shareholder return of 85.21%. Over shorter windows, momentum has cooled, with the 30 day share price return down 6.07% even after a 1 day gain of 1.95%. This suggests that investors are reassessing Centerra Gold as higher sales, lower recent net income and active capital returns all feed into changing expectations about growth potential and risk.
Spot 34 elite gold producer stocks that echo Centerra Gold's mix of active buybacks, dividends, and operational milestones while this part of the sector is being repriced.Centerra Gold now trades well below the average analyst price target, after a powerful 1 year run and a softer recent patch. So where does a reasonable estimate of fair value actually land within that spread?
Most Popular Narrative: 14% Undervalued
On the most followed view, Centerra Gold’s fair value of CA$33.61 sits above the last close at CA$28.78. This raises the question of what the market is really paying for in the current price.
The current valuation implies that the market is largely pricing Centerra Gold on Mount Milligan alone, with limited value ascribed to Öksüt, the growth pipeline, and the molybdenum platform. This aligns with a narrative that emphasizes a positive view on the shares based on perceived undervaluation.
See why 19 investors see Centerra Gold as 14% undervalued.
Result: Fair Value of CA$33.61 (UNDERVALUED)
Still, the Centerra Gold story leans on analysts expecting revenue to decline 8.4% a year and margins to narrow. Any miss there could quickly challenge the undervaluation case.
Find out about the key risks to this Centerra Gold narrative.
Another View: SWS DCF Flags A Very Different Fair Value
There is a big gap between the CA$33.61 fair value used in the Centerra Gold narrative and the Simply Wall St DCF model, which estimates future cash flow value at about CA$14 per share. That implies the stock is trading well above this DCF output, so which yardstick should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
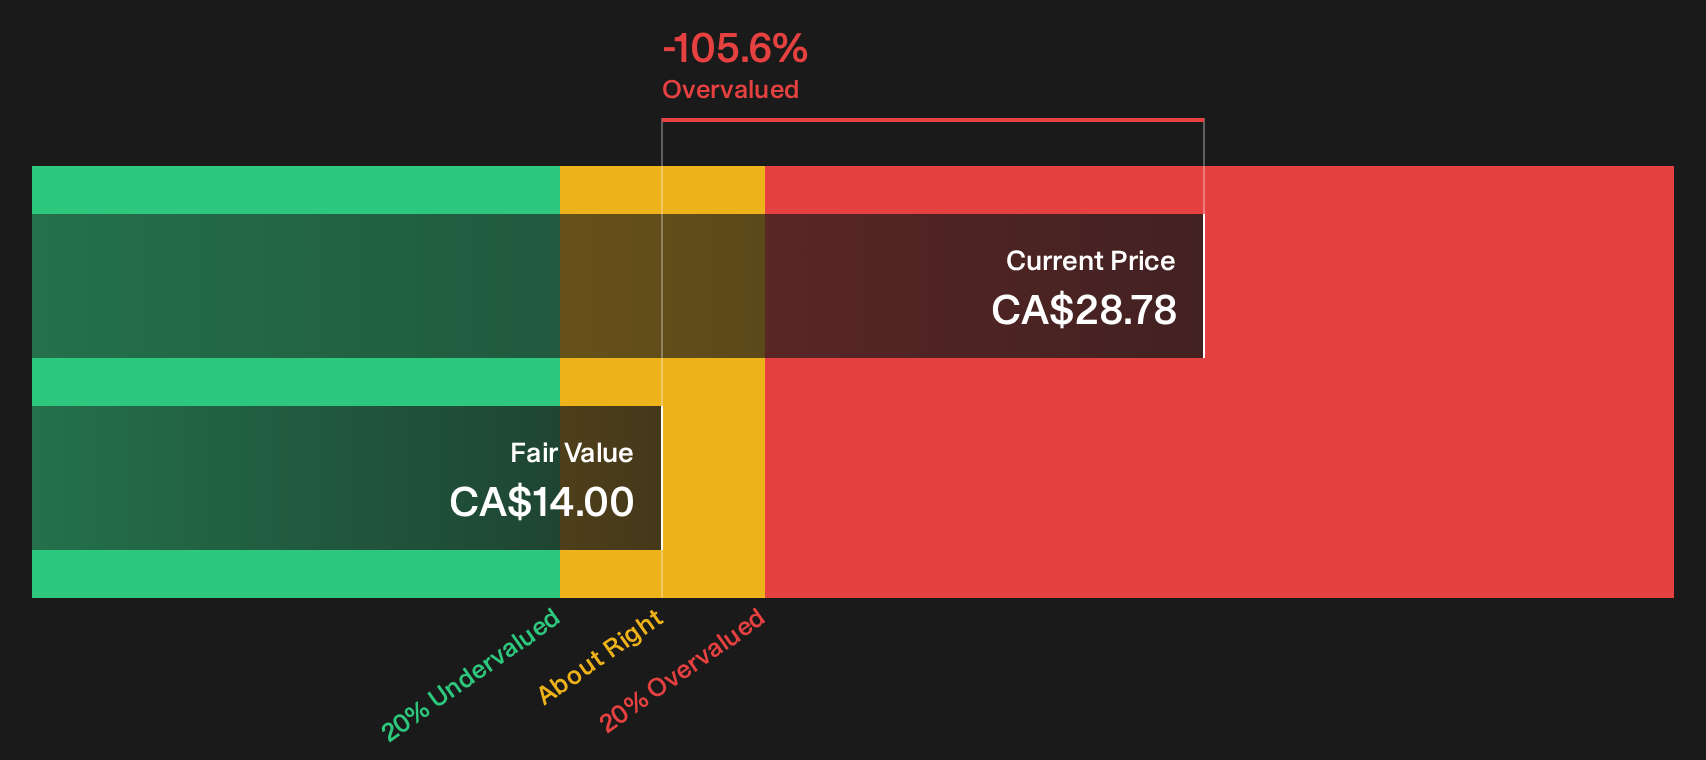
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Centerra Gold for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Centerra Gold's valuation and outlook can be hard to weigh, so move fast, review the data, and pressure test the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Centerra Gold?
Do not stop at one opportunity. Broaden your watchlist and pressure test your thesis against other stocks that share traits you care about.
- Target robust balance sheets and stronger cushions against shocks by scanning our list of solid balance sheet and fundamentals (6 results).
- Hunt for mispriced quality and compare Centerra Gold with our 5 high quality undervalued stocks that screens for strong fundamentals at compressed valuations.
- Prioritize steady income and see how Centerra Gold sits alongside our 3 dividend fortresses built for investors who want yield backed by substance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com