


Arm Holdings (ARM) has been an underperformer in 2026, but options traders believe its upcoming earnings will only add to the pressure on its stock price. Consensus is for ARM to record $0.22 in earnings per share (EPS) for its fiscal Q2 on Nov. 4. That would represent about a 47% increase on a year-over-year basis.
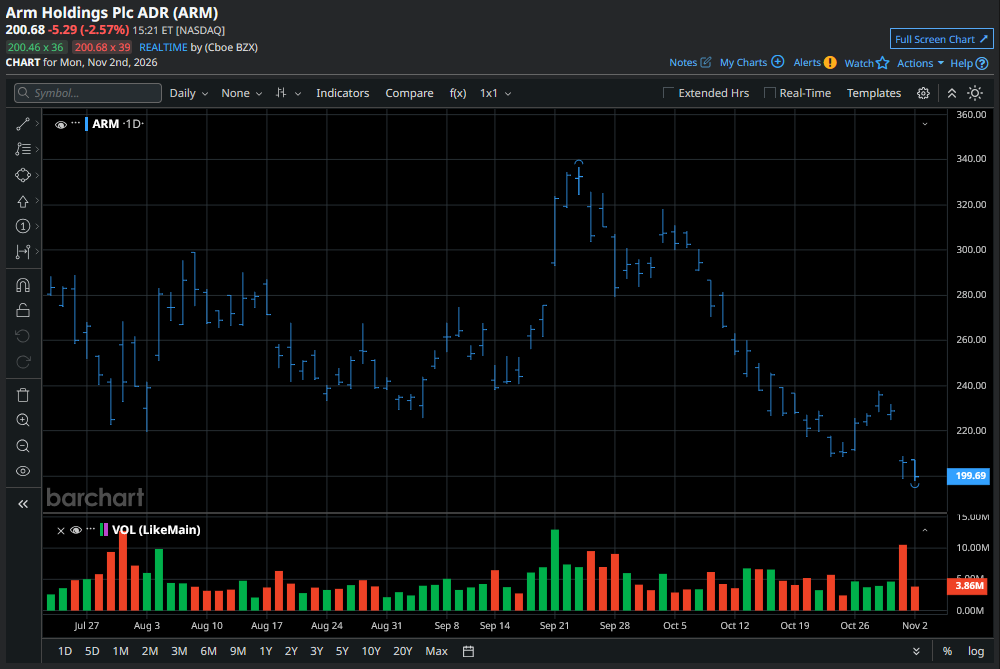
Heading into the quarterly print, ARM stock is trading at less than half its year-to-date high set in mid-June.
Where Options Data Suggests ARM Stock Is Headed
The derivatives market is not entirely convinced that a 47% year-on-year growth would be enough to revitalize ARM shares.
According to Barchart’s options data, the put-to-call ratio on contracts expiring Nov. 13 sits at 1.57x as of this writing, indicating a strong bearish skew. And the lower price on those options contracts is set at about $176 currently, signaling potential for a nearly 12% post-earnings decline through the end of next week.
The technical setup reinforces this bearish sentiment. Arm Holdings currently sits firmly below its key moving averages (MAs), with an RSI in the early 30s pointing to intense selling pressure that may drive it lower in the months ahead.
ARM Shares Are Not Inexpensive to Own
Options traders are keeping dovish ahead of ARM’s quarterly release, likely because of valuation concerns. The chip design giant is currently trading at a forward price-to-earnings (P/E) multiple of roughly 200x, which makes it an expensive name to own by any stretch of the imagination.
Revenue visibility adds another risk. Arm's licensing business depends partly on the timing of large contracts, meaning delayed deals can dent quarterly results. With expectations already high, any weakness in the firm’s licensing revenue or a cautious outlook could overshadow earnings growth and give investors another reason to reduce exposure.
ARM has a history of closing both November and December in the red, a seasonal pattern that further dulls its near-term appeal.
How Wall Street Recommends Playing Arm Holdings
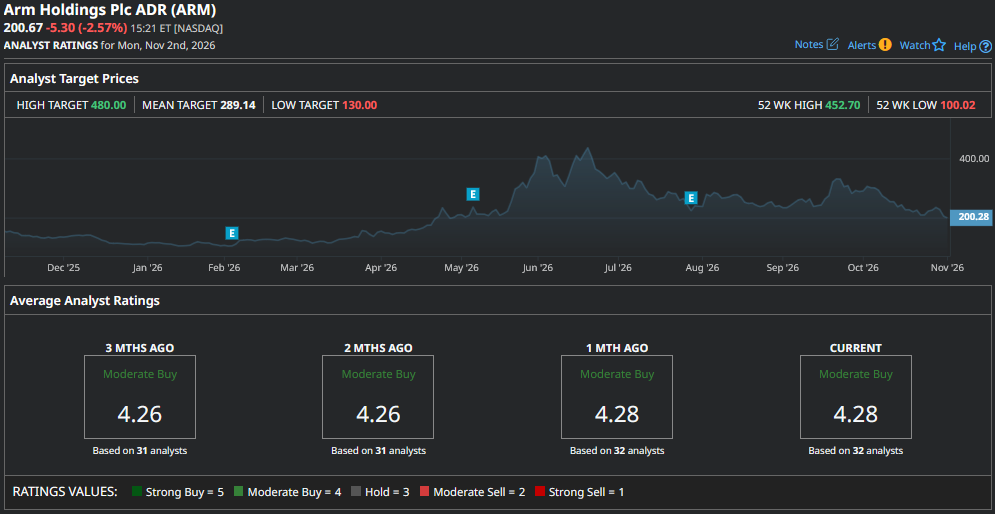
Wall Street analysts nonetheless remain bullish as ever on ARM stock and expect it to extend gains further in 2027.
According to Barchart, the consensus rating on Arm Holdings sits at “Moderate Buy” currently, with the mean price objective of about $289 indicating potential upside of nearly 45% over the next 12 months.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.