


Enova International has logged a powerful multiyear run, and after fresh headlines around both regulatory questions and strong recent earnings, the stock now invites a simple but important check. Are investors paying a price that its current profit base can reasonably support, or has enthusiasm run ahead of what those earnings suggest?
- Over the past 5 years, Enova International has returned about 340.4%, which puts a lot of past success on the line when you ask whether the present valuation still lines up with its profit stream.
- Recent earnings growth alongside sizeable share repurchases can support the case for a richer earnings multiple, since they may tighten the share count and focus more of the business's profit on each remaining share.
- Your read on Enova International is one view; the desks covering it have another. See what analysts think Enova International's shares could be worth.
The issue now is whether the current share price for Enova International is adequately supported by its earnings power when you line it up against the Fair Ratio benchmark.
Alongside testing whether Enova International’s current P/E looks stretched or reasonable against its recent earnings, you can also broaden your watchlist with 34 high quality undervalued stocks.
Does Enova International Look Undervalued on Earnings?
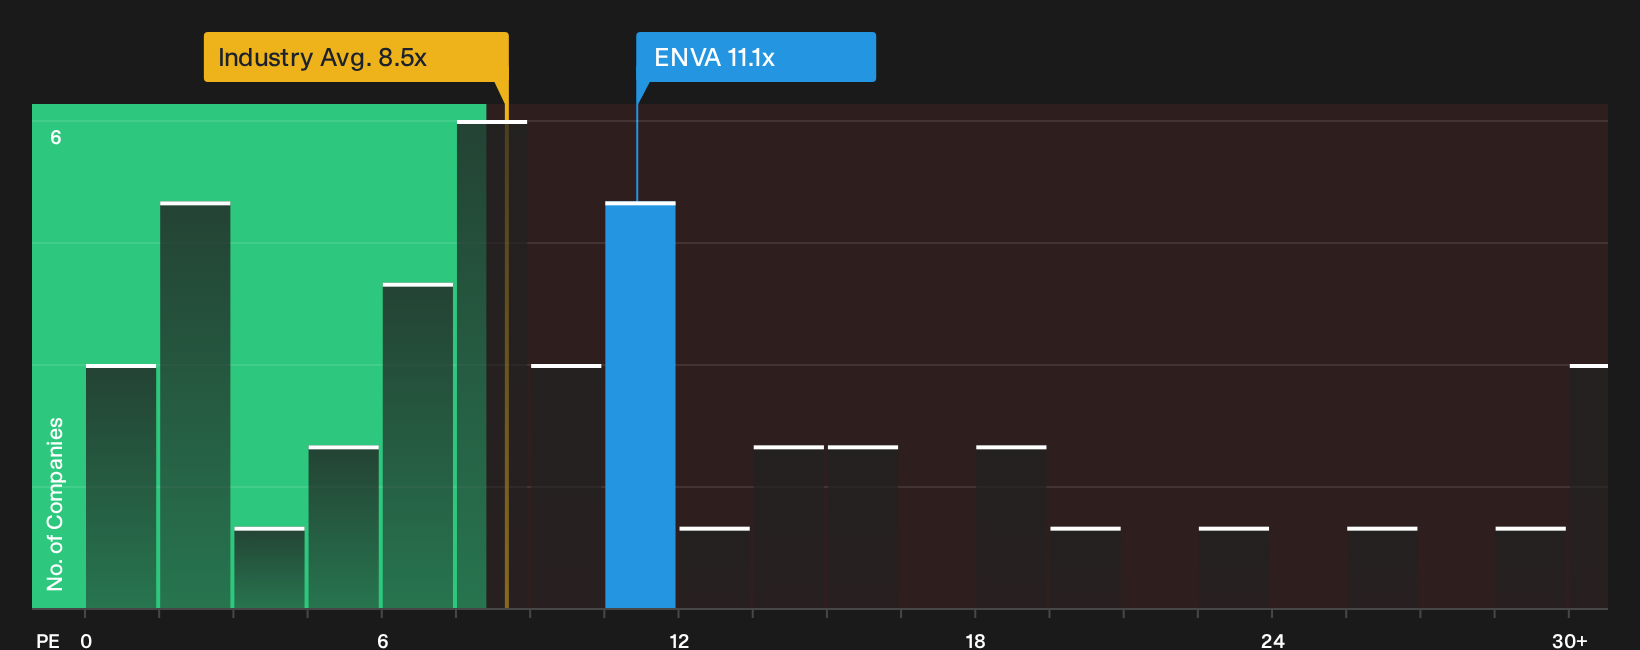
The P/E ratio is a useful starting point for Enova International because earnings sit at the center of how this lender is being judged right now. Based on the latest figures, the stock trades on about 11.1x earnings, which is below both the Consumer Finance industry average of roughly 8.5x and a wider peer group closer to 18.3x. That puts Enova in an unusual spot where it carries a premium to the broader sector but still changes hands at a discount to many direct comparables.
On the Fair Ratio framework, which estimates the P/E you might expect given Enova International’s profitability profile, scale and risk, the current multiple sits on the cheaper side and screens as undervalued. Because the latest investigation into Enova’s withdrawn bank acquisition has raised questions around regulatory risk, this lower P/E may partly reflect a margin of safety investors want before paying up for the strong recent earnings line. For anyone weighing those risks against the recent results and buybacks, the gap between today’s P/E and the Fair Ratio is where the valuation debate really lives. Explore the numbers behind Enova International's P/E valuation.
The Enova International Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St give you a structured way to explain what would need to happen to Enova International's growth, margins and earnings for the current valuation gap to close in either direction, using community views on the business's future that are available on the Community page. Each one treats fair value as a thesis you can revisit later, which lets you see how the story holds up as new information comes through.
One of the top community narratives on Enova International: 27% undervalued
"The key thing that has to go right is that Enova International maintains stable credit performance and reliable capital markets funding…"
Discover why this Narrative puts Enova International at 27% undervalued.
The Enova International price is only one piece of the puzzle
Share price and P/E tell you what the market is willing to pay today, but the projected earnings path a few years out can change how you see that entirely. Explore where analysts expect Enova International to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com