


Framery Group Oyj went into its Q3 2026 earnings with the stock at €7.10 and a solid three month gain behind it. The fresh print shows revenue of €53.6m and net income of €9.53m, which keeps profit margins healthy for an office pod manufacturer that relies on pricing and mix, not just unit volumes. Yet the real tug of war for an investor sits between that steady profitability and the longer term question of how much debt and valuation risk is acceptable for the growth story ahead.
Like the earnings profile at Framery Group Oyj but uneasy about the balance between debt, pricing power and what you are paying for that growth story? Check your expectations against a curated set of financially solid peers in our list of solid balance sheet and fundamentals stocks (196 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): €53.63m vs. €53.13m (approximately +0.9%)
- Net Income (Q3 2026 vs. Q3 2025): €9.53m vs. €6.45m (approximately +47.9%)
- Basic EPS (Q3 2026 vs. Q3 2025): €0.12 vs. €0.08 (approximately +50.0%)
- Adjusted EBIT Margin (Q3 2026 vs. Q3 2025): 23.7% of revenue vs. 23.7% of revenue (stable year on year)
Framery Group’s fastest growth now comes from North America. Ask Charlie what makes Framery Group’s North America growth so strong.
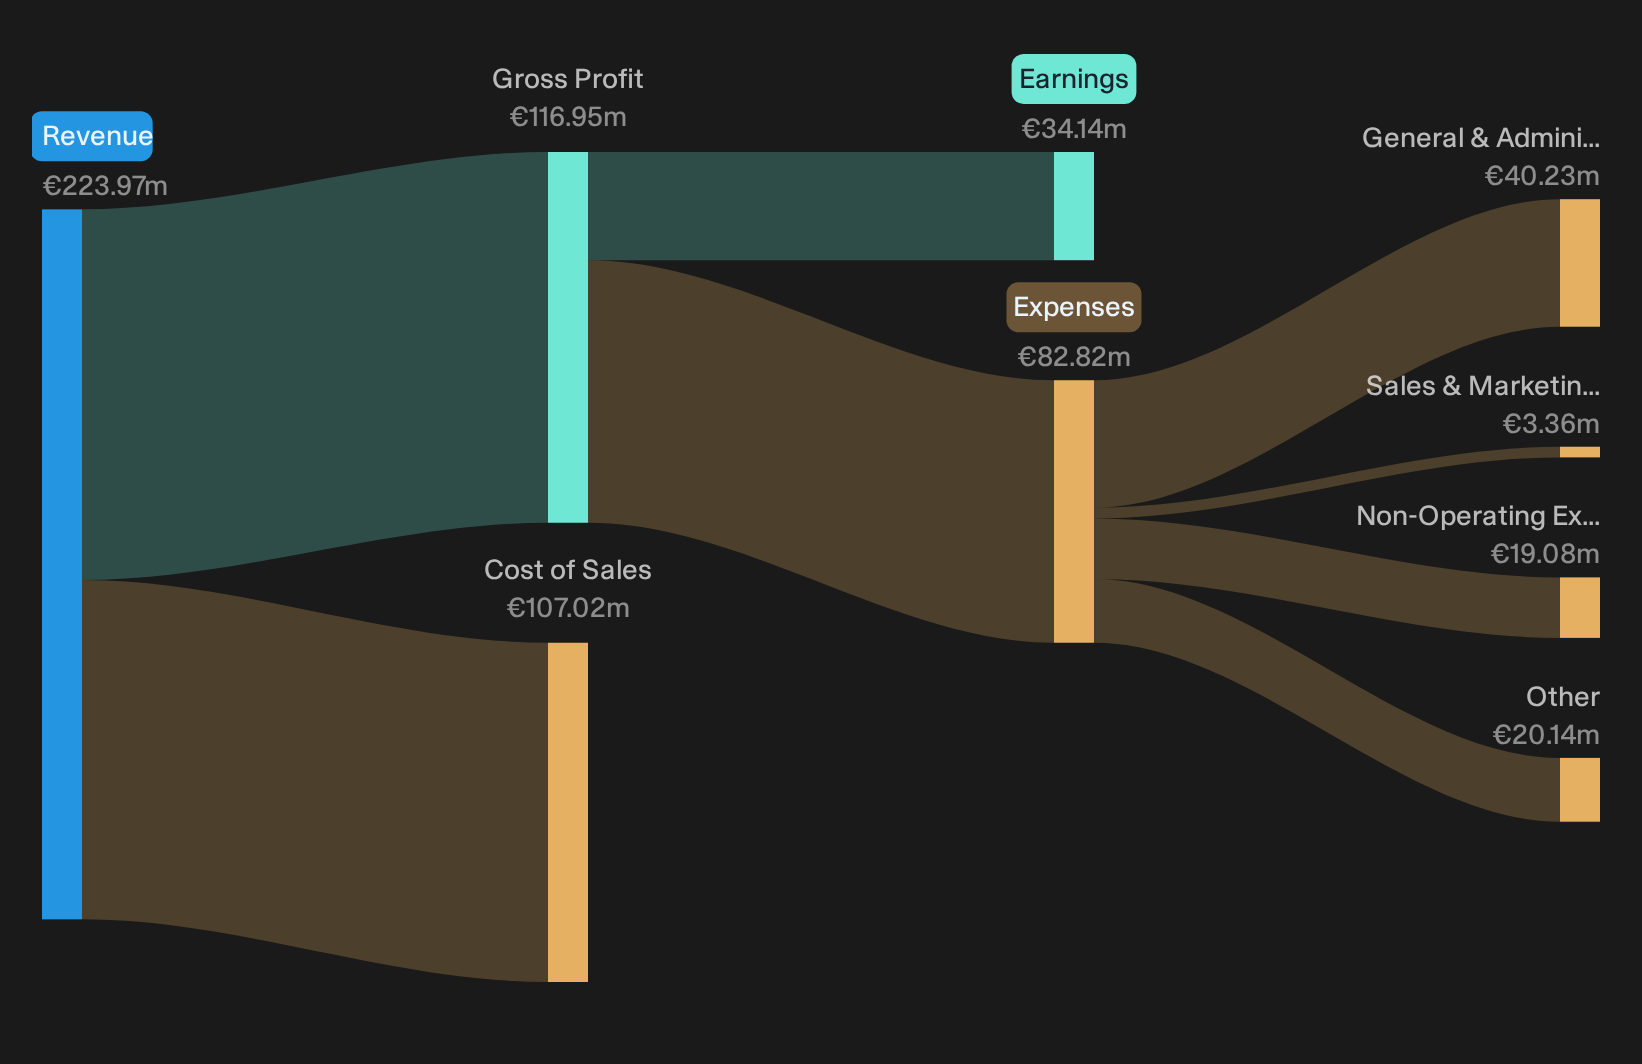
Framery bullish story meets resilient earnings
Framery Group Oyj gives supporters something concrete to point to. Revenue nudged up to about €53.6m while net income moved to €9.53m and adjusted EBIT margin held at 23.7%. That mix of steady top line and firm profitability fits a thesis that pricing, product mix and smart office offerings can help keep returns healthy even when unit volumes soften. Cash generation also looks supportive, with Q3 operating free cash flow of €10.8m and cash conversion near 75%, which backs the idea of a self-funded model for growth and capital returns.
Framery risks still visible but more balanced
Bears focus on cyclic office spending and leverage, and the latest numbers only partly echo that caution. EMEA and APAC are described as softer, which keeps demand risk in view for Framery Group Oyj. At the same time, net debt at roughly 1.1x adjusted EBITDA is well below the firm’s own ceiling, which moderates balance sheet concerns. Margin pressure from Gradus start-up costs is present but contained, with overall adjusted EBIT margin steady at 23.7%, so profitability is not indicating near-term stress.
After margin headwinds from Gradus and softer EMEA and APAC orders, you might ask whether Framery Group Oyj’s leverage and cyclic exposure are fully priced in or only partly visible. Scan the independent risk analysis for Framery Group Oyj which shows 1 important warning signHunt For Quiet Fundamental Shifts
Framery Group Oyj recently highlighted how stable profitability can coexist with questions about leverage and sensitivity to economic cycles. The real opportunity is finding stocks that could be undervalued before the market fully reassesses them.
- Company 1 - 27% below our estimate - sell diagnostic and test systems utilities rely on as electrification and grid modernization projects upgrade aging infrastructure.
- Company 2 - 23% below our estimate - open new boutiques that reportedly pay back quickly while expanding higher margin digital sales tied closely to its own brands.
- Company 3 - 38% below our estimate - shift toward recurring critical care equipment and infection control products as quality related costs are planned to decline from recent peaks.
That is three of the list. See every one of the 197 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com