


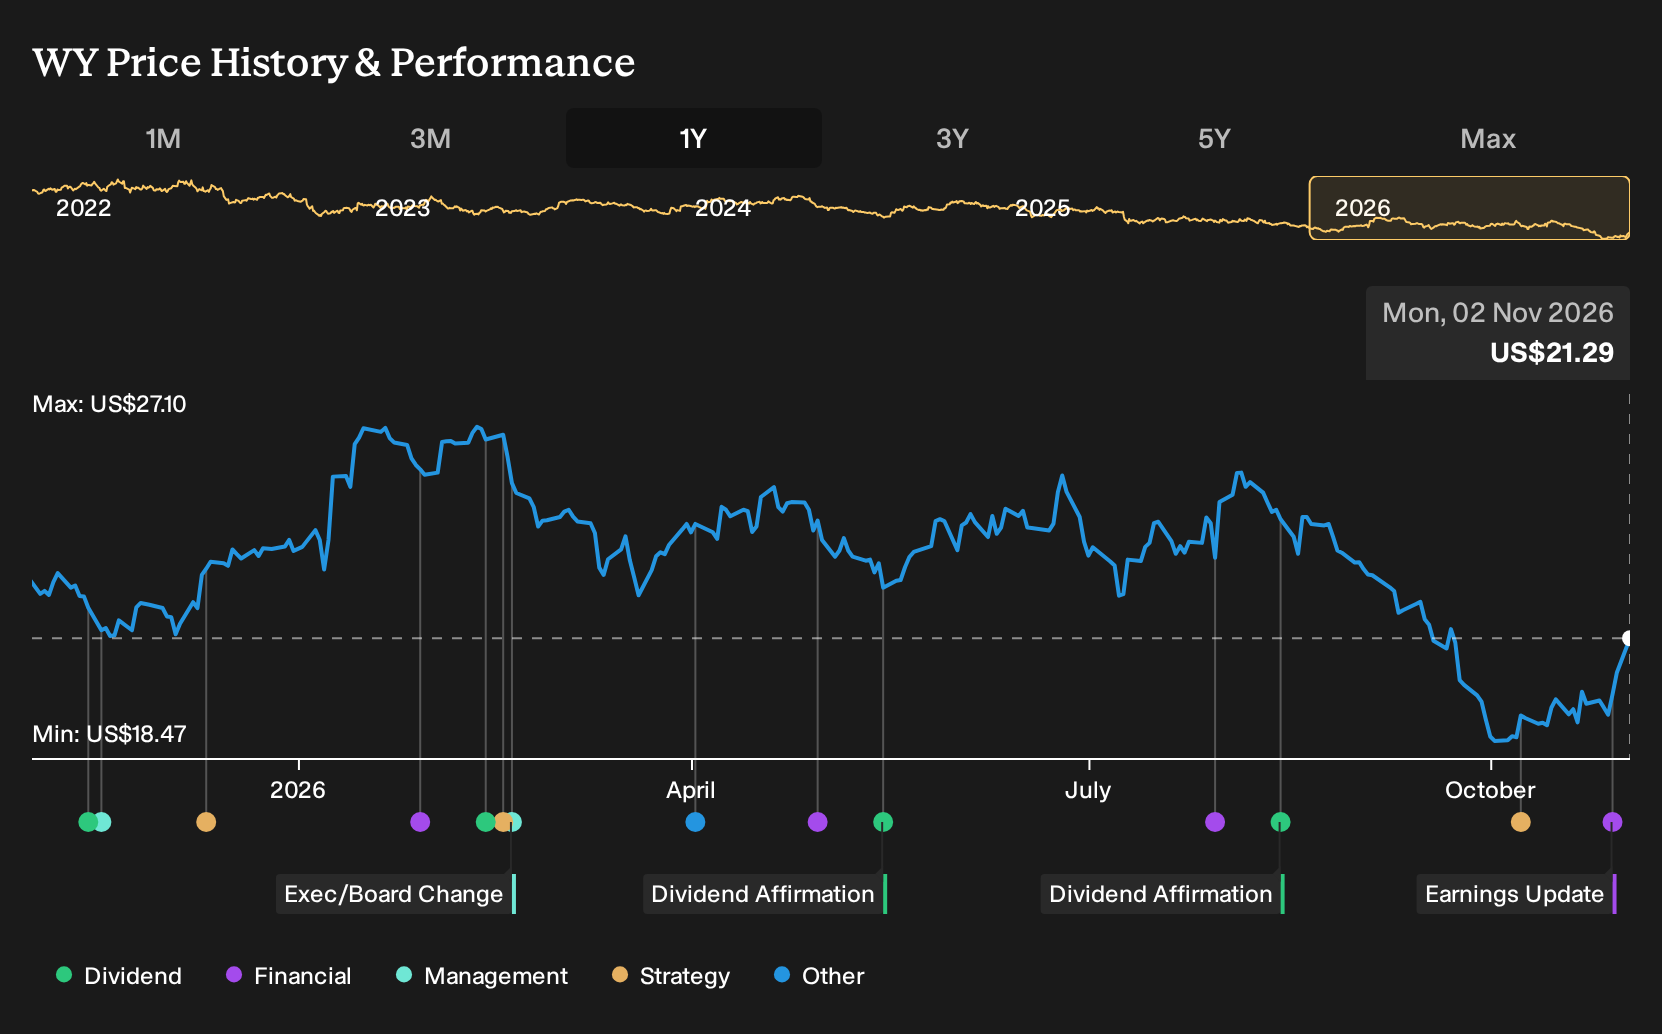
- Weyerhaeuser reported third quarter 2026 net income of US$61 million versus US$80 million a year earlier, while nine month net income reached US$379 million compared with US$250 million. Management paired these results with plans to reduce 2026 capital expenditures and allocate proceeds from non core timberland sales to share repurchases.
- The decision to trim upcoming capital expenditures and recycle divestiture cash into buybacks, while keeping the Monticello TimberStrand project on track despite higher costs, highlights how Weyerhaeuser is balancing growth investments with a tighter capital return focus.
- We will now look at how Weyerhaeuser's lower 2026 capital expenditure plans and redirected divestiture proceeds could reshape its broader investment narrative.
Scan how Weyerhaeuser's capital shift compares with other balance sheet focused opportunities by reviewing the curated list of solid balance sheet and fundamentals (24 results).
Weyerhaeuser Investment Narrative Recap
To own Weyerhaeuser, you need to believe the timberlands, wood products and newer climate and energy businesses can steadily turn its large asset base into consistent cash, even when housing and panel markets are soft. The latest quarter showed net income of US$61 million, which is below last year, so near term execution still leans on cost discipline.
The trimmed 2026 capital spending plan, coupled with using non core timberland sale proceeds for buybacks, points to a tighter focus on free cash and balance sheet flexibility. That helps the short term story, while key risks remain weak oriented strand board economics, subdued housing activity and leverage that is already elevated.
The most relevant update here is the third quarter and nine month 2026 earnings release. Net income reached US$379 million for the nine months compared with US$250 million a year earlier, with basic earnings per share from continuing operations at US$0.53 versus US$0.35.
For you, the link to catalysts is about capacity to fund projects like the Monticello TimberStrand mill, the biocarbon venture with Aymium and growing solar and wind options without stretching the balance sheet. Stronger year to date earnings give Weyerhaeuser more room to pursue those plans while still addressing interest coverage and dividend sustainability concerns.
Weyerhaeuser's analyst narrative assumes annual revenue growth of 6.9%, with earnings moving from $472.0 million today to a forecast $631.3 million by 2029, an increase of about $159 million. It highlights projected 2029 revenue of $8.4 billion and earnings of $631.3 million as the key anchors for those long term estimates.
Uncover why Weyerhaeuser's fair value indicates a 29% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
One bullish twist in the Weyerhaeuser story focuses on higher earnings potential from Climate Solutions and land income. The most optimistic analysts were penciling in revenue of about US$9.0b and earnings of roughly US$780.7 million by 2029 before this earnings update. You can use these numbers as a reference point and explore how this fresh capital spending news might shift those views.
Explore 3 other Weyerhaeuser fair value estimates, including one that suggests potential upside of up to 327% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Weyerhaeuser research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Weyerhaeuser. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Weyerhaeuser's overall financial health at a glance.
Looking for more Weyerhaeuser style investment ideas?
If you like the way Weyerhaeuser combines hard assets with a clear capital plan, it can help to widen the net and compare it with other listed businesses that share traits you care about most, whether that is valuation, balance sheet strength or dividend income.
- For investors who focus on price relative to quality, scan a curated set of potentially mispriced opportunities through 34 high quality undervalued stocks.
- If capital preservation ranks high on your checklist, concentrate on companies with sturdier finances by reviewing a targeted 29 resilient stocks with low risk scores.
- When you want growth potential without ignoring balance sheet discipline, search for under-the-radar opportunities via a focused 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com