


The Morning Bull - Australian Market Morning Update Tuesday, 3 Nov 2026
Australian shares are set for a softer open, with sentiment dominated by the Reserve Bank of Australia’s latest move to tighten policy. The fresh rate hike signals a tougher backdrop, so futures pricing now reflects a cautious tone.
The RBA lifted the cash rate to 4.85% in November, the highest level since 2008, in a split 6-3 decision. That outcome points to a board grappling with persistent inflation pressures while still acknowledging global risks from conflict and technology driven demand.
Higher local borrowing costs typically lift mortgage and business loan rates, which can pressure household spending and compress profit margins over time. Equity investors often respond by reassessing valuations that relied on cheaper funding and more generous earnings expectations.
The unresolved question is how long this higher for longer stance lasts. Attention now turns to the RBA statement and press conference, where any guidance on potential growth trade offs could influence the current cautious positioning in Australian markets.
Stocks to Watch Before the Opening Bell
GQG Partners (GQG)
Performance pressure is front and centre for GQG Partners after its CIO flipped from sceptical to positive on AI stocks and the US$11.9b US equity fund lagged the MSCI World Index by roughly 10% last month. Attention now sits on client retention and any tweaks to this AI tilt as performance data for the next few months comes through.
Peet (PPC)
Scheme paperwork for Peet is moving ahead after the Federal Court approved a shareholder meeting to vote on Ingenia Communities Group’s proposal to acquire 100% of the company. ASIC has registered the Scheme Booklet and an independent expert has called the deal fair and reasonable. Retail holders now face a timetable of meetings and election deadlines through December.
Dicker Data (DDR)
Dicker Data has closed its purchase of Sektor Group, funded through extended debt facilities. Sektor generated NZ$440m in gross revenue and NZ$22.7m in normalised EBITDA for the year to 31 August 2026, with management targeting NZ$28m to NZ$32m of annualised EBITDA contribution. Investors will focus on integration progress and how the new POS and mobility categories bed into existing operations.
Top Movers
- Qantas Airways (ASX:QAN) surged 6.36% as easing oil prices supported margin expectations and dividend confidence among traders.
- Barrenjoey Group (ASX:BJY) gained 6.14% with sentiment tied to sector interest ahead of Magellan Financial Group’s February result.
- Lendlease Group (ASX:LLC) climbed 5.51% after confirming completion of its Exhibition Place build to rent tower in Brisbane.

Top Losers
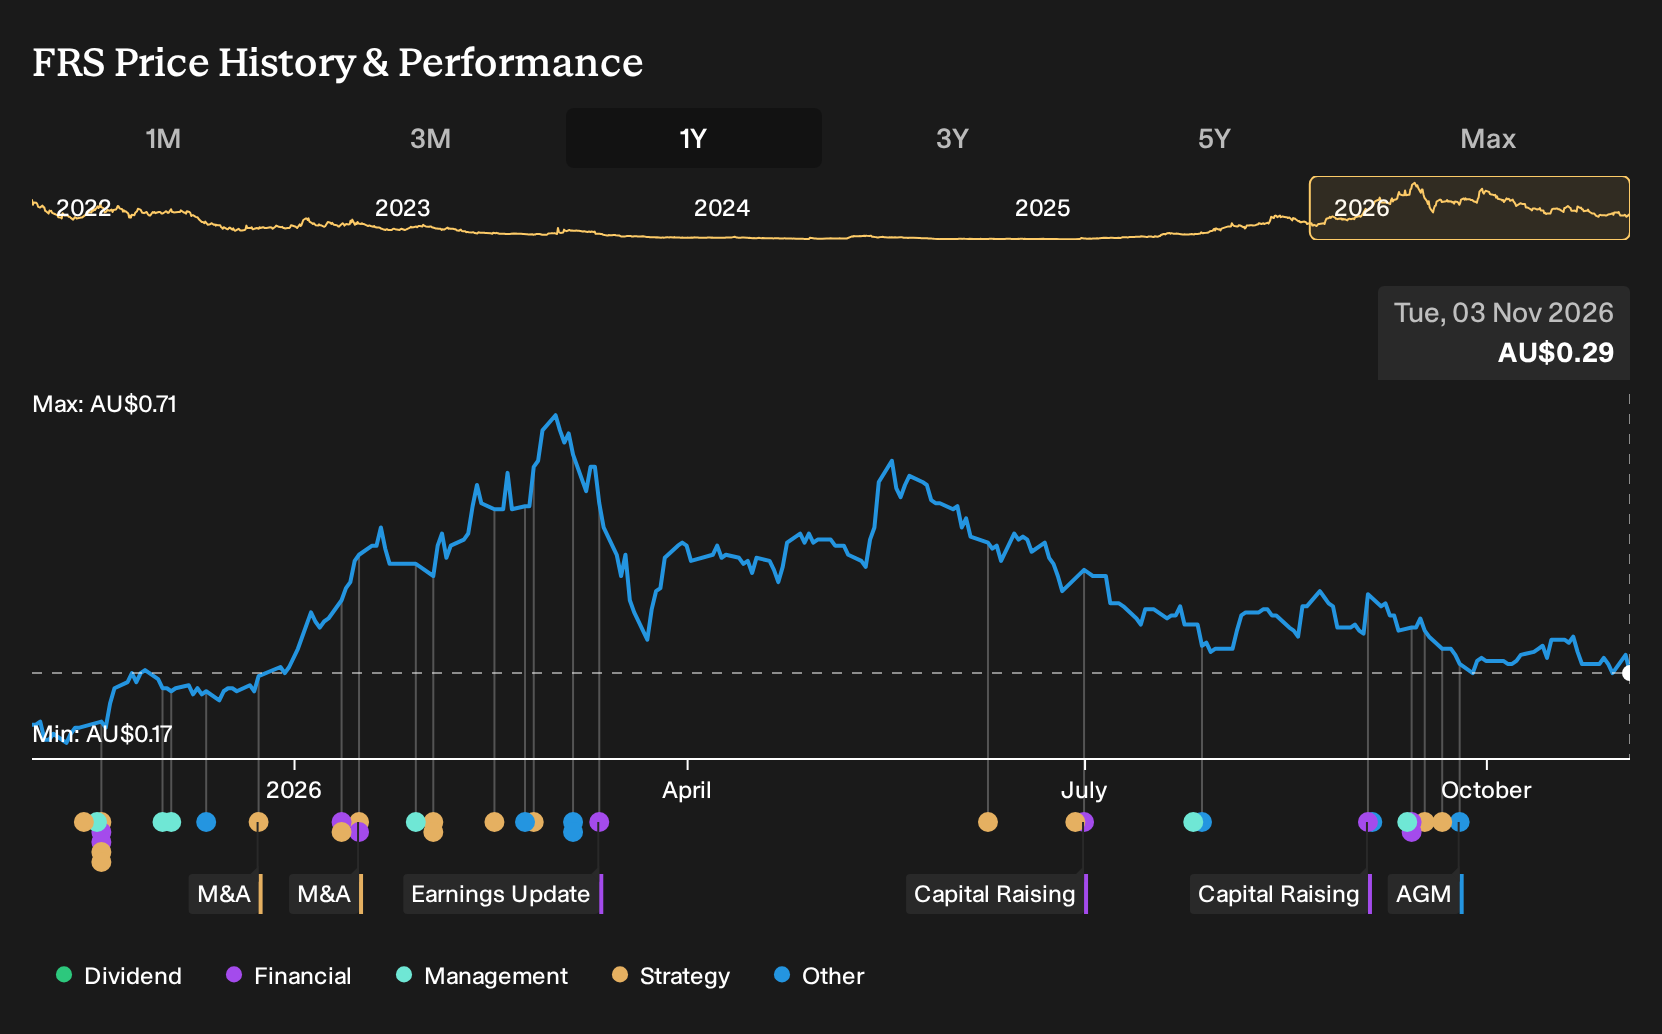
- Forrestania Resources (ASX:FRS) declined 9.38%.
- 4DMedical (ASX:4DX) fell 7.31% after management addressed an ASX query on recent volatility and increased short interest.
- Yancoal Australia (ASX:YAL) slipped 6.42% following recent disclosure on renewed coal transaction agreements with Glencore and Anotero.
On The Radar
Australian trading over the next few days revolves around the RBA move, fresh local trade data and a heavy run of bank and blue-chip earnings.
- RBA Monetary Policy Statement, Tue 3 Nov. With the cash rate now at 4.85%, investors will be looking at updated inflation projections and any discussion of growth costs to gauge how restrictive policy may feel for banks and rate sensitive stocks.
- RBA Press Conference, Tue 3 Nov. Language around the split 6-3 vote and any indications of what might shift the board toward future moves will matter for expectations on mortgage rates, the Australian dollar and equity risk appetite.
- Australia Balance of Trade, Thu 5 Nov. The September surplus consensus sits at A$1b compared with A$0.495b previously. A weaker figure would flag softer support for resources and the currency from export receipts.
- National Australia Bank, Thu 5 Nov. Full year 2026 results place attention on lending margins and bad debt charges. These feed directly into how sustainable dividend settings look across the major Australian banks.
- ANZ Group Holdings, Mon 9 Nov. Fiscal 2026 earnings will highlight how higher interest rates are feeding through to net interest income and funding costs. This will set a reference point for broader sentiment toward financials on the ASX.
Sector & Industry Watch
Banks Mixed signals from rates and housing
Banks have edged higher over the past week and month, while 1 year returns are close to flat. A 4.85% cash rate supports interest margins, at the same time Commonwealth Bank economists now expect national dwelling prices to fall around 14% from peak to trough. That mix means stronger income on each loan but more pressure on new lending volumes and mortgage stress.
If you rely on bank dividends, focus on National Australia Bank’s full year 2026 result on Thursday. Detail on arrears, bad debt charges and housing loan growth will help you judge how this higher rate setting is flowing into capital buffers and future payout decisions across the major banks.
Real Estate REIT recovery tested by higher yields
Real Estate has delivered solid 7 day and 30 day gains, while the sector still shows weaker year to date and 1 year numbers. The new 4.85% RBA cash rate lifts borrowing costs for landlords, and Commonwealth Bank now expects a sizeable national housing downturn, which together put pressure on both rental income and underlying property values.
If you hold REITs for income, the RBA Monetary Policy Statement and press conference later today are key. Any detail on funding costs, housing demand or bank funding spreads will help clarify how secure current distribution settings look as existing debt is refinanced at higher yields.
Materials and Metals and Mining Short burst higher after tough month
Materials and Metals and Mining show strong 7 day returns a little above 4%, after a weaker 30 day patch and flat year to date lines. Company news is busy, from BHP’s Resolution Copper progress and sector wide value losses since February to drilling updates and capital raisings across gold, lithium and critical minerals. That points to plenty of project level activity even as global miners have shed value since early 2026.
If your portfolio leans heavily toward miners, Thursday’s Australia Balance of Trade release is the main data check. Export figures for iron ore, copper and coal will indicate whether this recent bounce has support from actual shipment volumes or is mostly a short term sentiment recovery after earlier selling.
Energy and Oil and Gas Higher rates meet firm medium term returns
Energy and Oil and Gas have recorded positive 7 day and 30 day performance on top of firmer year to date and 1 year figures. Recent headlines include Invictus Energy’s production sharing agreement in Zimbabwe and Noble Helium’s Kinambo 1 drilling plans, alongside lower oil prices that have given Qantas and other fuel users some breathing room on costs. That combination means producers still benefit from past commodity strength while users briefly enjoy cheaper input prices.
If you are exposed to both resource stocks and fuel hungry sectors like airlines, tonight’s US API crude inventory data is the key global catalyst. Any sharp move in crude can quickly change earnings expectations for ASX energy companies and margin assumptions for transport and logistics businesses.
Healthcare and Pharmaceuticals & Biotech Gradual rebuild helped by product milestones
Healthcare has moved higher over the past month after a softer 1 year period, and Pharmaceuticals & Biotech show stronger 7 day gains supported by stock specific news. Orthocell’s partner Marine Biomedical secured US FDA clearance for its PearlBone bone graft, Clever Culture Systems raised A$2.6m to expand its APAS product range, and Neuren gained another US Orphan Drug Designation. These updates keep attention on individual pipelines, funding and early revenue rather than broad sector moves.
If you own Healthcare or Pharmaceuticals & Biotech stocks, upcoming company milestones usually matter more than macro data. Watch for trial updates, US approvals and first sales reports, since these tend to move valuations far more than the latest RBA decision or offshore PMI readings.
Where Are The Opportunities Now?
With the RBA cash rate now at 4.85% and bank dividends under closer scrutiny, you can stress test your income focus using this list of 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com