


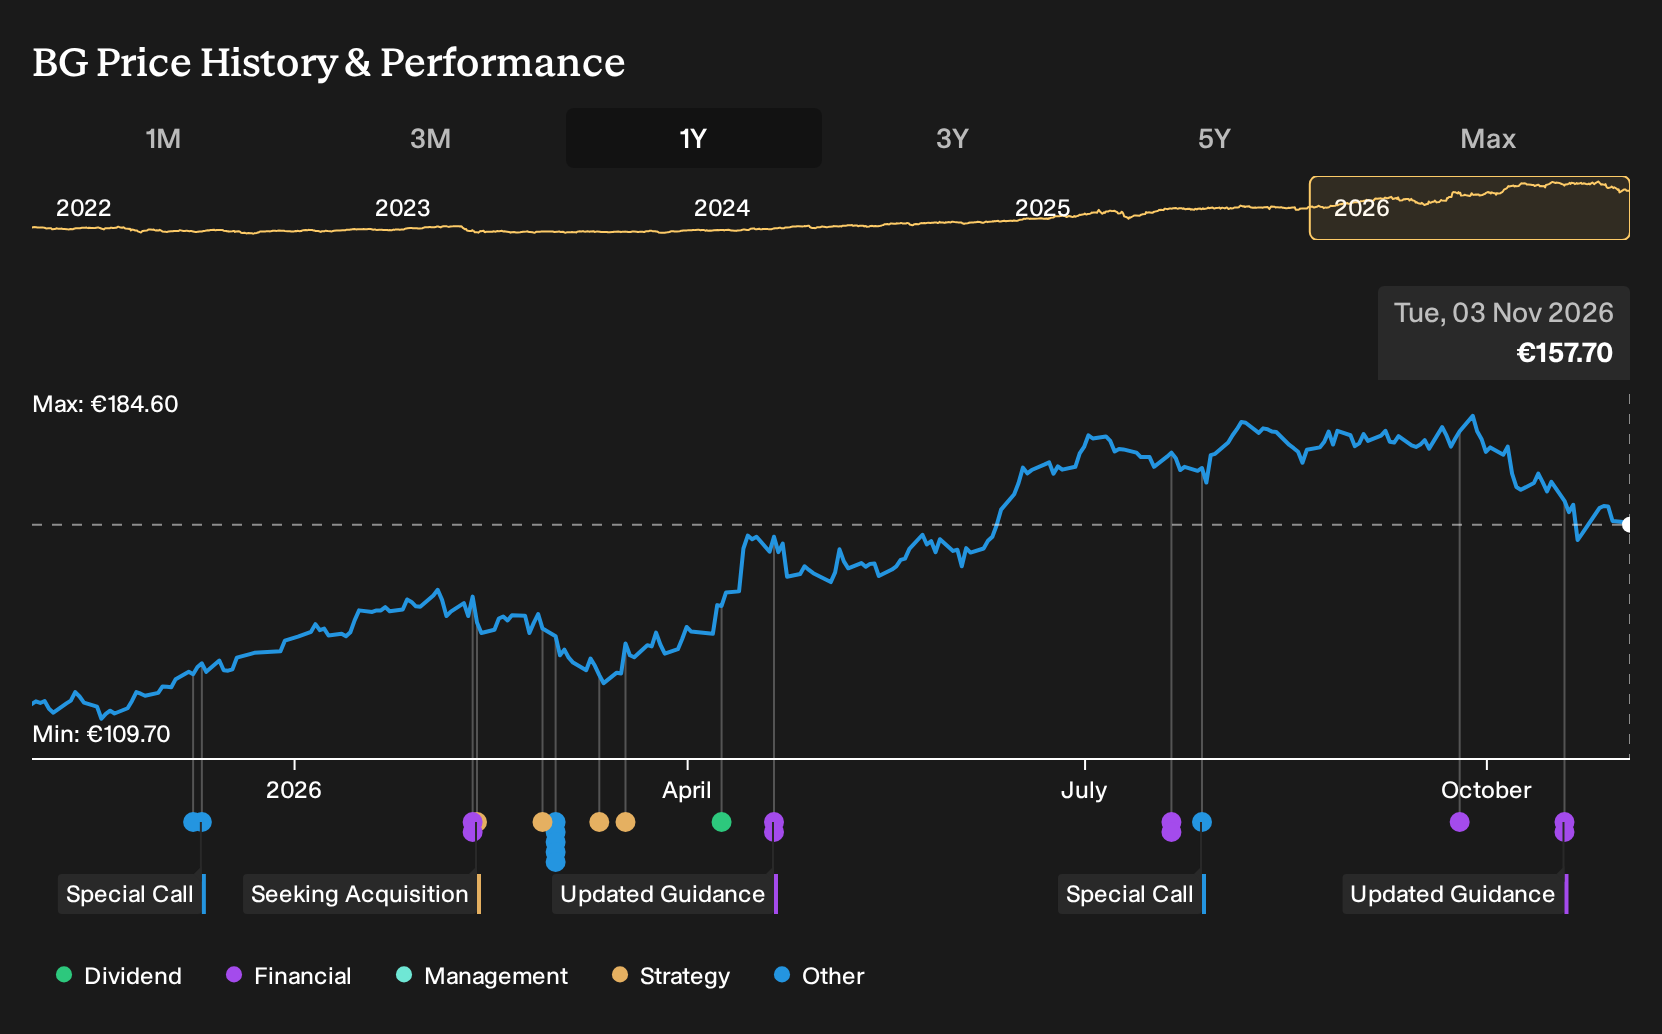
If BAWAG Group had been on your watchlist rather than in your portfolio, the last 12 months may feel like a costly what if. Investors who held BAWAG Group over the past year are up 44.7%, including dividends. That return invites a simple question. Back in November 2025, could you have spotted that faster digital integration and cross border consolidation ambitions might matter more than worries about DACH reliance and fintech pressure?
If the move has made BAWAG Group harder to judge, start where the gap is still open and scan 197 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On BAWAG Group
The shares cost €114 at the start of the period and BAWAG Group sat between two sharply different stories about what might come next.
On the optimistic side, the bullish narrative pointed to a fair value of €148.47, a price that depended on its assumptions playing out, with confidence that rapid digital integration and European consolidation could support sector leading profitability.
The bearish view anchored on a fair value of €89.03 based on its own scenario, stressing risks from fintech competition and heavy DACH exposure that could restrict growth and pressure returns if those threats bit harder than expected.
What The Results Changed For The BAWAG Group Story
The most telling update came from BAWAG Group’s reported Q3 2026 figures. Revenue reached €526.2 million and net income hit €247.5 million, with net margin at 47.0%. Those numbers leaned toward the optimistic case that talked about sector leading profitability but did not remove the bear concerns around concentration and fintech pressure, so the evidence cut both ways.
The lesson is simple. When a thesis hinges on profitability quality, track net margin and absolute profit in each quarterly release and compare both to the original claim rather than the share price chart.
What You Would Be Paying For In BAWAG Group Today
At a current share price of €158, this Narrative’s Fair Value sits above the market level, based on its own assessment of BAWAG Group’s earnings power and capital flexibility.
The core pitch leans on self funded expansion and the PTSB deal. A buyer today would need to believe that unsecured lending growth can be managed without a sustained step up in risk costs.
"Planned use of excess CET1 capital, which currently sits well above the 12.5% target at 15.4% pro forma in Q1 2026 and 17.4% in Q2 2026, together with €14 to €15 billion of cash and an underinvested securities portfolio, gives BAWAG Group room to self-fund growth and potentially expand revenue and net income without relying on external capital."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 34% below our estimate - targets higher value nutrition segments using a broadening product range and export reach.
- Company 2 - 45% below our estimate - converts housing underbuild and public works demand into higher margin modular projects.
- Company 3 - 30% below our estimate - channels rising AI workloads onto its cloud platform through unified pricing and infrastructure.
Those are three of them. See the full list of 196 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com