


Tyson Foods has delivered a 36.0% share price gain over the past three years, which puts fresh focus on whether that move is supported by the company’s earnings power at today’s price. With the stock recently closing at US$57.08, the question for investors is how much of Tyson Foods’ profit profile is already reflected in that tag.
- The 36.0% return over three years raises the issue of whether recent shareholders are paying a price that fairly reflects Tyson Foods’ earnings today and its potential to sustain them.
- The business depends heavily on converting a mature protein portfolio into consistent profit and cash flow, so any shift in costs or pricing power can quickly change what investors are willing to pay for each dollar of earnings.
- The analysts covering Tyson Foods have run their own numbers. See what analysts think Tyson Foods's shares could be worth.
The issue now is whether Tyson Foods’ current share price is justified by the earnings it is generating and what that implies for investors considering the stock today.
If you are evaluating whether Tyson Foods’ earnings multiple feels fair, it can help to compare that question across 34 high quality undervalued stocks.
Is Tyson Foods Still Cheap on Earnings?
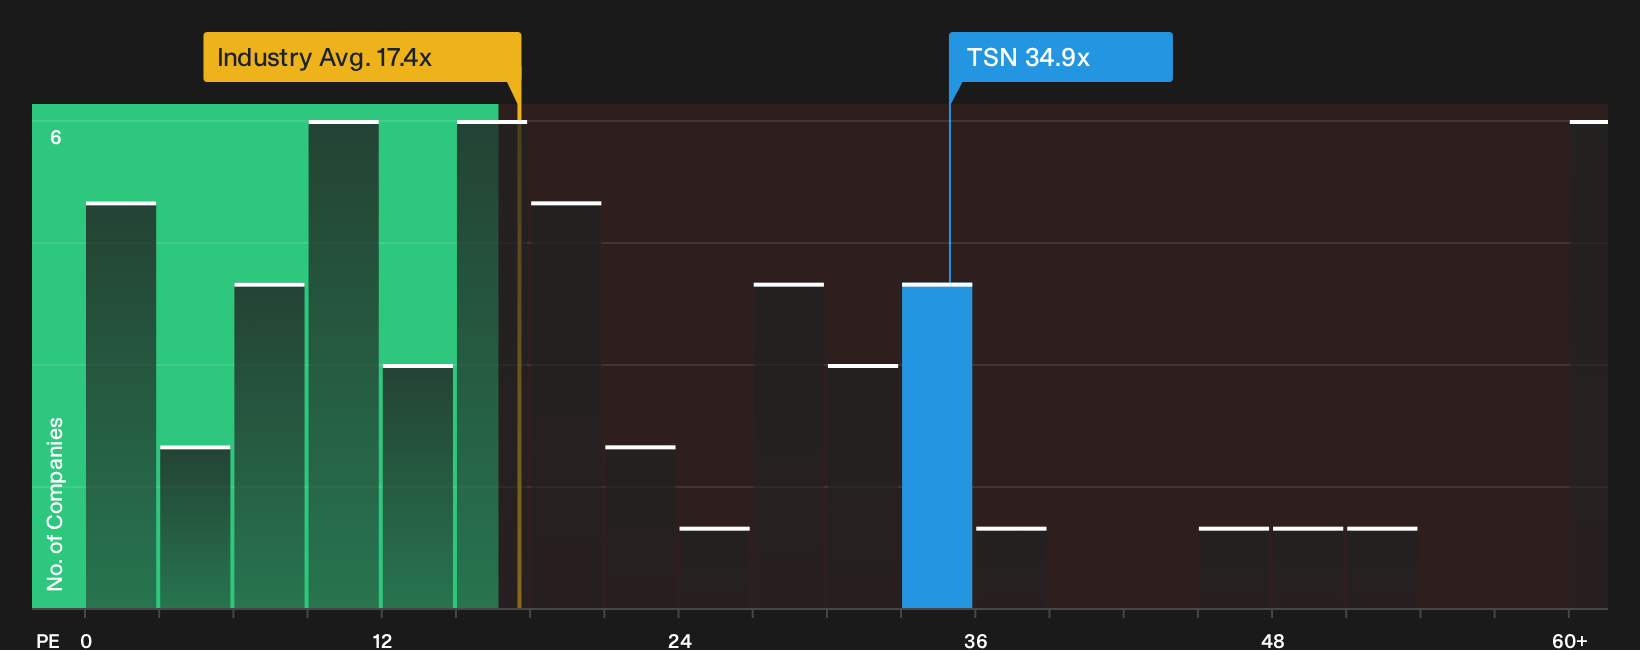
For Tyson Foods, the P/E ratio is a useful shortcut because earnings remain a primary reference point for how the market prices a mature food producer. The stock trades on roughly 34.9x earnings, which is well above the broader food industry average of about 17.4x and also higher than the peer group near 25.3x.
The valuation model that backs out a tailored fair P/E, based on Tyson Foods’ own mix of growth expectations, profitability and risk, points to a lower earnings multiple than where the shares change hands today. That gap suggests investors currently accept a richer earnings price tag than this framework would imply. It also means more emphasis is placed on the company continuing to justify that confidence through its future profit profile. Explore the numbers behind Tyson Foods's P/E valuation.
The Tyson Foods Narrative: What Would Justify Today's Price?
Narratives on Tyson Foods pick up where the valuation question leaves off, spelling out which expectations around future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price. Each one treats Tyson Foods' implied fair value as a thesis about how the business might perform that you can revisit over time. They are available on Simply Wall St’s Community page.
Community views on Tyson Foods split between investors who see more upside in the shift toward Prepared Foods and Chicken and those who think recent guidance and beef issues already cap the opportunity.
Bull case: 9% undervalued
"Continued mix shift at Tyson Foods toward branded and value-added Prepared Foods and Chicken, supported by multiple quarters of segment volume and sales growth and higher-margin pull-driven contracts..."
Discover why this Narrative puts Tyson Foods at 9% undervalued.
Bear case: roughly fairly valued
"The current numbers and guidance ranges imply a share price that already reflects a fairly valued Tyson Foods with both the earnings drag from Beef and the contribution from Prepared Foods, Chicken, International and cost efficiency gains..."
Explore why this Narrative puts Tyson Foods at roughly fairly valued.
One more Tyson Foods angle that could shift how you see this stock
Everything so far has focused on what Tyson Foods looks like today, yet analyst models sketch out where earnings and cash generation might sit a few years from now, and that comparison with the current price is worth a separate look. Explore where analysts expect Tyson Foods to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com