


Coloplast just reported Q4 2026 and the share price closed at DKK495.7 after a strong run over the past month. The mood around the stock is upbeat. The headline story inside the report is less about the income statement and more about valuation nerves meeting a margin reset.
The company still trades on a rich P/E of 36.3x, while trailing net profit margin sits at 10.6%. That combination creates a sentiment clash. Short term traders are cheering the print. Longer term holders are staring at a high multiple on compressed profitability and a recent DKK3.2b impairment and wondering who is misreading whom.
Love the strong recent share price move in Coloplast but concerned about paying 36.3x P/E for a business with a 10.6% net profit margin and a fresh DKK3.2b impairment on the books? Check out our list of solid balance sheet and fundamentals stocks (196 results).
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs. Q4 2025): DKK 7,459m vs. DKK 6,960m (up about 7%)
- Net Income, Excl. Extra Items (Q4 2026 vs. Q4 2025): DKK 1,186m vs. DKK 875m (up about 36%)
- Basic EPS (Q4 2026 vs. Q4 2025): DKK 5.26 vs. DKK 3.88 (up about 36%)
- Trailing 12-Month Net Profit Margin (FY 2025 to 2026 vs. prior year): 10.6% vs. 13.0% (margin contracted, also affected by a DKK 3.2b one off loss)
Coloplast cut its long‑term growth and margin ambition. Ask Charlie what Coloplast’s lower 2030 targets really signal.
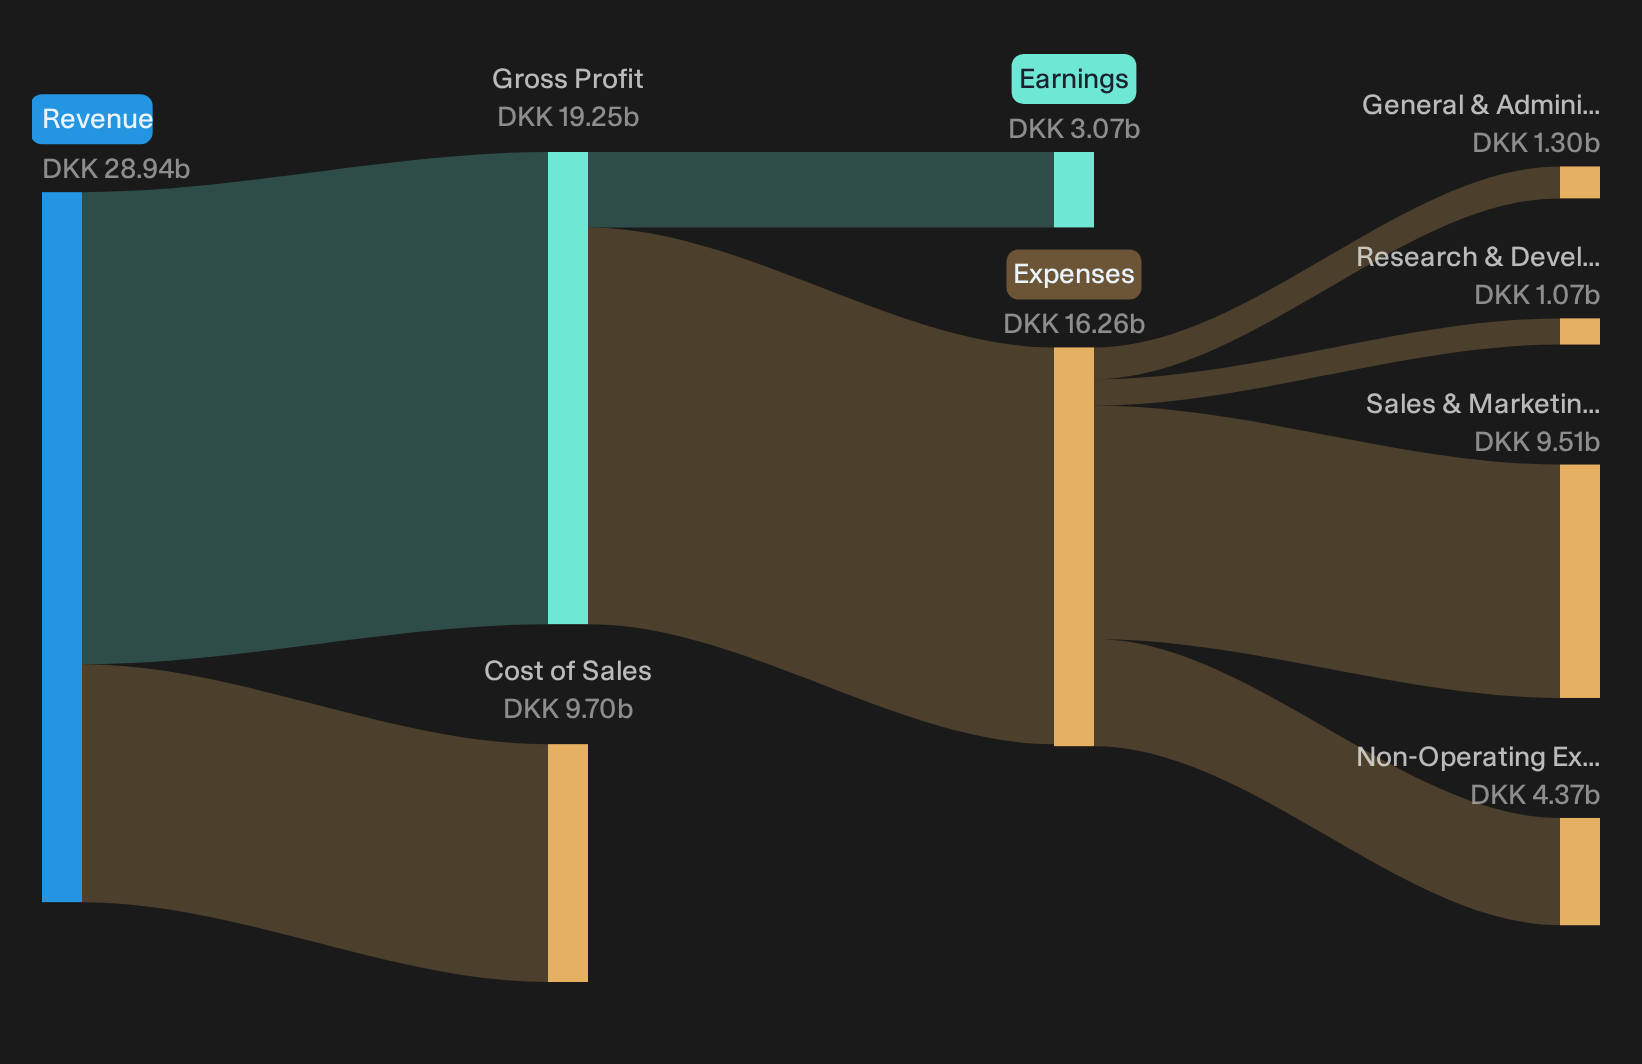
Coloplast growth ambitions meet a more grounded plan
Coloplast bulls argue that a richer mix and efficiency push will steadily lift profitability. That hinges on a clear upgrade in earnings power over time rather than just solid sales momentum.
"Ongoing industrial scaling and footprint optimization, including new cost efficient manufacturing in Portugal and ramp up in Costa Rica, together with efficiency programs in Wound Care and Interventional Urology, are set to unlock next level cost savings and improve net margins and free cash flow conversion."
Current numbers partially line up with that script. Free cash flow is strong at DKK 6.3b and cash conversion is 98%. At the same time, the EBIT margin before special items moved to 26% and guidance now points to around 25% in the near term and only the mid 20s by FY29 to FY30, which is softer than the earlier high margin ambition.
The price and this Narrative do not agree. → Uncover what this Narrative says Coloplast is actually worth.
Coloplast Bear Case: Biologics And China Still Drag
Bearish investors worry that Coloplast’s weaker growth engines will offset solid Chronic Care and Interventional Urology momentum.
"While Kerecis inpatient procedures currently grow at a healthy double digit rate and account for more than 70% of that business, the sharp reset in outpatient volumes and a guidance cut for FY25/26 Biologics growth to around 0%, combined with a DKK 3.0b goodwill impairment and an EBIT margin outlook of about 0%, increase the risk that future group earnings and return on invested capital could fall short of expectations that still rely on a quicker Biologics recovery."
The latest year largely reflects that concern. Biologics declined about 12% and triggered a DKK 3.0b impairment, pulling roughly 40 bps off group EBIT margin. China Ostomy also weakened, so 6% organic growth depended heavily on healthier franchises while the pressured areas did not yet recover.
Hunt For Mispriced Earners
Coloplast has released updated results and a higher share price that prompt investors to reconsider what the valuation reflects. The real opportunity could be in finding stocks that could be undervalued before the market adjusts their pricing.
- Company 1 - 42% below our estimate - build out new manufacturing and supply capacity so higher margin film and services can support a larger customer base.
- Company 2 - 37% below our estimate - extend long term security and facility contracts as labour rule changes and acquisitions feed into higher earnings efficiency.
- Company 3 - 43% below our estimate - scale large digital display projects and software services as more venues and transport networks switch from static signage.
Those are three of them. See every one of the 199 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com