


Cohu has had a striking 12 months in the market, and with the stock last closing at US$50.03 the real question for you now is whether that price can be backed up by the cash the business is expected to generate. With the focus squarely on its cash flows, the Discounted Cash Flow (DCF) intrinsic value estimate becomes a useful lens for judging how far the recent share-price story lines up with the underlying economics of the company.
- The stock has gained 120.7% over the past year, so a big part of the recent move now rests on whether that rally is supported by the cash the business can produce over time.
- Recent news around stronger demand for semiconductor test and inspection systems and a higher outlook for high performance computing related products may support expectations for future revenue and the timing of cash inflows that feed directly into any cash flow based valuation.
- What if you looked at Cohu through its sales instead? See why Cohu's 4.2x P/S tells a different valuation story.
For investors, the debate is whether Cohu's current share price around US$50 is justified by its projected cash flows when run through a Discounted Cash Flow (DCF) intrinsic value framework.
If you want a broader reference point for what this kind of cash flow story looks like across the market, compare Cohu with companies in the same theme using 53 AI infrastructure stocks.
Is Cohu a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here is based on what Cohu can realistically return to shareholders in cash over time. Latest twelve month free cash flow is about $49.4 million, and the two-stage setup assumes that this figure grows before settling into a slower, more mature rhythm in later years.
Those projected cash flows, when discounted back, suggest an intrinsic worth meaningfully above the current share price of US$50.03. Because recent Q3 2026 results showed stronger demand for high performance computing and thermal test systems, the raised HPC outlook helps explain why the cash flow profile used in the model points to more value than the market is currently pricing in. Find out what Cohu could be worth using our Discounted Cash Flow (DCF) estimate.
The Cohu Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Community page pick up where this valuation question leaves off by explaining what would need to happen to Cohu's growth, profitability and earnings profile for the stock to be worth meaningfully more or materially less than today’s price. Each scenario focuses less on a single multiple or model output and more on the underlying assumptions about fair value, so you can compare those expectations with future reported results.
One of the top community narratives on Cohu: 33% undervalued
"Cohu is capitalizing on the surge in high-performance computing and the complexity of modern semiconductors by rolling out advanced, configurable handler platforms and test solutions..."
Discover why this Narrative puts Cohu at 33% undervalued.
One more Cohu question the valuation does not touch
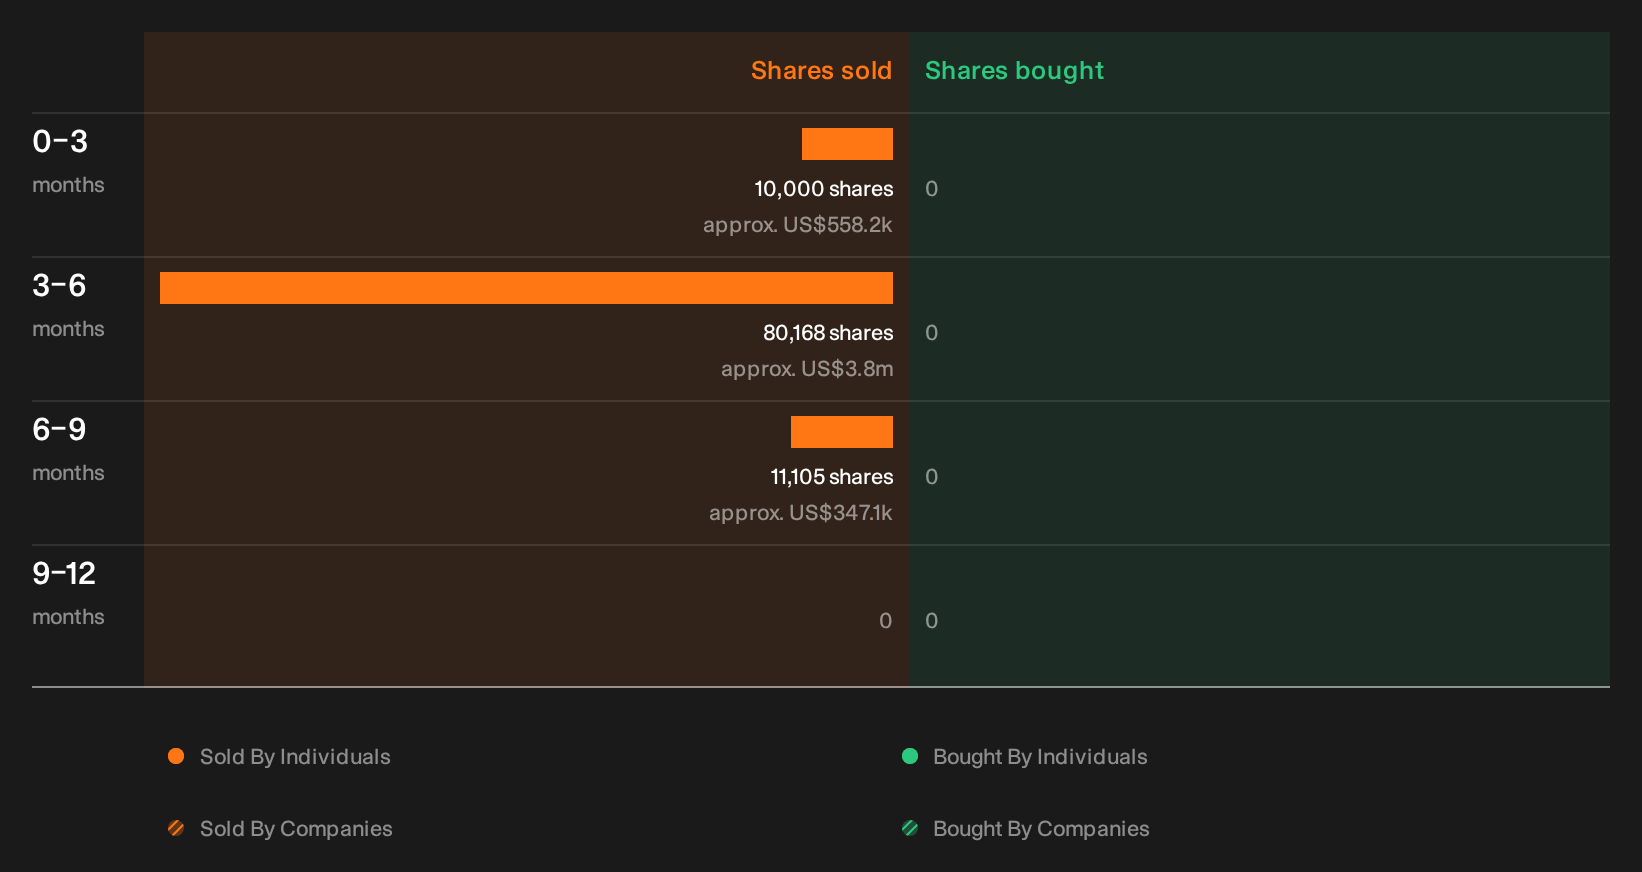
Cash flow models cannot show what company insiders have been doing with their own holdings, and recent activity by Cohu executives and directors raises a separate question that deserves a closer look. See the recent insider selling flagged for Cohu.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com